
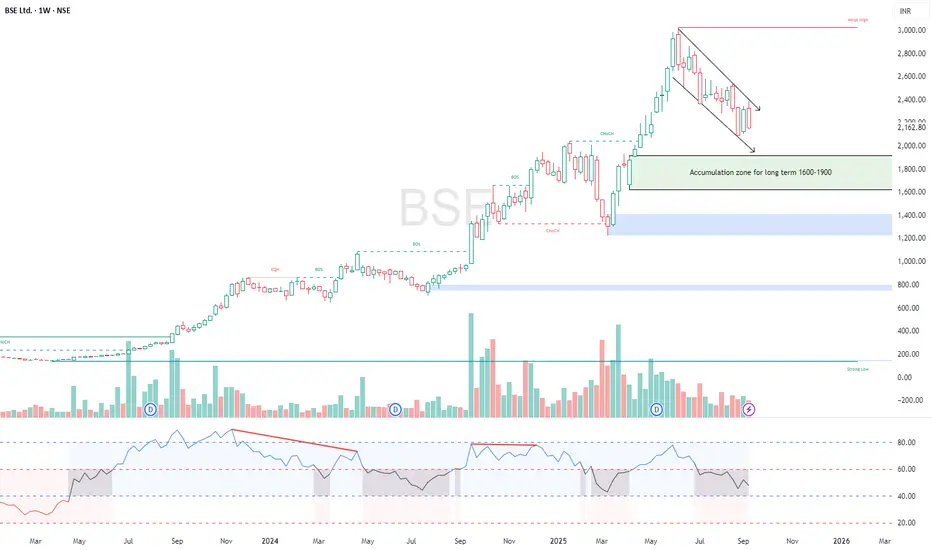
🔎 Technical View
Price: ₹2,162 (down ~6.7% this week).
Trend: Stock topped near ₹3,000, now consolidating inside a downward channel.
Support Levels:
Immediate: ₹2,000–2,100 (holding for now).
Major Accumulation Zone: ₹1,600–1,900 (highlighted on chart).
Strong structural support: ₹1,200.
Resistance Levels:
Short-term: ₹2,400–2,500 (channel top).
Medium-term: ₹2,800–3,000 (previous peak).
Interpretation: Stock is in corrective phase but long-term structure remains intact. Best risk-reward lies in accumulating between ₹1,600–1,900.
📊 Fundamental View
Business Strengths:
Monopoly-like status in equity cash segment; growing dominance in derivatives after contract redesign.
Strong network effect (volumes bring liquidity → liquidity attracts volumes).
Healthy balance sheet, cash-rich, zero debt.
Revenue visibility from transaction charges, listing, data, and annual fees.
Triggers Ahead:
Increasing derivatives volumes (BSE Sensex contracts gaining popularity).
Growth in SME and mutual fund distribution platforms.
Regulatory easing or new product launches could unlock further growth.
Risks:
Heavily dependent on regulatory stance (SEBI).
NSE competition remains tough in derivatives.
Valuations are rich compared to global peers.
📝 Long-Term Investment View
Accumulation Zone: ₹1,600–1,900 (best entry for investors).
Upside Potential: If volumes sustain and product mix improves, stock can revisit ₹2,800–3,000+ in 2–3 years.
Investment Style: SIP-based staggered buying around 1,800–2,000 reduces timing risk.
Conclusion: Structurally strong franchise with high entry barriers → a core long-term portfolio stock, but wait for better entry levels (below 2,000 ideal).

إخلاء المسؤولية
لا يُقصد بالمعلومات والمنشورات أن تكون، أو تشكل، أي نصيحة مالية أو استثمارية أو تجارية أو أنواع أخرى من النصائح أو التوصيات المقدمة أو المعتمدة من TradingView. اقرأ المزيد في شروط الاستخدام.
إخلاء المسؤولية
لا يُقصد بالمعلومات والمنشورات أن تكون، أو تشكل، أي نصيحة مالية أو استثمارية أو تجارية أو أنواع أخرى من النصائح أو التوصيات المقدمة أو المعتمدة من TradingView. اقرأ المزيد في شروط الاستخدام.