
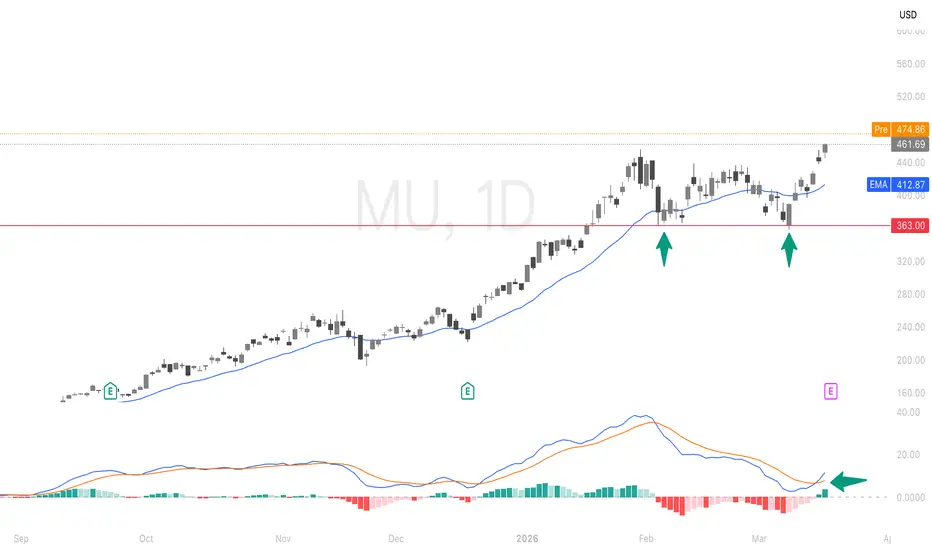
Micron (MU) is set to report Q2 earnings after the close on March 18. Technically, the daily chart has confirmed a double bottom structure with two successful tests of support, and the price is now firmly above the EMA, breaking out of the prior high range. This clear bullish trend signals strong buying momentum, laying a solid foundation for further upside.
Fundamentally, Micron is the only U.S.-based manufacturer of both DRAM and NAND, sitting at the core of the AI compute bottleneck. HBM has evolved from a commodity component to a strategic asset for AI systems, with severe supply-demand imbalances giving Micron massive pricing power. The upcoming HBM4 production will tighten capacity further—each HBM4 wafer requires the equivalent of 4 standard DRAM wafers—while cloud and mobile segments are seeing explosive revenue and margin growth, backed by multi-year customer contracts.
Fundamentally, Micron is the only U.S.-based manufacturer of both DRAM and NAND, sitting at the core of the AI compute bottleneck. HBM has evolved from a commodity component to a strategic asset for AI systems, with severe supply-demand imbalances giving Micron massive pricing power. The upcoming HBM4 production will tighten capacity further—each HBM4 wafer requires the equivalent of 4 standard DRAM wafers—while cloud and mobile segments are seeing explosive revenue and margin growth, backed by multi-year customer contracts.

إخلاء المسؤولية
لا يُقصد بالمعلومات والمنشورات أن تكون، أو تشكل، أي نصيحة مالية أو استثمارية أو تجارية أو أنواع أخرى من النصائح أو التوصيات المقدمة أو المعتمدة من TradingView. اقرأ المزيد في شروط الاستخدام.
إخلاء المسؤولية
لا يُقصد بالمعلومات والمنشورات أن تكون، أو تشكل، أي نصيحة مالية أو استثمارية أو تجارية أو أنواع أخرى من النصائح أو التوصيات المقدمة أو المعتمدة من TradingView. اقرأ المزيد في شروط الاستخدام.