
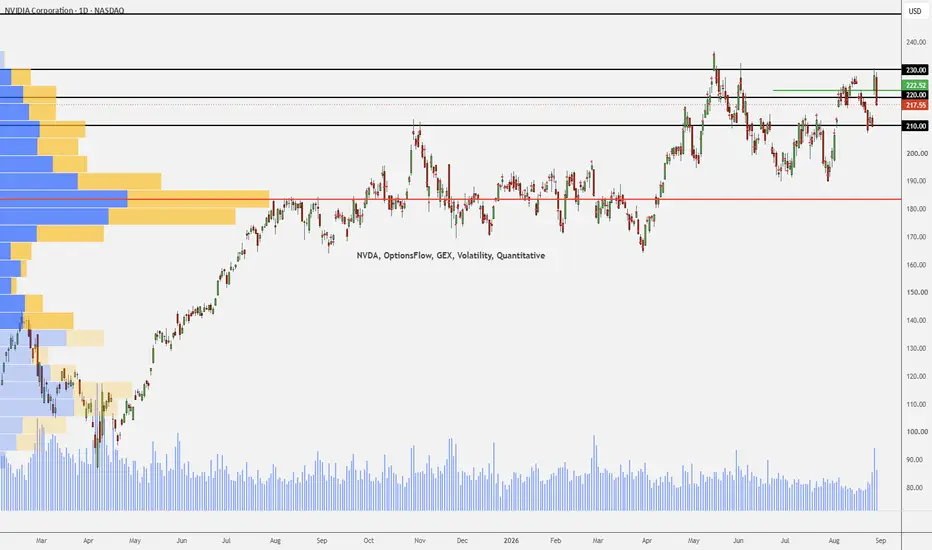
Following the recent earnings release, I analyze institutional positioning across the NVIDIA ($217.88) options chain to define key support, resistance, and liquidity levels for the upcoming trading sessions
**Quantitative Breakdown:
- Short-Term (1-4 Days): Range $215 – $220. Gamma wall at $220. A breakout above $220 opens the path to $225.
- Medium-Term (September): Support $200 / Target $230 – $240. Strong Call flow bias.
- Long-Term (Oct / Nov): Floor $175 / Upper Target $250. Healthy institutional market structure.
**Quantitative Analysis:
1. Market Diagnosis & Flow Bias:
- Sustained Bullish Sentiment: The Volume Put/Call Ratio at 0.59 (nearly 2 Calls traded for every Put) and the Open Interest Put/Call Ratio at 0.77 confirm continuous structural bullish positioning in the derivatives market.
- Volatility Contraction (IV Crush): Implied Volatility dropped to 2.02%, trading below Historical Volatility (2.50%). Earnings event uncertainty has fully collapsed out of option premiums.
2. Short-Term Key Levels (1 to 4 Days)
Resistance Wall: $220.00 Call Wall
- The Obstacle: Holds a massive 92.9K volume in the $220 Call. Market makers act as passive sellers near this strike.
- The Catalyst: To trigger a broader move (Gamma Squeeze) toward $225 and $230, NVDA needs to break and consolidate above $220.00 with high spot volume.
2.1 Immediate Support: $215.00 – $210.00 Put Wall
- Short-term buyer liquidity is concentrated at $215 (38.8K volume) and $210 (22.2K volume / 9.33K OI).
- Expected Scenario: A compressed range between $215 (support) and $220 (gamma wall) in the near term.
3. Medium & Long-Term Structure (Sep / Oct / Nov)
- Contango Volatility Curve: The IV term structure slopes upward toward late-year expirations (macro risks & Q3 earnings), allowing traders to enter longer-dated options without overpaying for short-term premium.
- Major Call Wall ($250 & $300): The largest absolute Open Interest accumulation across Sep/Oct/Nov rests at the $250 strike (>150K contracts).
- Downside Tail Protection ($175 & $200): Open Interest spikes at $175 and $200 show institutions are buying cheap Out-of-the-Money hedges rather than near-the-money protection, reinforcing the health of the broader trend.

إخلاء المسؤولية
لا يُقصد بالمعلومات والمنشورات أن تكون، أو تشكل، أي نصيحة مالية أو استثمارية أو تجارية أو أنواع أخرى من النصائح أو التوصيات المقدمة أو المعتمدة من TradingView. اقرأ المزيد في شروط الاستخدام.
إخلاء المسؤولية
لا يُقصد بالمعلومات والمنشورات أن تكون، أو تشكل، أي نصيحة مالية أو استثمارية أو تجارية أو أنواع أخرى من النصائح أو التوصيات المقدمة أو المعتمدة من TradingView. اقرأ المزيد في شروط الاستخدام.