
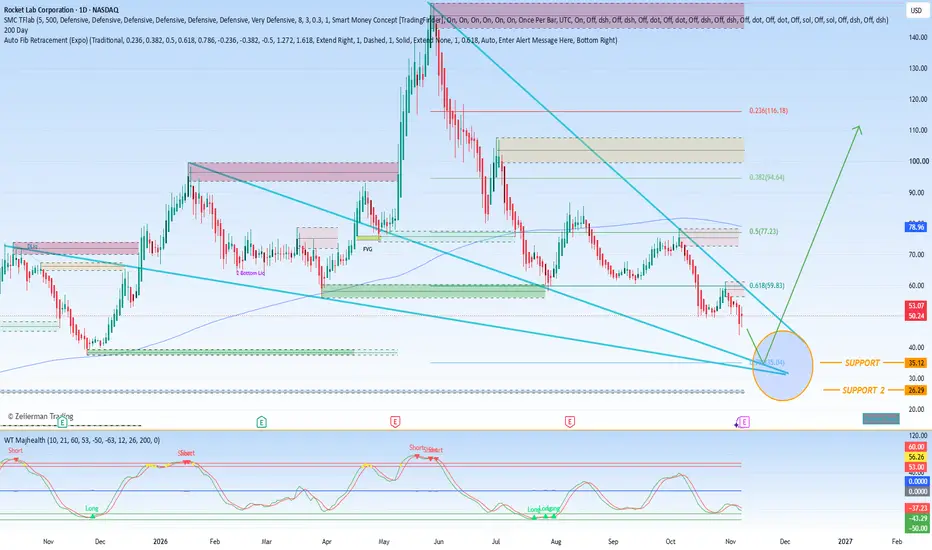
Options traders appear to believe Rocket Lab (RKLB) shares could regain some of their recent losses after the company reports its fiscal third-quarter earnings on November 9. The consensus estimate calls for the space infrastructure firm to report a loss of $0.05 per share for the quarter, which would represent a significant deterioration from the $0.01 per-share loss it reported in the same period last year. Despite that expected worsening in profitability, the options market is signaling that a meaningful amount of bad news may already be reflected in the stock price.
Heading into the earnings event, Rocket Lab stock sits nearly 70% below its year-to-date high. That steep decline has left investors wondering whether the selloff has created an opportunity or whether more pain is ahead. The derivatives market, according to Barchart data, seems to be leaning toward the idea that the downside is largely priced in at current levels.
What Options Traders Expect From Rocket Lab Stock
Even though the company is expected to report a larger per-share loss than it did a year ago, traders are increasingly favoring calls over puts. The put-to-call ratio on options contracts expiring November 13 currently stands at 0.89x. A reading below 1.00x is typically interpreted as bullish, because it means call options — which benefit from upward moves in the stock — are being traded more heavily than put options, which benefit from downward moves.
Barchart’s data also pegs the upper price target implied by those contracts at $52.33. That would signal potential for a post-earnings rally of more than 14% from current levels. In other words, options traders are not necessarily expecting a massive breakout, but they do see a reasonable chance that Rocket Lab shares bounce after the report rather than fall further.
That positioning matters because earnings events often force investors to reassess a stock’s valuation and outlook. If the company delivers results that are merely in line with expectations, or if management provides reassuring commentary on its backlog, launch schedule, and space systems business, the stock could benefit from a relief rally. The options market appears to be preparing for that possibility.
Cantor Fitzgerald Remains Bullish on RKLB Shares
Heading into the quarterly print, Cantor Fitzgerald analysts maintain a Buy rating on Rocket Lab shares. The investment firm currently has a $122 price target on the company, which implies potential upside of roughly 152% from current levels. That is a striking target given the stock’s recent weakness, and it reflects a long-term view rather than a short-term trading call.
Cantor’s bullish thesis is rooted in Rocket Lab’s growing position as a diversified space infrastructure company rather than simply a pure launch provider. The firm sees significant long-term value in several parts of the business. First, Rocket Lab’s expanding space systems segment — which includes spacecraft components, satellite manufacturing, and related services — gives the company multiple ways to generate revenue beyond launch services. Second, increasing government and defense opportunities could provide a durable source of demand, particularly as national security space programs continue to expand. Third, the upcoming Neutron rocket program could unlock a much larger addressable market by giving Rocket Lab a medium-lift launch vehicle capable of serving a broader range of commercial and government missions.
If management executes on those growth initiatives, analysts believe revenue and margin expansion could justify substantial upside in Rocket Lab shares in the years ahead. The Cantor view is therefore less about what happens on November 9 and more about whether Rocket Lab can convert its pipeline of opportunities into sustained financial performance over the next several years.
What’s the Consensus Rating on Rocket Lab?
Other Wall Street analysts also recommend owning RKLB stock heading into 2027. The consensus rating on Rocket Lab currently sits at “Strong Buy,” with a mean price objective of about $101. That implies potential for a rally of more than 100% from current levels.
Of course, consensus ratings and price targets can change quickly around earnings, especially for a high-beta stock like Rocket Lab that has already fallen sharply from its highs. But the current setup suggests that many analysts see the recent selloff as overdone relative to the company’s long-term opportunity. The options market, meanwhile, is signaling that a near-term bounce is plausible, even if the company’s per-share loss is expected to widen.
For investors, the key question is whether Rocket Lab can show enough progress on its launch cadence, Neutron development, and space systems backlog to justify the Street’s confidence. If it can, the combination of depressed expectations and bullish options positioning could set the stage for a post-earnings recovery.
Heading into the earnings event, Rocket Lab stock sits nearly 70% below its year-to-date high. That steep decline has left investors wondering whether the selloff has created an opportunity or whether more pain is ahead. The derivatives market, according to Barchart data, seems to be leaning toward the idea that the downside is largely priced in at current levels.
What Options Traders Expect From Rocket Lab Stock
Even though the company is expected to report a larger per-share loss than it did a year ago, traders are increasingly favoring calls over puts. The put-to-call ratio on options contracts expiring November 13 currently stands at 0.89x. A reading below 1.00x is typically interpreted as bullish, because it means call options — which benefit from upward moves in the stock — are being traded more heavily than put options, which benefit from downward moves.
Barchart’s data also pegs the upper price target implied by those contracts at $52.33. That would signal potential for a post-earnings rally of more than 14% from current levels. In other words, options traders are not necessarily expecting a massive breakout, but they do see a reasonable chance that Rocket Lab shares bounce after the report rather than fall further.
That positioning matters because earnings events often force investors to reassess a stock’s valuation and outlook. If the company delivers results that are merely in line with expectations, or if management provides reassuring commentary on its backlog, launch schedule, and space systems business, the stock could benefit from a relief rally. The options market appears to be preparing for that possibility.
Cantor Fitzgerald Remains Bullish on RKLB Shares
Heading into the quarterly print, Cantor Fitzgerald analysts maintain a Buy rating on Rocket Lab shares. The investment firm currently has a $122 price target on the company, which implies potential upside of roughly 152% from current levels. That is a striking target given the stock’s recent weakness, and it reflects a long-term view rather than a short-term trading call.
Cantor’s bullish thesis is rooted in Rocket Lab’s growing position as a diversified space infrastructure company rather than simply a pure launch provider. The firm sees significant long-term value in several parts of the business. First, Rocket Lab’s expanding space systems segment — which includes spacecraft components, satellite manufacturing, and related services — gives the company multiple ways to generate revenue beyond launch services. Second, increasing government and defense opportunities could provide a durable source of demand, particularly as national security space programs continue to expand. Third, the upcoming Neutron rocket program could unlock a much larger addressable market by giving Rocket Lab a medium-lift launch vehicle capable of serving a broader range of commercial and government missions.
If management executes on those growth initiatives, analysts believe revenue and margin expansion could justify substantial upside in Rocket Lab shares in the years ahead. The Cantor view is therefore less about what happens on November 9 and more about whether Rocket Lab can convert its pipeline of opportunities into sustained financial performance over the next several years.
What’s the Consensus Rating on Rocket Lab?
Other Wall Street analysts also recommend owning RKLB stock heading into 2027. The consensus rating on Rocket Lab currently sits at “Strong Buy,” with a mean price objective of about $101. That implies potential for a rally of more than 100% from current levels.
Of course, consensus ratings and price targets can change quickly around earnings, especially for a high-beta stock like Rocket Lab that has already fallen sharply from its highs. But the current setup suggests that many analysts see the recent selloff as overdone relative to the company’s long-term opportunity. The options market, meanwhile, is signaling that a near-term bounce is plausible, even if the company’s per-share loss is expected to widen.
For investors, the key question is whether Rocket Lab can show enough progress on its launch cadence, Neutron development, and space systems backlog to justify the Street’s confidence. If it can, the combination of depressed expectations and bullish options positioning could set the stage for a post-earnings recovery.

إخلاء المسؤولية
لا يُقصد بالمعلومات والمنشورات أن تكون، أو تشكل، أي نصيحة مالية أو استثمارية أو تجارية أو أنواع أخرى من النصائح أو التوصيات المقدمة أو المعتمدة من TradingView. اقرأ المزيد في شروط الاستخدام.
إخلاء المسؤولية
لا يُقصد بالمعلومات والمنشورات أن تكون، أو تشكل، أي نصيحة مالية أو استثمارية أو تجارية أو أنواع أخرى من النصائح أو التوصيات المقدمة أو المعتمدة من TradingView. اقرأ المزيد في شروط الاستخدام.