
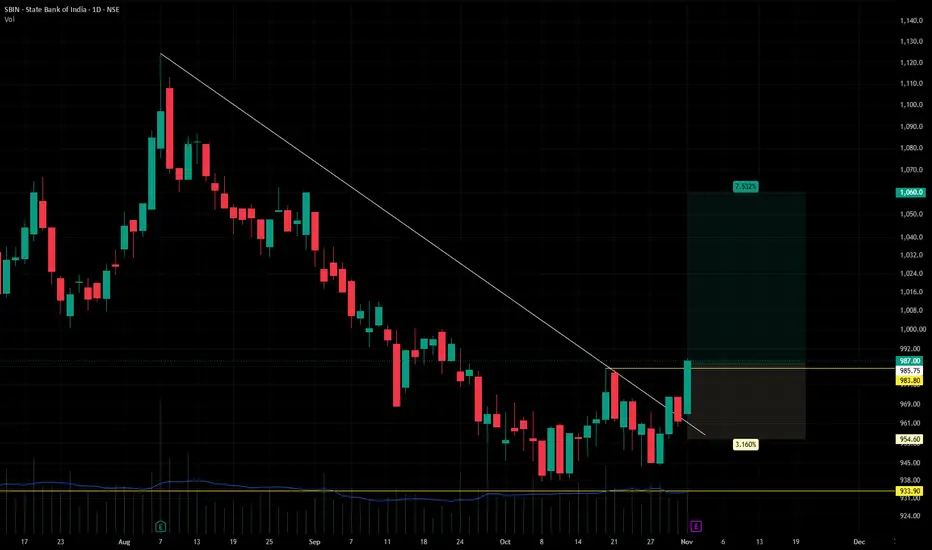
State Bank of India (CMP ₹987.00, NSE: SBIN)
The SmartWay Research Desk | 3 November 2026
A Mumbai‑based public sector bank, incorporated in 1955. State Bank of India (SBI) is India's largest bank, providing retail banking, corporate banking, treasury operations, international banking, digital banking, insurance distribution, and wealth management services. SBI serves millions of customers through its extensive branch network, digital platforms, and international presence across multiple countries.
Promoter Holding (Jun 2026): Government of India — ~56.9% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹5,42,842 Cr vs ₹4,82,212 Cr in FY25 (+12.6% YoY). → Good
Net Profit: FY26 PAT ₹82,212 Cr vs ₹71,842 Cr in FY25 (+14.4% YoY). → Good
Net Interest Margin (NIM): 3.4% vs 3.3% last year. → Good
Equity Capital: Stable, face value ₹1. → Good
Dividend Policy: Consistent dividend payout backed by strong earnings growth. → Good
Asset Quality: Gross NPA ~2.1%; Net NPA ~0.5%. → Excellent
Loan Growth: Strong growth across retail, SME, agriculture, and corporate lending segments. → Good
Provision Coverage: Healthy provisioning and improved recoveries. → Good
EPS: FY26 EPS ₹92.25 vs ₹80.60 last year (+14.5%). → Good
Institutional Interest & Ownership Trends (Jun 2026)
Promoter Holding: ~56.9% (Government of India)
FII Holding: ~10.4%
DII Holding: ~24.8%
Retail & Others: ~7.9%
Strategic Moves & Innovations
Expansion of digital banking ecosystem through YONO and AI‑driven customer services.
Continued focus on retail loans, MSME financing, and rural banking growth.
Strengthening fee income through insurance, mutual funds, and wealth management businesses.
Leveraging subsidiaries including SBI Life Insurance, SBI Cards, and SBI Mutual Fund.
Cash Flow & Balance Sheet Strength
Market cap ~₹8.8 lakh Cr.
Capital Adequacy Ratio comfortably above regulatory requirements.
Strong CASA franchise supporting low-cost deposits.
Book Value per Share ~₹520.00.
P/B ~1.9.
EPS (TTM) ~₹92.25.
P/E ~10.7.
Risk Factors
Dependence on interest rate cycles and economic growth.
Exposure to corporate credit and public sector lending risks.
Regulatory changes affecting banking operations.
Competition from HDFC Bank, ICICI Bank, Axis Bank, and digital fintech platforms.
Investor Takeaway
State Bank of India remains India's strongest public sector banking franchise with significant leadership across retail, corporate, and digital banking. The bank has substantially improved asset quality, profitability, capital strength, and operating efficiency over the past few years. With strong government backing (Government of India holding ~56.9%), dominant market share, improving return ratios, and a growing digital ecosystem, SBI remains a high-quality large-cap banking play. At CMP ₹987.00, valuations appear attractive (P/E ~10.7, P/B ~1.9) relative to earnings growth, balance sheet strength, and long-term banking sector opportunities.
The SmartWay Research Desk | 3 November 2026
A Mumbai‑based public sector bank, incorporated in 1955. State Bank of India (SBI) is India's largest bank, providing retail banking, corporate banking, treasury operations, international banking, digital banking, insurance distribution, and wealth management services. SBI serves millions of customers through its extensive branch network, digital platforms, and international presence across multiple countries.
Promoter Holding (Jun 2026): Government of India — ~56.9% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹5,42,842 Cr vs ₹4,82,212 Cr in FY25 (+12.6% YoY). → Good
Net Profit: FY26 PAT ₹82,212 Cr vs ₹71,842 Cr in FY25 (+14.4% YoY). → Good
Net Interest Margin (NIM): 3.4% vs 3.3% last year. → Good
Equity Capital: Stable, face value ₹1. → Good
Dividend Policy: Consistent dividend payout backed by strong earnings growth. → Good
Asset Quality: Gross NPA ~2.1%; Net NPA ~0.5%. → Excellent
Loan Growth: Strong growth across retail, SME, agriculture, and corporate lending segments. → Good
Provision Coverage: Healthy provisioning and improved recoveries. → Good
EPS: FY26 EPS ₹92.25 vs ₹80.60 last year (+14.5%). → Good
Institutional Interest & Ownership Trends (Jun 2026)
Promoter Holding: ~56.9% (Government of India)
FII Holding: ~10.4%
DII Holding: ~24.8%
Retail & Others: ~7.9%
Strategic Moves & Innovations
Expansion of digital banking ecosystem through YONO and AI‑driven customer services.
Continued focus on retail loans, MSME financing, and rural banking growth.
Strengthening fee income through insurance, mutual funds, and wealth management businesses.
Leveraging subsidiaries including SBI Life Insurance, SBI Cards, and SBI Mutual Fund.
Cash Flow & Balance Sheet Strength
Market cap ~₹8.8 lakh Cr.
Capital Adequacy Ratio comfortably above regulatory requirements.
Strong CASA franchise supporting low-cost deposits.
Book Value per Share ~₹520.00.
P/B ~1.9.
EPS (TTM) ~₹92.25.
P/E ~10.7.
Risk Factors
Dependence on interest rate cycles and economic growth.
Exposure to corporate credit and public sector lending risks.
Regulatory changes affecting banking operations.
Competition from HDFC Bank, ICICI Bank, Axis Bank, and digital fintech platforms.
Investor Takeaway
State Bank of India remains India's strongest public sector banking franchise with significant leadership across retail, corporate, and digital banking. The bank has substantially improved asset quality, profitability, capital strength, and operating efficiency over the past few years. With strong government backing (Government of India holding ~56.9%), dominant market share, improving return ratios, and a growing digital ecosystem, SBI remains a high-quality large-cap banking play. At CMP ₹987.00, valuations appear attractive (P/E ~10.7, P/B ~1.9) relative to earnings growth, balance sheet strength, and long-term banking sector opportunities.

Sucrit.D.Patil
إخلاء المسؤولية
لا يُقصد بالمعلومات والمنشورات أن تكون، أو تشكل، أي نصيحة مالية أو استثمارية أو تجارية أو أنواع أخرى من النصائح أو التوصيات المقدمة أو المعتمدة من TradingView. اقرأ المزيد في شروط الاستخدام.
Sucrit.D.Patil
إخلاء المسؤولية
لا يُقصد بالمعلومات والمنشورات أن تكون، أو تشكل، أي نصيحة مالية أو استثمارية أو تجارية أو أنواع أخرى من النصائح أو التوصيات المقدمة أو المعتمدة من TradingView. اقرأ المزيد في شروط الاستخدام.