
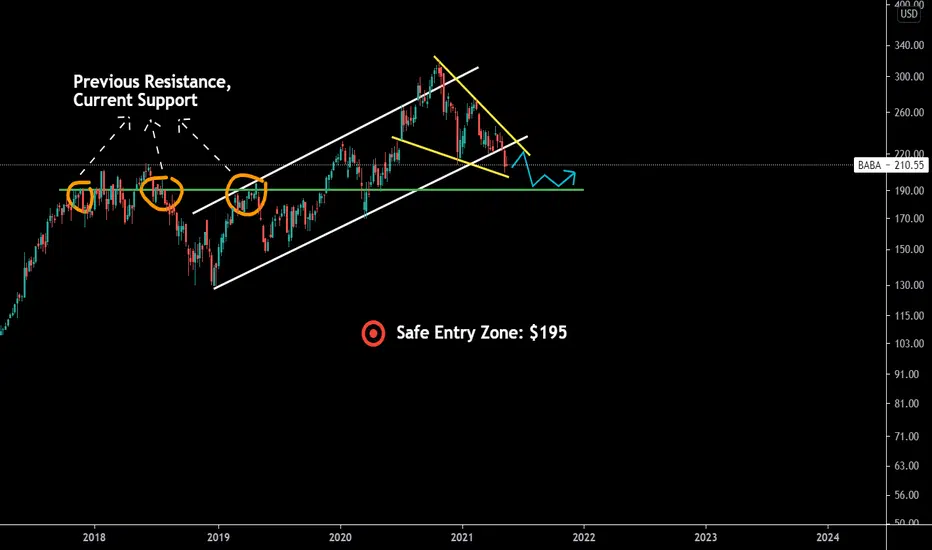
-As of Wednesday, Alibaba is down nearly 33% from its late October peak despite showing robust growth rates.
-The company suffered one of its worst earnings in Q1, with solid performance eclipsed by a hefty Chinese fine.
-From behind a cloud of negative headlines, Alibaba continues to shine as a fast-growing, profitable company with China’s backing.
-The most recent blow was its Q1 earnings report, in which the company reported a roughly $800 million loss, its first-ever as a public company.
-BABA is substantially undervalued and the threats to its success are exaggerated.
Our Opinion:
BABA is oversold but with the given economic volatility and tech sector crash, a safe entry zone can be seen at around $195.

Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.