
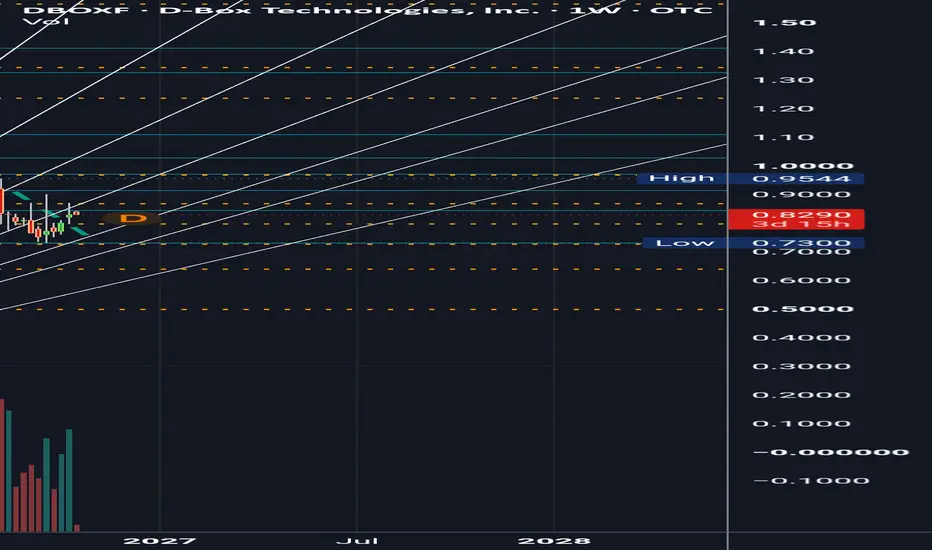
DBOXF is one of those rare early-cycle small-cap opportunities where share-price appreciation is supported by an actual operating transformation vs. speculation about a future product.
The company has moved from selling motion systems toward monetizing a growing installed base through recurring royalties, and fly wheel economics is starting to tell a different story. Revenue is expanding, operating leverage is becoming visible, and the balance sheet is substantially stronger.
The stock has appreciated ~180% over the past year but this should be a validation of the thesis, not a counterfactual. The underlying business is in the early stages of an earnings expansion cycle.
I'm comfortable with a 5 year price target of $80/sh, which puts the market cap at $18B. Current capex is funded entirely by royalty revenue. This is the precise formula for a small cap growing into a mid cap.

Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.