
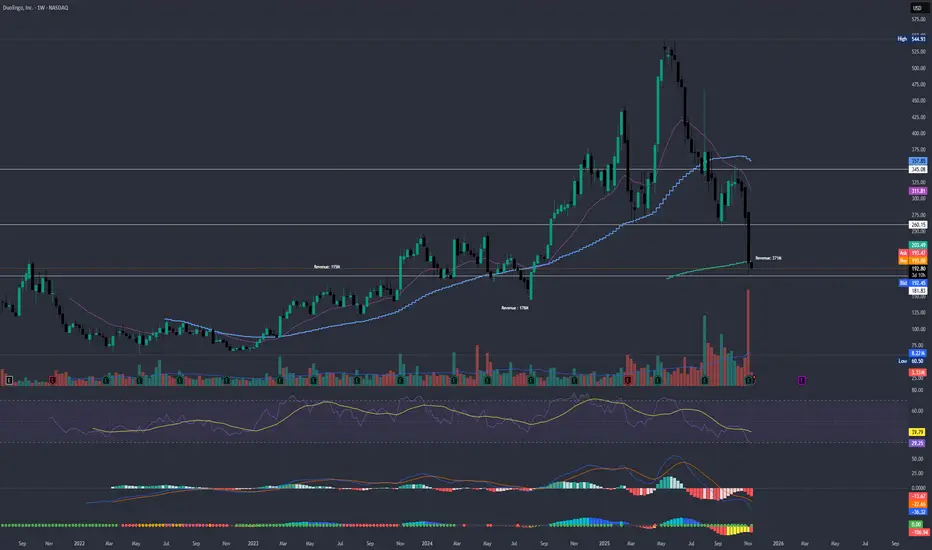
The recent sentiment for Duolingo has been shaky. Leveraging AI to maximize content output has not exactly translated well for Duolingo. AI content is controversial, and tests lost some accuracy. They also wish extend their reach by offering different subjects now that they believe the content is ready to produce. Is it really necessary or could this be similar to what Meta tried to do when they pushed their Metaverse ambitions? Will mistakes need to be made first before finding something that makes sense? Despite the controversy and upset loyal users, growth companies will behave like visionaries until they are slapped back into reality.
According to documents from 2023 to 2025, Duolingo financials show consistent high growth numbers, stable but slightly compressing margins, and rapidly improving profitability.
On revenues, the company reports remarkable momentum driven primarily by subscription growth. ~+40% YoY, $754.7 this year so far.
User Metrics:
MAU = 135.3M, +20% YoY
DAU = 50.5M, +36% YoY
Paid Users = 11.5M, +34% YoY
Margins remain exceptionally high for a software subscription business, showing strong operating leverage, with mild compression due to AI-Driven product investment.
Gross Margins:
2025 YTD: 72%
2024: 73%
2023: 73%
Duolingo has entered a highly profitable scaling phase. The business is transitioning from growth-mode to cash-generative compounding mode. R&D and G&A is growing slower than revenue.
Given rising net income and expanding equity base, ROE is improving materially as operating leverage continues. ROC is surging upwards as the company shifts from R&D heavy to monetization heavy. In other words, low capital requirements and rapidly expanding operating income.
An intrinsic value of $260 - $345 aligns with its hard to replicate network effect, high FCF conversion, and growing margins.

Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.