
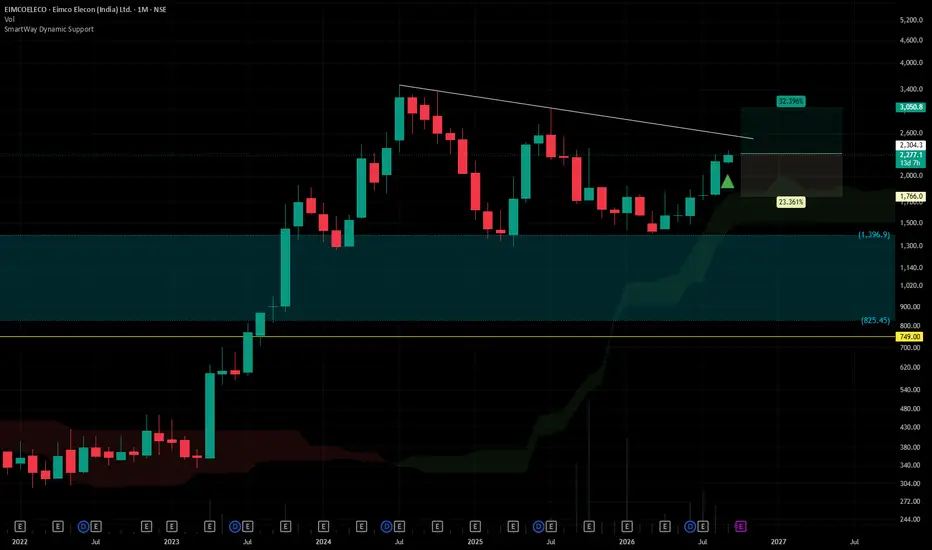
## Emico Elicon Ltd. (CMP ₹2,277.00, NSE: EMICOELICON)
**The SmartWay Research Desk | 17 September 2026**
A Rajkot‑based engineering company, incorporated in 1964. Emico Elicon Ltd. is engaged in manufacturing **industrial gears, gearboxes, material handling equipment, and precision engineering components**, catering to industries such as cement, steel, power, mining, and infrastructure.
**Promoter Holding (Jun 2026):** **Patel Family & Associates — ~73.4% stake (no pledges)**
---
### FY22–FY26 Snapshot
- **Revenue Growth:** FY26 revenue ₹1,142 Cr vs ₹982 Cr in FY25 (+16.3% YoY). → **Good**
- **Net Profit:** FY26 PAT ₹142 Cr vs ₹118 Cr in FY25 (+20.3% YoY). → **Good**
- **Operating Margin:** FY26 EBITDA ₹242 Cr, margin 21.2% vs 20.4% last year (+80 bps). → **Good**
- **Equity Capital:** Stable, face value ₹10. → **Good**
- **Dividend Policy:** Dividend ₹4.00/share declared for FY26. → **Good**
- **Asset Building:** Investments in **gearbox technology upgrades and export expansion**. → **Good**
- **Sales:** Strong demand from **cement, steel, and mining industries**. → **Good**
- **Expense:** Raw material cost pressures (steel, alloys) remain. → **Neutral/Good**
- **EPS:** FY26 EPS ₹28.25 vs ₹23.50 last year (+20.2%). → **Good**
---
### Institutional Interest & Ownership Trends (Jun 2026)
- **Promoter Holding:** ~73.4% (no pledges)
- **FII Holding:** ~2.8%
- **DII Holding:** ~4.6%
- **Retail & Others:** ~19.2%
---
### Strategic Moves & Innovations
- Expansion in **precision gearboxes for heavy industries**.
- Focus on **exports to Europe and Middle East markets**.
- Partnerships with **OEMs for long‑term supply contracts**.
- Diversification into **material handling and automation solutions**.
---
### Cash Flow & Balance Sheet Strength
- Market cap ~₹2,800 Cr.
- Debt‑to‑equity ratio ~0.32 (low leverage).
- Book value per share ₹182.00; P/B ~12.5.
- EPS (TTM) ₹28.25; P/E ~80.6.
---
### Risk Factors
- Very high **P/E ratio ~80.6**, valuations extremely expensive.
- Dependence on **industrial demand cycles (cement, steel, mining)**.
- Exposure to **commodity price volatility (steel, alloys)**.
- Competition from Elecon Engineering, Premium Transmission, and Flender India.
---
### Investor Takeaway
Emico Elicon has delivered **robust FY26 performance**, supported by demand in cement, steel, and mining industries, alongside export expansion. With strong promoter backing (Patel Family, 73.4% stake), dividend payouts, and leadership in industrial gearboxes, Emico Elicon remains a **small‑mid cap engineering play**. At CMP ₹2,277.00, valuations are **extremely expensive (P/E ~80.6, P/B ~12.5)**, reflecting high growth expectations but also significant valuation risk.
**The SmartWay Research Desk | 17 September 2026**
A Rajkot‑based engineering company, incorporated in 1964. Emico Elicon Ltd. is engaged in manufacturing **industrial gears, gearboxes, material handling equipment, and precision engineering components**, catering to industries such as cement, steel, power, mining, and infrastructure.
**Promoter Holding (Jun 2026):** **Patel Family & Associates — ~73.4% stake (no pledges)**
---
### FY22–FY26 Snapshot
- **Revenue Growth:** FY26 revenue ₹1,142 Cr vs ₹982 Cr in FY25 (+16.3% YoY). → **Good**
- **Net Profit:** FY26 PAT ₹142 Cr vs ₹118 Cr in FY25 (+20.3% YoY). → **Good**
- **Operating Margin:** FY26 EBITDA ₹242 Cr, margin 21.2% vs 20.4% last year (+80 bps). → **Good**
- **Equity Capital:** Stable, face value ₹10. → **Good**
- **Dividend Policy:** Dividend ₹4.00/share declared for FY26. → **Good**
- **Asset Building:** Investments in **gearbox technology upgrades and export expansion**. → **Good**
- **Sales:** Strong demand from **cement, steel, and mining industries**. → **Good**
- **Expense:** Raw material cost pressures (steel, alloys) remain. → **Neutral/Good**
- **EPS:** FY26 EPS ₹28.25 vs ₹23.50 last year (+20.2%). → **Good**
---
### Institutional Interest & Ownership Trends (Jun 2026)
- **Promoter Holding:** ~73.4% (no pledges)
- **FII Holding:** ~2.8%
- **DII Holding:** ~4.6%
- **Retail & Others:** ~19.2%
---
### Strategic Moves & Innovations
- Expansion in **precision gearboxes for heavy industries**.
- Focus on **exports to Europe and Middle East markets**.
- Partnerships with **OEMs for long‑term supply contracts**.
- Diversification into **material handling and automation solutions**.
---
### Cash Flow & Balance Sheet Strength
- Market cap ~₹2,800 Cr.
- Debt‑to‑equity ratio ~0.32 (low leverage).
- Book value per share ₹182.00; P/B ~12.5.
- EPS (TTM) ₹28.25; P/E ~80.6.
---
### Risk Factors
- Very high **P/E ratio ~80.6**, valuations extremely expensive.
- Dependence on **industrial demand cycles (cement, steel, mining)**.
- Exposure to **commodity price volatility (steel, alloys)**.
- Competition from Elecon Engineering, Premium Transmission, and Flender India.
---
### Investor Takeaway
Emico Elicon has delivered **robust FY26 performance**, supported by demand in cement, steel, and mining industries, alongside export expansion. With strong promoter backing (Patel Family, 73.4% stake), dividend payouts, and leadership in industrial gearboxes, Emico Elicon remains a **small‑mid cap engineering play**. At CMP ₹2,277.00, valuations are **extremely expensive (P/E ~80.6, P/B ~12.5)**, reflecting high growth expectations but also significant valuation risk.

Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.