
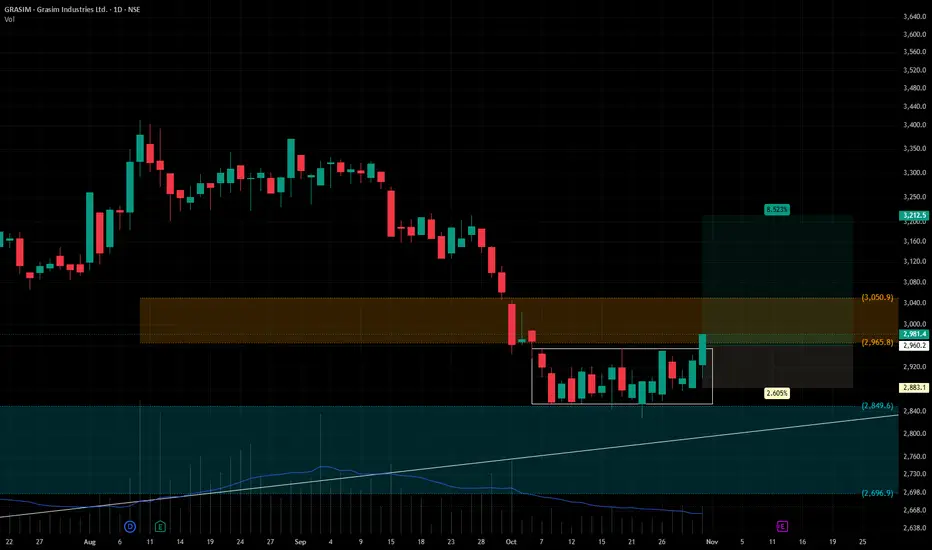
Grasim Industries Ltd. (CMP ₹2,982.00, NSE: GRASIM)
The SmartWay Research Desk | 30 October 2026
A Mumbai‑based diversified manufacturing company, incorporated in 1947. Grasim Industries Ltd., the flagship company of the Aditya Birla Group, operates across cement, chemicals, viscose staple fibre (VSF), paints, financial services, and textiles. Through its holdings in UltraTech Cement and Aditya Birla Capital, Grasim has established itself as one of India's most diversified industrial conglomerates.
Promoter Holding (Jun 2026): Aditya Birla Group (Kumar Mangalam Birla & Promoter Group) — ~42.6% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹1,48,842 Cr vs ₹1,32,112 Cr in FY25 (+12.7% YoY). → Good
Net Profit: FY26 PAT ₹13,212 Cr vs ₹11,812 Cr in FY25 (+11.9% YoY). → Good
Operating Margin: FY26 EBITDA ₹26,842 Cr, margin 18.0% vs 17.4% last year (+60 bps). → Good
Equity Capital: Stable, face value ₹2. → Good
Dividend Policy: Consistent dividend distribution supported by diversified cash flows. → Good
Asset Building: Investments in Birla Opus Paints, chemicals expansion, and cement capacity additions. → Good
Sales: Strong demand from cement, building materials, chemicals, and financial services businesses. → Good
Expense: Input costs related to energy, raw materials, and logistics remain key variables. → Neutral
EPS: FY26 EPS ₹188.25 vs ₹168.40 last year (+11.8%). → Good
Institutional Interest & Ownership Trends (Jun 2026)
Promoter Holding: ~42.6% (no pledges)
FII Holding: ~14.8%
DII Holding: ~27.2%
Retail & Others: ~15.4%
Strategic Moves & Innovations
Expansion of Birla Opus Paints to gain market share in the decorative paints segment.
Continued capacity expansion in UltraTech Cement.
Strengthening the specialty chemicals and advanced materials business.
Leveraging synergies across financial services, building materials, and manufacturing verticals.
Cash Flow & Balance Sheet Strength
Market cap ~₹2.0 lakh Cr.
Debt‑to‑equity ratio ~0.62 (manageable for a diversified conglomerate).
Book Value per Share ~₹1,480.00.
P/B ~2.0.
EPS (TTM) ~₹188.25.
P/E ~15.8.
Risk Factors
Dependence on infrastructure, construction, and economic growth cycles.
Exposure to commodity and energy price fluctuations.
High capital expenditure requirements across multiple businesses.
Competition from Asian Paints, JSW Paints, Pidilite, and other diversified industrial players.
Investor Takeaway
Grasim Industries offers investors exposure to multiple high‑growth sectors through its leadership positions in cement, chemicals, paints, and financial services. The company's aggressive expansion in the paints business, coupled with strong contributions from UltraTech Cement and Aditya Birla Capital, provides diversified growth opportunities. With strong promoter backing (Aditya Birla Group holding ~42.6%), healthy cash generation, and a broad industrial portfolio, Grasim remains a high‑quality large‑cap conglomerate. At CMP ₹2,982.00, valuations are reasonable (P/E ~15.8, P/B ~2.0), offering a balanced mix of growth, diversification, and long‑term value creation potential.
The SmartWay Research Desk | 30 October 2026
A Mumbai‑based diversified manufacturing company, incorporated in 1947. Grasim Industries Ltd., the flagship company of the Aditya Birla Group, operates across cement, chemicals, viscose staple fibre (VSF), paints, financial services, and textiles. Through its holdings in UltraTech Cement and Aditya Birla Capital, Grasim has established itself as one of India's most diversified industrial conglomerates.
Promoter Holding (Jun 2026): Aditya Birla Group (Kumar Mangalam Birla & Promoter Group) — ~42.6% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹1,48,842 Cr vs ₹1,32,112 Cr in FY25 (+12.7% YoY). → Good
Net Profit: FY26 PAT ₹13,212 Cr vs ₹11,812 Cr in FY25 (+11.9% YoY). → Good
Operating Margin: FY26 EBITDA ₹26,842 Cr, margin 18.0% vs 17.4% last year (+60 bps). → Good
Equity Capital: Stable, face value ₹2. → Good
Dividend Policy: Consistent dividend distribution supported by diversified cash flows. → Good
Asset Building: Investments in Birla Opus Paints, chemicals expansion, and cement capacity additions. → Good
Sales: Strong demand from cement, building materials, chemicals, and financial services businesses. → Good
Expense: Input costs related to energy, raw materials, and logistics remain key variables. → Neutral
EPS: FY26 EPS ₹188.25 vs ₹168.40 last year (+11.8%). → Good
Institutional Interest & Ownership Trends (Jun 2026)
Promoter Holding: ~42.6% (no pledges)
FII Holding: ~14.8%
DII Holding: ~27.2%
Retail & Others: ~15.4%
Strategic Moves & Innovations
Expansion of Birla Opus Paints to gain market share in the decorative paints segment.
Continued capacity expansion in UltraTech Cement.
Strengthening the specialty chemicals and advanced materials business.
Leveraging synergies across financial services, building materials, and manufacturing verticals.
Cash Flow & Balance Sheet Strength
Market cap ~₹2.0 lakh Cr.
Debt‑to‑equity ratio ~0.62 (manageable for a diversified conglomerate).
Book Value per Share ~₹1,480.00.
P/B ~2.0.
EPS (TTM) ~₹188.25.
P/E ~15.8.
Risk Factors
Dependence on infrastructure, construction, and economic growth cycles.
Exposure to commodity and energy price fluctuations.
High capital expenditure requirements across multiple businesses.
Competition from Asian Paints, JSW Paints, Pidilite, and other diversified industrial players.
Investor Takeaway
Grasim Industries offers investors exposure to multiple high‑growth sectors through its leadership positions in cement, chemicals, paints, and financial services. The company's aggressive expansion in the paints business, coupled with strong contributions from UltraTech Cement and Aditya Birla Capital, provides diversified growth opportunities. With strong promoter backing (Aditya Birla Group holding ~42.6%), healthy cash generation, and a broad industrial portfolio, Grasim remains a high‑quality large‑cap conglomerate. At CMP ₹2,982.00, valuations are reasonable (P/E ~15.8, P/B ~2.0), offering a balanced mix of growth, diversification, and long‑term value creation potential.

Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.