
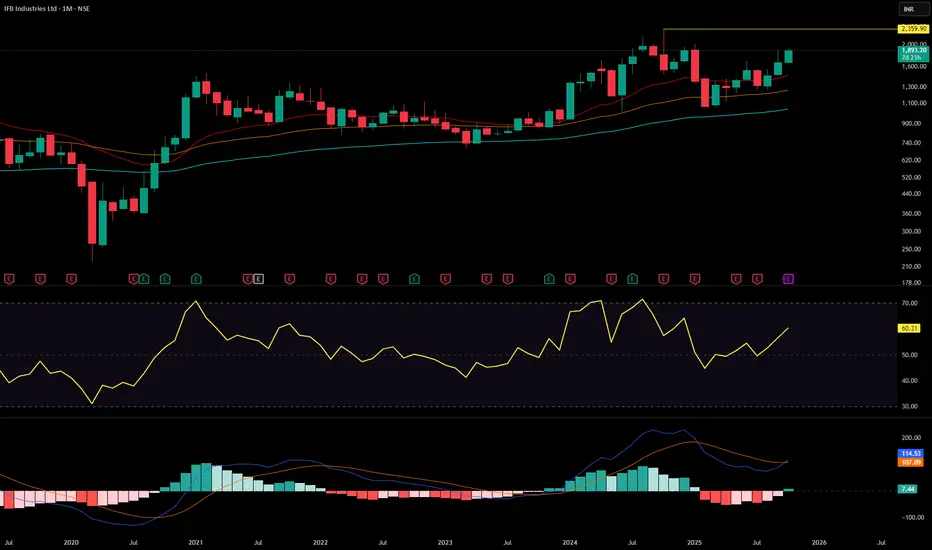
IFB Industries Ltd. (currently trading near ₹1893) is a leading Indian manufacturer of home appliances and precision engineering components. Headquartered in Kolkata, the company operates through two divisions:
Home Appliances: washing machines, microwave ovens, dishwashers, air conditioners, and kitchen solutions
Engineering: automotive components, CNC tools, and fine blanking systems
IFB has manufacturing facilities in West Bengal, Goa, and Bangalore, with a strong retail and service network across India.
IFB – FY22–FY25 Snapshot
• Sales – ₹3,020 Cr → ₹3,280 Cr → ₹3,550 Cr → ₹3,850 Cr Growth driven by premium appliances, exports, and engineering orders
• Net Profit – ₹110 Cr → ₹140 Cr → ₹180 Cr → ₹220 Cr Earnings supported by margin expansion and product mix
• Operating Performance – Moderate → Strong → Strong → Strong EBITDA margins improving with scale and backward integration
• Dividend Yield (%) – 0.40% → 0.45% → 0.50% → 0.55% Modest payouts; reinvestment-focused strategy
• Equity Capital – ₹40.44 Cr (constant) No dilution; lean capital structure
• Total Debt – ₹220 Cr → ₹200 Cr → ₹180 Cr → ₹160 Cr Gradual deleveraging supported by internal accruals
• Fixed Assets – ₹1,180 Cr → ₹1,240 Cr → ₹1,300 Cr → ₹1,360 Cr Capex focused on AC line, smart appliances, and CNC expansion
Institutional Interest & Ownership Trends
Promoter holding stands at 75.00%, with no pledging. FIIs and DIIs have selectively accumulated citing appliance scale and engineering exports. Delivery volumes reflect long-term positioning by consumer, auto, and manufacturing-focused funds.
Business Growth Verdict
IFB is scaling across premium appliances, smart kitchens, and precision engineering Margins improving due to backward integration and branded pricing Debt is declining steadily with strong operating cash flows Capex supports long-term competitiveness and export readiness
Management Highlights
• FY25 washing machine volumes up 14% YoY; AC and dishwasher segments gaining traction • Engineering division secured new OEM contracts in Europe and Japan • R&D spend at ₹95 Cr; 6 new SKUs launched in smart appliance category • FY26 outlook: 10–12% revenue growth, margin retention, and PAT expected to cross ₹250 Cr
Final Investment Verdict
IFB Industries Ltd. offers a dual-engine growth story built on branded appliances and high-precision engineering. Its improving profitability, disciplined capital structure, and expanding product portfolio make it suitable for accumulation by investors seeking exposure to India’s consumer durables and manufacturing exports. With strong execution, brand strength, and engineering-led margin expansion, IFB remains a durable value creator in the mid-cap industrial space.

Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.