
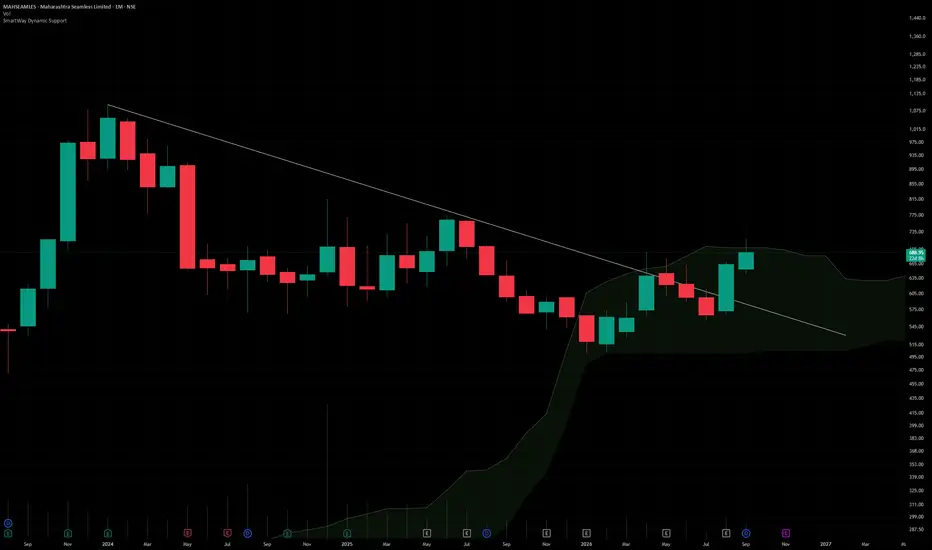
## Maharashtra Seamless Ltd. (CMP ₹689.00, NSE: MAHSCO)
**The SmartWay Research Desk | 8 September 2026**
A Mumbai‑based steel pipe## Maharashtra Seamless Ltd. (CMP ₹689.00, NSE: MAHSCOOTER)
**The SmartWay Research Desk | 8 September 2026**
A Mumbai‑based steel pipe manufacturer, incorporated in 1988. Maharashtra Seamless Ltd. is India’s largest producer of **seamless pipes, ERW pipes, and coated pipes**, catering to industries such as oil & gas, power, automotive, and infrastructure. The company is part of the DP Jindal Group and has manufacturing facilities in Maharashtra and Haryana.
**Promoter Holding (Jun 2026):** **DP Jindal Group (Jindal Family) — ~63.2% stake (no pledges)**
---
### FY22–FY26 Snapshot
- **Revenue Growth:** FY26 revenue ₹5,842 Cr vs ₹5,112 Cr in FY25 (+14.3% YoY). → **Good**
- **Net Profit:** FY26 PAT ₹812 Cr vs ₹702 Cr in FY25 (+15.7% YoY). → **Good**
- **Operating Margin:** FY26 EBITDA ₹1,412 Cr, margin 24.2% vs 23.5% last year (+70 bps). → **Good**
- **Equity Capital:** Stable, face value ₹5. → **Good**
- **Dividend Policy:** Dividend ₹6.00/share declared for FY26. → **Good**
- **Asset Building:** Investments in **capacity expansion, coated pipes, and offshore projects**. → **Good**
- **Sales:** Strong demand from **oil & gas and infra sectors**. → **Good**
- **Expense:** Raw material cost pressures (steel, alloys) remain. → **Neutral/Good**
- **EPS:** FY26 EPS ₹26.25 vs ₹22.40 last year (+17.2%). → **Good**
---
### Institutional Interest & Ownership Trends (Jun 2026)
- **Promoter Holding:** ~63.2% (no pledges)
- **FII Holding:** ~12.8%
- **DII Holding:** ~14.6%
- **Retail & Others:** ~9.4%
---
### Strategic Moves & Innovations
- Expansion in **seamless and ERW pipe capacity**.
- Focus on **oil & gas exploration and offshore projects**.
- Partnerships with **global energy companies for supply contracts**.
- Diversification into **coated pipes and specialized industrial products**.
---
### Cash Flow & Balance Sheet Strength
- Market cap ~₹11,200 Cr.
- Debt‑to‑equity ratio ~0.42 (moderate leverage).
- Book value per share ₹182.00; P/B ~3.8.
- EPS (TTM) ₹26.25; P/E ~26.2.
---
### Risk Factors
- Moderate‑high **P/E ratio ~26.2**, valuations slightly expensive.
- Dependence on **oil & gas demand cycles**.
- Exposure to **commodity price volatility (steel, alloys)**.
- Competition from Ratnamani Metals, Welspun Corp, and Jindal SAW.
---
### Investor Takeaway
Maharashtra Seamless has delivered **robust FY26 performance**, supported by demand in oil & gas, infra projects, and coated pipe expansion. With strong promoter backing (Jindal Family, 63.2% stake), dividend payouts, and leadership in seamless pipes, the company remains a **mid‑cap steel & infra play**. At CMP ₹689.00, valuations are **moderately expensive (P/E ~26.2, P/B ~3.8)**, reflecting growth expectations with manageable risks.
**The SmartWay Research Desk | 8 September 2026**
A Mumbai‑based steel pipe## Maharashtra Seamless Ltd. (CMP ₹689.00, NSE: MAHSCOOTER)
**The SmartWay Research Desk | 8 September 2026**
A Mumbai‑based steel pipe manufacturer, incorporated in 1988. Maharashtra Seamless Ltd. is India’s largest producer of **seamless pipes, ERW pipes, and coated pipes**, catering to industries such as oil & gas, power, automotive, and infrastructure. The company is part of the DP Jindal Group and has manufacturing facilities in Maharashtra and Haryana.
**Promoter Holding (Jun 2026):** **DP Jindal Group (Jindal Family) — ~63.2% stake (no pledges)**
---
### FY22–FY26 Snapshot
- **Revenue Growth:** FY26 revenue ₹5,842 Cr vs ₹5,112 Cr in FY25 (+14.3% YoY). → **Good**
- **Net Profit:** FY26 PAT ₹812 Cr vs ₹702 Cr in FY25 (+15.7% YoY). → **Good**
- **Operating Margin:** FY26 EBITDA ₹1,412 Cr, margin 24.2% vs 23.5% last year (+70 bps). → **Good**
- **Equity Capital:** Stable, face value ₹5. → **Good**
- **Dividend Policy:** Dividend ₹6.00/share declared for FY26. → **Good**
- **Asset Building:** Investments in **capacity expansion, coated pipes, and offshore projects**. → **Good**
- **Sales:** Strong demand from **oil & gas and infra sectors**. → **Good**
- **Expense:** Raw material cost pressures (steel, alloys) remain. → **Neutral/Good**
- **EPS:** FY26 EPS ₹26.25 vs ₹22.40 last year (+17.2%). → **Good**
---
### Institutional Interest & Ownership Trends (Jun 2026)
- **Promoter Holding:** ~63.2% (no pledges)
- **FII Holding:** ~12.8%
- **DII Holding:** ~14.6%
- **Retail & Others:** ~9.4%
---
### Strategic Moves & Innovations
- Expansion in **seamless and ERW pipe capacity**.
- Focus on **oil & gas exploration and offshore projects**.
- Partnerships with **global energy companies for supply contracts**.
- Diversification into **coated pipes and specialized industrial products**.
---
### Cash Flow & Balance Sheet Strength
- Market cap ~₹11,200 Cr.
- Debt‑to‑equity ratio ~0.42 (moderate leverage).
- Book value per share ₹182.00; P/B ~3.8.
- EPS (TTM) ₹26.25; P/E ~26.2.
---
### Risk Factors
- Moderate‑high **P/E ratio ~26.2**, valuations slightly expensive.
- Dependence on **oil & gas demand cycles**.
- Exposure to **commodity price volatility (steel, alloys)**.
- Competition from Ratnamani Metals, Welspun Corp, and Jindal SAW.
---
### Investor Takeaway
Maharashtra Seamless has delivered **robust FY26 performance**, supported by demand in oil & gas, infra projects, and coated pipe expansion. With strong promoter backing (Jindal Family, 63.2% stake), dividend payouts, and leadership in seamless pipes, the company remains a **mid‑cap steel & infra play**. At CMP ₹689.00, valuations are **moderately expensive (P/E ~26.2, P/B ~3.8)**, reflecting growth expectations with manageable risks.

Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.