
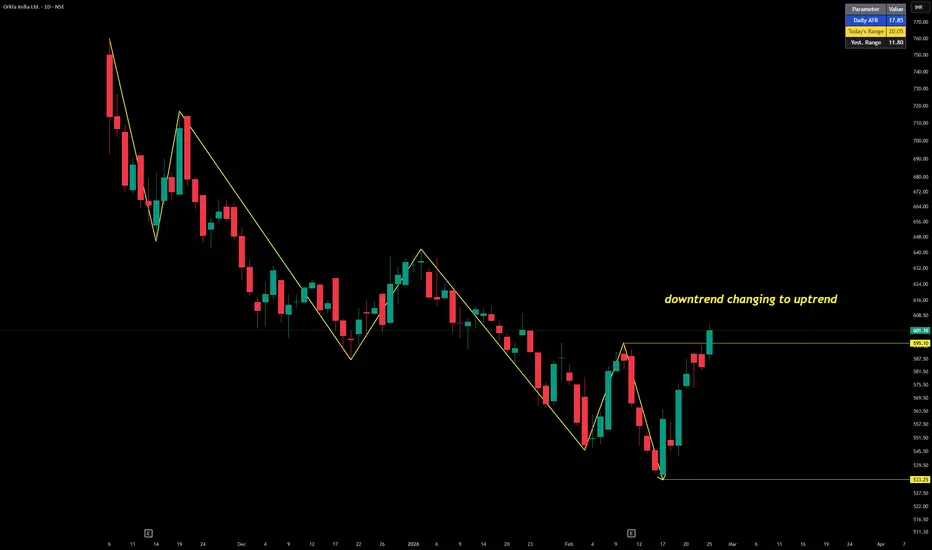
Orkla India Ltd. (NSE: ORKLAINDIA) is part of Orkla ASA (Norway), a global FMCG and branded consumer goods company. In India, Orkla operates through MTR Foods and Eastern Condiments, focusing on packaged foods, spices, ready‑to‑eat meals, and condiments.
Promoter: Orkla ASA (Norway) – 75.00% holding (Dec 2025)
FY22–FY26 Snapshot
Revenue Growth: CAGR ~13% over FY22–FY26, driven by packaged foods and condiments. → Good
Net Profit: FY26 PAT ~₹420 Cr, reflecting steady FMCG demand. → Good
Operating Margin: Maintained ~12–14% range, showing moderate efficiency. → Neutral
Equity Capital: Stable, no major dilution. → Good
Dividend Policy: Conservative, reinvesting profits into expansion. → Neutral
Asset Building: Expansion of food processing facilities and distribution network. → Good
Sales: FY26 revenue crossed ₹3,200 Cr, supported by MTR and Eastern brands. → Good
Expense: Raw material inflation (spices, food grains) impacted margins. → Neutral
EPS: ~₹18.7 in FY26, reflecting consistent earnings growth. → Good
Institutional Interest & Ownership Trends
Largest Promoter: Orkla ASA (Norway) – 75.00%
Largest FII: Vanguard Emerging Markets Fund – 3.24%
Largest DII: SBI Mutual Fund – 0.27%
Strategic Moves & Innovations
Strengthening MTR Foods and Eastern Condiments portfolio.
Expansion into ready‑to‑eat meals and packaged spices.
Focus on distribution in Tier‑2 and Tier‑3 cities.
Leveraging Orkla’s global expertise in FMCG branding.
Cash Flow & Balance Sheet Strength
Strong operating cash flows supported by FMCG demand.
Debt levels remain minimal.
Consistent profit growth supports scalability.
Risk Factors
Margin sensitivity to raw material inflation.
Competition from ITC, Nestlé, and HUL in packaged foods.
Regulatory risks in food safety and labeling.
Investor Takeaway
Orkla India Ltd. is a stable FMCG player with strong promoter backing and rising institutional interest. With most snapshot parameters rated Good, the company shows consistent EPS growth, robust asset building, and strong sales momentum. Investors should monitor raw material inflation and competition, but overall the outlook remains positive.
Promoter: Orkla ASA (Norway) – 75.00% holding (Dec 2025)
FY22–FY26 Snapshot
Revenue Growth: CAGR ~13% over FY22–FY26, driven by packaged foods and condiments. → Good
Net Profit: FY26 PAT ~₹420 Cr, reflecting steady FMCG demand. → Good
Operating Margin: Maintained ~12–14% range, showing moderate efficiency. → Neutral
Equity Capital: Stable, no major dilution. → Good
Dividend Policy: Conservative, reinvesting profits into expansion. → Neutral
Asset Building: Expansion of food processing facilities and distribution network. → Good
Sales: FY26 revenue crossed ₹3,200 Cr, supported by MTR and Eastern brands. → Good
Expense: Raw material inflation (spices, food grains) impacted margins. → Neutral
EPS: ~₹18.7 in FY26, reflecting consistent earnings growth. → Good
Institutional Interest & Ownership Trends
Largest Promoter: Orkla ASA (Norway) – 75.00%
Largest FII: Vanguard Emerging Markets Fund – 3.24%
Largest DII: SBI Mutual Fund – 0.27%
Strategic Moves & Innovations
Strengthening MTR Foods and Eastern Condiments portfolio.
Expansion into ready‑to‑eat meals and packaged spices.
Focus on distribution in Tier‑2 and Tier‑3 cities.
Leveraging Orkla’s global expertise in FMCG branding.
Cash Flow & Balance Sheet Strength
Strong operating cash flows supported by FMCG demand.
Debt levels remain minimal.
Consistent profit growth supports scalability.
Risk Factors
Margin sensitivity to raw material inflation.
Competition from ITC, Nestlé, and HUL in packaged foods.
Regulatory risks in food safety and labeling.
Investor Takeaway
Orkla India Ltd. is a stable FMCG player with strong promoter backing and rising institutional interest. With most snapshot parameters rated Good, the company shows consistent EPS growth, robust asset building, and strong sales momentum. Investors should monitor raw material inflation and competition, but overall the outlook remains positive.

Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.