
PayPal is a rare combination of value and growth.
The company demonstrates strong fundamentals, is strategically focused on the future, and trades at record-low multiples. The combination of financial discipline, capital return, and AI innovation makes it an attractive asset for long-term investors.
The most recent quarter confirmed the resilience of PayPal's business model.
Revenue: $8.42 billion (+7% y-o-y).
Adjusted earnings per share: $1.34, exceeding analyst expectations by $0.14.
Total payment volume (TPV): $458 billion (+8% y-o-y), demonstrating the platform's scale and activity.
Free cash flow (FCF): $2.3 billion for the quarter, and the FCF margin increased 7 percentage points to 27%. This demonstrates high efficiency and the ability to generate cash.
Key Growth Drivers
Paypal isn't dependent on a single product, but is developing several promising areas.
Venmo: The main growth driver. Revenue accelerated to +14% year-on-year. The service is not only growing, but also becoming more profitable.
Buy Now, Pay Later (BNPL): Growing by more than 20% annually, in line with changing consumer behavior.
Upward Guidance: Management raised its adjusted EPS guidance for 2025 to $5.35-$5.39, implying growth of 15-16% year-on-year.
Partnership with OpenAI
This isn't just marketing, but a strategic bet on the future of commerce.
Bottom Line: PayPal is becoming the default payment infrastructure within ChatGPT. Users can instantly transition from searching for a product through an AI-powered conversation to paying with PayPal without leaving the chat.
Meaning:
For PayPal: A new, massive sales channel—"AI commerce" (agentic commerce)—is opening. The company is becoming a "commerce bus" between millions of its merchants and AI users.
For merchants: They automatically gain access to the ChatGPT storefront without the need for complex integration.
For OpenAI: ChatGPT is evolving from an assistant into a full-fledged commerce platform.
The company declared its first-ever dividend of $0.14 per share.
There is also a $6 billion annual buyback program. Shares have declined by 6.25% over the past year.
The "Dividend + Buyback" combination is a powerful signal that the company believes its shares are undervalued.
Historically low valuation
This is a key element of the investment thesis. The market completely ignores positive developments.
Multiples: PayPal trades at only ~12x expected 2026 earnings. This is lower than many less profitable fintech competitors (SoFi, Block).
The investor is paying a price that assumes a complete lack of future growth, while the company is showing double-digit profit growth, generating record cash flow, and building the business of the future.
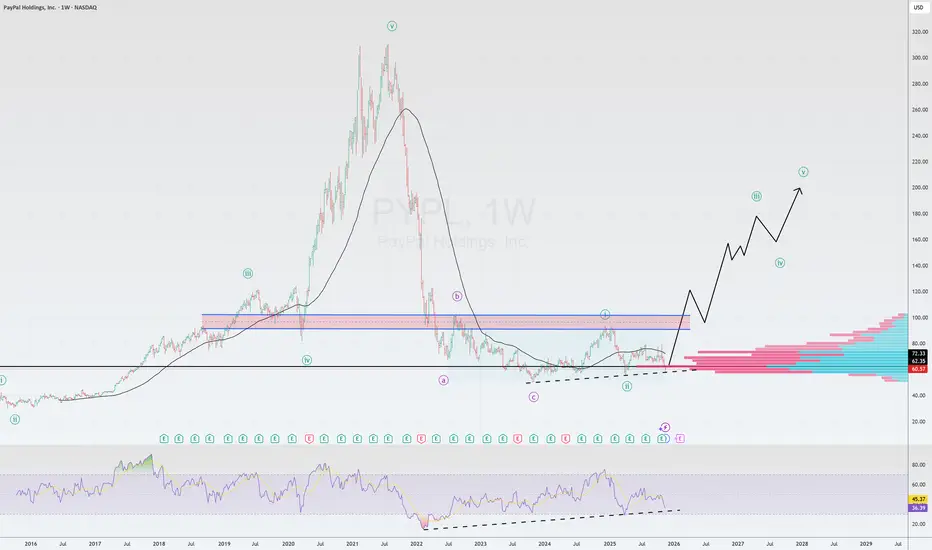
From a technical analysis perspective, we are in the accumulation zone.
The price is near an uptrend line.
The RSI also signals divergence🌎

Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.