
Root, Inc. (NASDAQ:ROOT): A Detailed Look at Q3 Performance, Market Reaction, and Long-Term Positioning
Root, Inc. (NASDAQ:ROOT), a technology-driven auto insurer that utilizes mobile apps and data science to price policies based on individual driving behavior, delivered what can be considered one of the strongest third-quarter performances within the property & casualty insurance segment. The company reported revenues of $387.8 million, marking a substantial 26.9% year-over-year increase and surpassing analysts' expectations by a notable 4.5%. The quarter was characterized by impressive execution, with beats on both earnings per share (EPS) estimates and a solid outperformance on net premiums earned estimates.
A Paradoxical Market Reaction
Despite this robust operational showing, the market's response was decidedly negative. Following the earnings release, the stock declined by approximately 8.5%, trading around $81.94. This disconnect between strong fundamentals and weak price action highlights the complex sentiment surrounding disruptive, growth-oriented insurance tech companies. The bearish reaction may reflect broader sector concerns, valuation pressures, or market impatience with the timeline to sustained, high-margin profitability.
This skepticism was echoed by financial commentator Jim Cramer. When asked about Root, Cramer advised looking elsewhere, cautioning that the stock is "expensive" based on doubts about the durability of its earnings, and pointed to competitor Lemonade (NASDAQ:LMND) as a point of comparison. Cramer's remarks underscore the high expectations and intense scrutiny facing companies in this innovative but competitive space.
The Core Investment Thesis: Data as a Moat
Root's fundamental proposition remains compelling. The company is transforming the traditional insurance model through its data-driven, mobile-first approach. By leveraging telematics to analyze actual driving behavior—processing over 32 billion miles of driving data—Root aims to more accurately assess risk and reward safe drivers, creating a powerful feedback loop for customer acquisition and retention.
This proprietary technology underpins a high-margin, recurring revenue business model. Key metrics demonstrate significant traction:
Policies in force grew from $220 million in 2022 to $415 million in 2024, reflecting a compound annual growth rate (CAGR) of approximately 37%.
The company has successfully expanded its product suite into renters and homeowners insurance, a strategic move designed to increase customer lifetime value and cross-selling opportunities.
Financial discipline is improving markedly, with the net margin rising from -150% in 2021 to 3% in 2024, and the generation of positive free cash flow of $195 million in 2024.
Strategic Positioning and Financial Health
Root operates in a massive U.S. auto insurance market estimated at $300 billion, benefiting from secular trends toward personalized, digital-first solutions. Its asset-light model and digital platform contribute to lower operational costs and efficient claims processing. Management alignment is strong, with insiders owning 11.6% of shares and compensation tied to performance metrics.
Analytically, Root scores 16.5 out of 22 on the "Compounder Score," qualifying it as a high-conviction business with a compelling growth and profitability narrative. The thesis emphasizes Root's development of a durable competitive advantage through scalable AI and machine learning models. While risks around pricing power, regulation, and competition persist, the company projects a revenue CAGR of 14.5% through 2027 and maintains a strong balance sheet.
Technical Perspective and Price Pathways
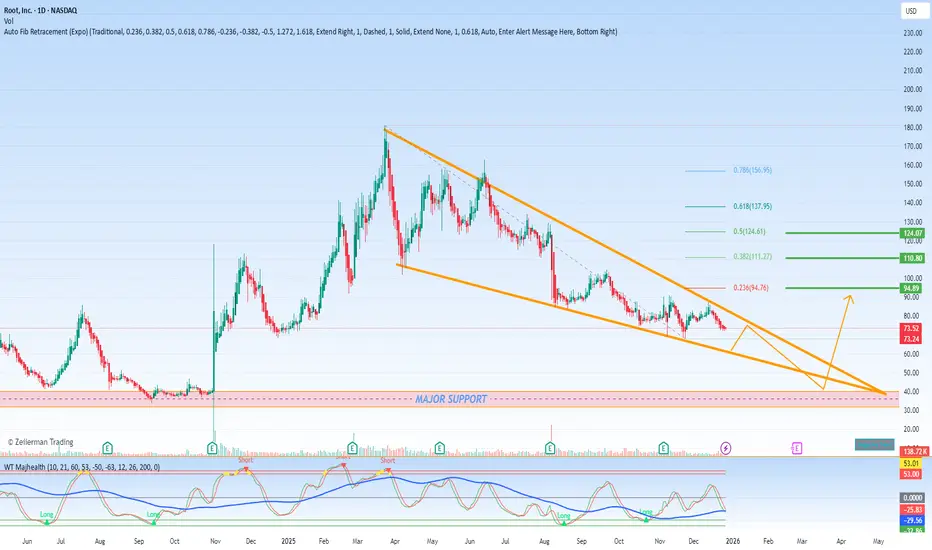
From a chart analysis standpoint, the recent decline places the stock in a cautious technical position. A major support level is identified near $40.00, which would represent a critical zone for the longer-term bullish structure.
For investors and traders anticipating a recovery and continuation of the growth story, Fibonacci extension levels derived from prior price movements suggest several key upside targets:
First Take-Profit Target (0.236 Fibonacci level): $94.76
Second Take-Profit Target (0.382 Fibonacci level): $111.27
Third Take-Profit Target (0.5 Fibonacci level): $124.61
These levels provide a structured framework for assessing potential resistance areas on a rebound.
Conclusion: A Story of Execution Versus Expectation
In summary, Root, Inc. presents a fascinating case of a company executing strongly on its operational and growth metrics—evidenced by an outstanding Q3—while facing a skeptical market preoccupied with valuation and the long path to dominating a traditional industry. The core investment thesis, centered on a transformative data advantage and improving financials, remains intact. However, the stock's journey will likely be volatile, as it must continually prove that its technology-led model can consistently translate into superior underwriting profits and shareholder value in a challenging macroeconomic and competitive landscape. The juxtaposition of its solid fundamentals against its weak recent price action and noted technical supports and resistances defines the current investment dilemma surrounding ROOT.

Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.