
An Australian enterprise software (SaaS) company, similar to Oracle or SAP, but focused heavily on government, councils, and universities.
- It builds ERP-style software (finance, HR, payroll, asset management, student systems, etc.)
- Delivered via the cloud as Software-as-a-Service (SaaS)
- Customers include local governments, universities, and large institutions
- Founded in Australia, listed on the ASX, and now expanding globally (UK, NZ, etc.)
1. Sticky, recurring revenue
Most revenue is subscription-based (SaaS)
Customers sign multi-year contracts
Switching costs are high (changing ERP systems is painful)
This leads to:
- Predictable revenue
- High retention
- Compounding growth
2. Strong track record of growth
Revenue growing ~18% and profit ~16% recently
Long history of profitability (since 1990s)
Management targets doubling size every ~5 years
That consistency is rare on the ASX.
3. High-margin software business
SaaS scales extremely well
Once built, software is cheap to deliver
Result:
- Strong margins
- Increasing profitability as they grow
4. Niche moat (underappreciated “quiet moat” not flashy, but very durable)
They dominate spec.ific verticals:
- Local councils
- Universities
- Government agencies
These markets are:
- Highly regulated
- Hard to penetrate
- Slow-moving (good for incumbents)
5. Low AI disruption risk (relative)
Unlike generic software companies:
- Their systems are deeply embedded workflows
- Hard to replace with AI tools
Recent commentary suggests they’re actually benefiting from AI integration, not being disrupted
6. International expansion upside
- Strong push into the UK (especially councils)
- Early traction but still small
If successful:
Big upside from scaling outside Australia
Negatives:
1. Expensive valuation, PE ~65x
Market already pricing in strong future growth
Less margin for error
2. Slower “sex appeal” vs global tech
Not like AI chips or consumer apps
More like “boring but reliable” software
3. Growth vs expectations risk
Even strong results can disappoint if:
- SaaS growth slows slightly
- ARR misses expectations
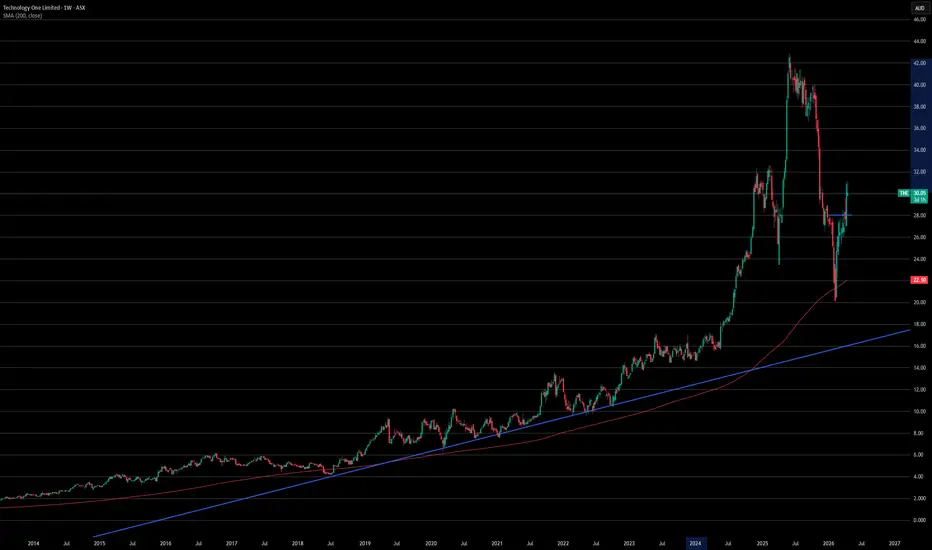
Weekly chart showing a potential for 40% upside return.
- It builds ERP-style software (finance, HR, payroll, asset management, student systems, etc.)
- Delivered via the cloud as Software-as-a-Service (SaaS)
- Customers include local governments, universities, and large institutions
- Founded in Australia, listed on the ASX, and now expanding globally (UK, NZ, etc.)
1. Sticky, recurring revenue
Most revenue is subscription-based (SaaS)
Customers sign multi-year contracts
Switching costs are high (changing ERP systems is painful)
This leads to:
- Predictable revenue
- High retention
- Compounding growth
2. Strong track record of growth
Revenue growing ~18% and profit ~16% recently
Long history of profitability (since 1990s)
Management targets doubling size every ~5 years
That consistency is rare on the ASX.
3. High-margin software business
SaaS scales extremely well
Once built, software is cheap to deliver
Result:
- Strong margins
- Increasing profitability as they grow
4. Niche moat (underappreciated “quiet moat” not flashy, but very durable)
They dominate spec.ific verticals:
- Local councils
- Universities
- Government agencies
These markets are:
- Highly regulated
- Hard to penetrate
- Slow-moving (good for incumbents)
5. Low AI disruption risk (relative)
Unlike generic software companies:
- Their systems are deeply embedded workflows
- Hard to replace with AI tools
Recent commentary suggests they’re actually benefiting from AI integration, not being disrupted
6. International expansion upside
- Strong push into the UK (especially councils)
- Early traction but still small
If successful:
Big upside from scaling outside Australia
Negatives:
1. Expensive valuation, PE ~65x
Market already pricing in strong future growth
Less margin for error
2. Slower “sex appeal” vs global tech
Not like AI chips or consumer apps
More like “boring but reliable” software
3. Growth vs expectations risk
Even strong results can disappoint if:
- SaaS growth slows slightly
- ARR misses expectations
Weekly chart showing a potential for 40% upside return.

Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.