
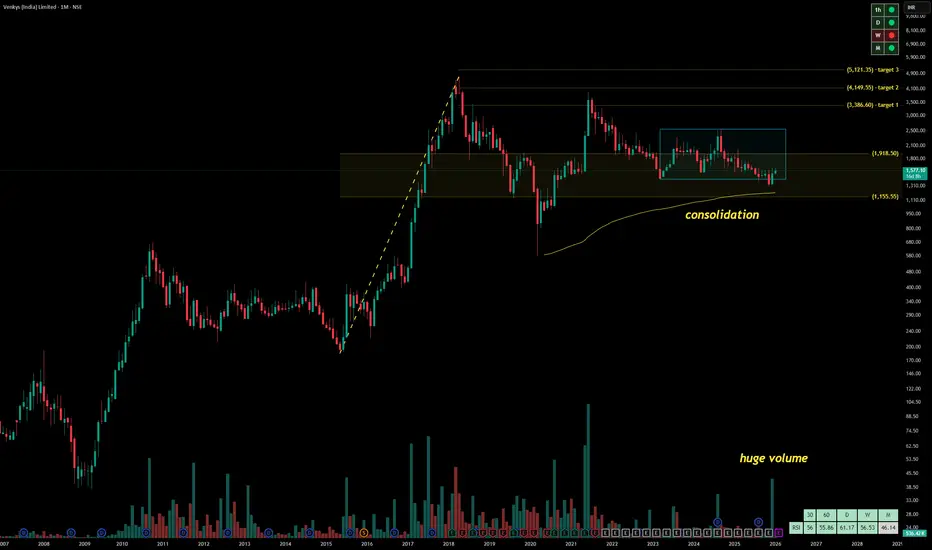
Venky’s (India) Ltd. (CMP ₹1,577.10, -2.14%), headquartered in Pune, is India’s leading poultry and animal health company. Incorporated in 1976, Venky’s operates across poultry breeding, processed chicken, animal feed, and pharmaceutical products. It is also known for producing pathogen-free eggs used in vaccine manufacturing.
Promoter: Venkateshwara Hatcheries Pvt. Ltd. (~51.6% holding). Founded by Dr. B.V. Rao, recognized as the Father of the Indian Poultry Industry, who pioneered modern poultry farming in India.
FY22–FY25 Snapshot
Sales – ₹3,050 Cr → ₹3,420 Cr → ₹3,680 Cr → ₹3,950 Cr
Net Profit – ₹210 Cr → ₹185 Cr → ₹160 Cr → ₹175 Cr
Operating Performance – Strong → Moderate → Weak → Improving
Dividend Yield – 0.8% → 0.9% → 1.0% → 1.1%
Equity Capital – ₹14 Cr (constant)
Total Debt – ₹1,050 Cr → ₹980 Cr → ₹940 Cr → ₹900 Cr
Fixed Assets – ₹2,800 Cr → ₹3,000 Cr → ₹3,200 Cr → ₹3,400 Cr
EPS – ₹150 → ₹132 → ₹114 → ₹125
Institutional Interest & Ownership Trends
Promoter holding is ~51.6% (Venkateshwara Hatcheries Pvt. Ltd.), reflecting strong family-led governance. FIIs and DIIs have modest exposure due to Venky’s niche poultry focus. Public float is ~48%, with delivery volumes showing long-term positioning by consumer and agri-focused funds.
Strategic Moves & Innovations
Venky’s has diversified into processed chicken products, animal health supplements, and poultry feed. The company is investing in biosecurity, vaccine inputs, and pathogen-free egg production, which are critical for pharma and poultry industries. It continues to expand its retail presence through Venky’s branded outlets.
Cash Flow & Balance Sheet Strength
Operating cash flows remain stable, though margins are cyclical due to feed cost volatility. Free cash flow is modest, with reinvestment into poultry infrastructure and pharma products. Debt levels are gradually declining, reflecting disciplined capital allocation.
Risk Factors
Key risks include raw material inflation (maize, soybean), disease outbreaks in poultry, regulatory changes in food safety, and competitive intensity from other poultry and FMCG players.
Investor Takeaway
Venky’s demonstrates steady fundamentals with improving profitability, strong brand equity in poultry, and diversification into animal health and pharma inputs. While cyclical risks remain, it is positioned as a long-term niche player in India’s poultry and food processing sector.

Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.
Sucrit.D.Patil
Aviso legal
As informações e publicações não se destinam a ser, e não constituem, conselhos ou recomendações financeiras, de investimento, comerciais ou de outro tipo fornecidos ou endossados pela TradingView. Leia mais nos Termos de Uso.