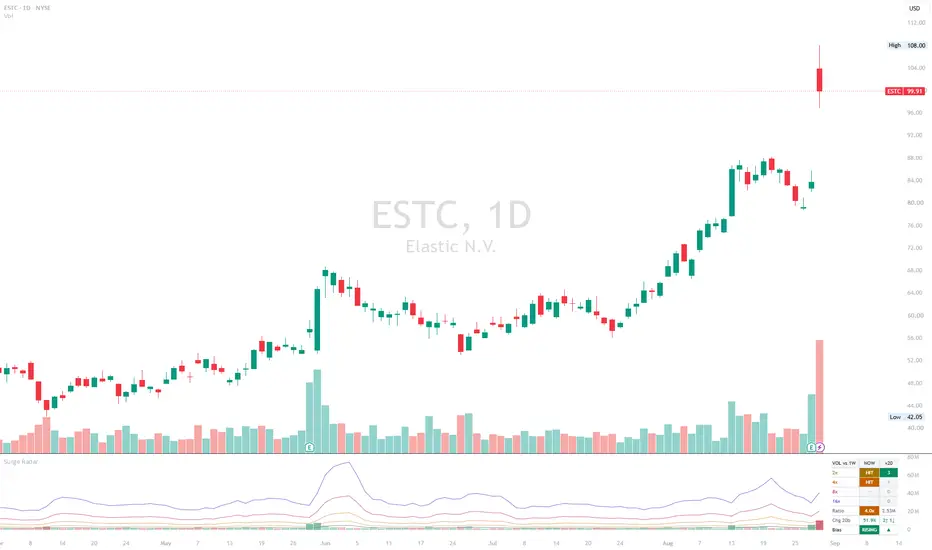
Volume Spike Radar [AxeAlgo]Volume Spike Radar
--
What it does
This indicator flags statistically abnormal volume the moment a bar closes, and instead of just saying volume was big it classifies what kind of event likely happened based on the relationship between that volume and the price range the bar actually produced. It separates four distinct situations. Absorption is heavy volume with a compressed range, often a sign that large resting orders are soaking up buying or selling pressure without letting price travel, and is a classic early reversal tell. Breakout is heavy volume paired with a wide, expanded range, suggesting aggressive orders are actually pushing price through a level rather than just defending it. Climax is extreme volume that caps an already extended run of same direction closes without any fresh range expansion, which is the classic exhaustion or blow off signature seen at the end of a move rather than the start of one. Anything left over is treated as a plain elevated spike with no distinct character.
On top of classification, the indicator flags effort versus result divergence, which happens when an extreme volume bar pushes hard in one direction but still fails to make a new high or low compared to recent price action, suggesting participants on that side got trapped rather than rewarded. A running estimate of cumulative volume delta, built from where each candle closed within its own range, shows whether recent volume has been net accumulating or net distributing over the last several bars. Every volume reading can also be normalized against that specific hour's own historical average, so a session open that is naturally busy every single day stops being repeatedly flagged as unusual just because of the time it happens, and only a bar that is unusual even for its own hour gets the extra marker.
How it works
Volume is measured against its own rolling average using either a straightforward relative volume multiple such as three times the average, or a statistical z score measured in standard deviations, with separate moderate and extreme thresholds for whichever method you choose. Every qualifying bar's total range is compared against its own ATR to decide whether it lands in the absorption, breakout, or climax bucket, and a consecutive same direction run counter is used specifically to detect climax conditions, since a climax by definition needs an extended move behind it rather than an isolated spike. Rapid fire spikes that occur within a small, configurable number of bars of each other are merged into a single growing event badge that shows the bar count and the peak multiple reached during that cluster, instead of stacking a separate tag on every single bar, which keeps fast moving or highly volatile charts readable instead of turning into a wall of overlapping text.
An optional smart candle coloring tints each qualifying bar according to its classification so the character of a move is visible without needing to hover over every tag, and a dashboard summarizes the current volume regime as quiet, normal, elevated, or extreme, the direction of the cumulative delta trend over the last several bars, the time of day adjusted reading, how many spikes have occurred so far in the current session, and the details of the most recent qualifying event.
How to use it
Choose between relative volume and z score depending on whether you prefer an intuitive multiple of average volume or a stricter statistical outlier test that adapts automatically to how noisy a symbol's volume normally is. The badge display mode lets you choose how much detail shows up on the chart itself, from showing every qualifying spike, to only the key institutional style events such as absorption, breakout, climax, and divergence, to only the very largest outliers, to hiding badges completely and relying on candle coloring alone for a cleaner look. Session windows for the major market opens can be highlighted so a spike can be read in the context of whether it happened during a typically active window or outside of it.
The advanced tuning section exposes the exact thresholds behind every classification, including how compressed a range needs to be to count as absorption, how wide it needs to be to count as breakout, and how long a directional run needs to last before a spike there can be called a climax, so the definitions can be tightened or loosened to match how a specific symbol or timeframe normally behaves. This tool describes historical volume behavior that has already happened on a confirmed bar. It is meant to add context to your own analysis of price action, not to function as a standalone buy or sell signal on its own.
Alerts
Alerts are provided for bullish volume spikes, bearish volume spikes, extreme tier outliers regardless of direction, absorption events, breakout volume, climax and exhaustion events, and effort versus result divergence.
Non repainting
Tags, badges, classification, cumulative volume delta, and every alert are evaluated on confirmed bar closes only and never move or change once they have been printed. The background glow and the smart candle coloring are the two live elements on the chart, and both are designed to track the forming bar in real time the same way a standard volume histogram does, settling into their final state the instant the bar actually closes.
Disclaimer
This script is provided for educational and informational purposes only. It visualizes historical volume statistics based on past price and volume data, and it does not predict future price movement in any way. Nothing in this indicator constitutes financial advice or a recommendation to buy or sell any instrument. Always use proper risk management and combine this tool with your own independent analysis before making any trading decision.
Indicador

VP/CD Active Relevance RadiusVolume Profile/Chip Ddistribution/Pressure Rails
The Volume Profile / Chip Distribution (VP/CD) indicator maps volume memory, price acceptance, overhead supply, downside memory, and low-volume transition areas across liquid large caps, volatile stocks, microcaps, gap-driven names, limited-history stocks, and multiple timeframes.
Current baseline: VP/CD v3.0 — M6A.3b. Its role is a market-memory and inventory-map evidence layer, answering key questions about accepted prices, volume memory, overhead supply, downside memory, low-acceptance zones, structural priority, and map reliability without providing automated buy/sell signals.
1. Pressure Rails
Calculates a Pressure Score for qualifying inventory levels and applies Pareto-style filtering to reduce clutter. Rail lengths reflect structural strength (longer rail = stronger surviving pressure structure).
2. Nearest UP and DN Pressure
Identifies nearest surviving pressure structures: UP (above price) and DN (below price). E.g., UP 174.19 | P26 indicates qualifying overhead pressure at 174.19 with a score of 26 (not an automatic resistance line).
3. Pressure Release — REL UP / REL DN
Marks REL UP or REL DN (e.g., REL UP 171.89 | P30) when price closes through a rail. This signifies inventory-pressure release in that direction rather than a guaranteed breakout or auto-entry.
4. Pareto Filtering
Evaluates candidate rails multi-dimensionally and eliminates dominated structures, reducing clutter while preserving key multi-factor historical levels.
5. Map Confidence
Classifies chart quality via environment states (High, Medium, Low, Event, Sparse) and numerical confidence scores. Accounts for structure variations between deep liquid assets versus IPOs, microcaps, gap events, or reverse splits.
6. Microstructure-Aware Calibration
Receives a profile from its companion adapter to categorize environments (Stable/Normal/Volatile Liquid, Limited Liquidity, Thin Stable, Thin Event-Driven, Gap Dominated, Limited History) to tune calculation conservativeness rather than direction.
7. Adaptive PM Evidence
Adjusts reaction counts based on market quality: stable liquid (3 reactions), thin stable (4 reactions), gap/event or limited history (5 reactions). Lower-quality structure requires stricter evidence.
8. Adaptive Event Sensitivity
Scales ATR sensitivity to shock candles based on market stability: stable (4.0 ATR), moderate instability (3.5 ATR), gap/event-driven (3.0 ATR) to avoid map contamination.
9. Adaptive Profile Resolution
Adapts Volume Profile rows to structure: highly liquid/gap-heavy uses finer rows (44 → 50), while thin stocks consolidate nearby inventory into coarser rows (44 → 34) for meaningful grouping.
10. Adaptive Profile Lookback
Modulates historical profile windows (e.g., stable stocks keep 252 days; gap/event-heavy use 189 days). Limited-history stocks retain full available history (252 days) but apply stricter confidence/resolution filters.
11. Adaptive Relevance Radius
Applies three historical relevance radii to prevent stale inventory from dominating: Normal (100%), Elevated Volatility (90%), Extreme/Erratic (80%).
12. Current Battle Map
Provides rapid visual identification of: Current Zone, Support Below, Resistance/Memory Above, AIR Path, Map Confidence, and Guard/Context warnings.
13. AIR / LVN Has a More Precise Meaning
AIR/LVN represents low-acceptance corridors (not direct support/resistance). Combines with Price Memory to form concepts like AIR+PM (thin volume with repeated price reactions).
14. Better Separation of Evidence
Separates distinct evidence categories: VP (traded volume), Chip Distribution (modeled cost basis), VP+Chip (confluence), PM (price memory), STRUCT (pivot memory), DEV (developing memory), and AIR (low-volume transitions).
15. Chip Distribution — Important Clarification
Chip Distribution estimates turnover migration over time. It is a model and does not track actual shareholder positions, tax lots, options exposure, or dark pool data.
16. Better Handling of Thin Stocks
Includes a Sparse Lower-Timeframe Current-Bar Fallback using current chart bar data if lower-timeframe data is missing, ensuring profile continuity without altering historical calculations.
17. Rail Endpoint Prices
Displays exact rail prices directly at the terminal end of each rail regardless of anchor orientation.
18. Cleaner REL Labels
Eliminates duplicate overlapping labels by prioritizing informative REL states over redundant nearest-level text.
19. Diagnostic Audit Improvements
Aligns Diagnostic audit ranking directly with production output: Candidate → Pressure Score filter → Pareto filtering → Surviving rails → Ranking → Displayed rails.
20. Multi-Timeframe Calibration
Scales baselines dynamically across timeframes (1D: 252d/44 rows; 2D: 504d/48 rows; 1W: 1825d/55 rows) to avoid stretched daily profiles.
What has NOT changed
VP/CD remains a structured evidence provider rather than an automatic buy/sell signal, entry trigger, or predictive guarantee.
How I use it
Recommended workflow: check Map Confidence → Current Zone → Support Below → Resistance Above → AIR Path → Pressure Rails → UP/DN → REL, then integrate with overall technical context.
Current Development Status
Baseline baseline VP/CD v3.0 — M6A.3b integrates Volume Profile, Chip Distribution, multi-layered memory, adaptive filters, and microstructure calibration into an analytical mapping framework.
Indicador

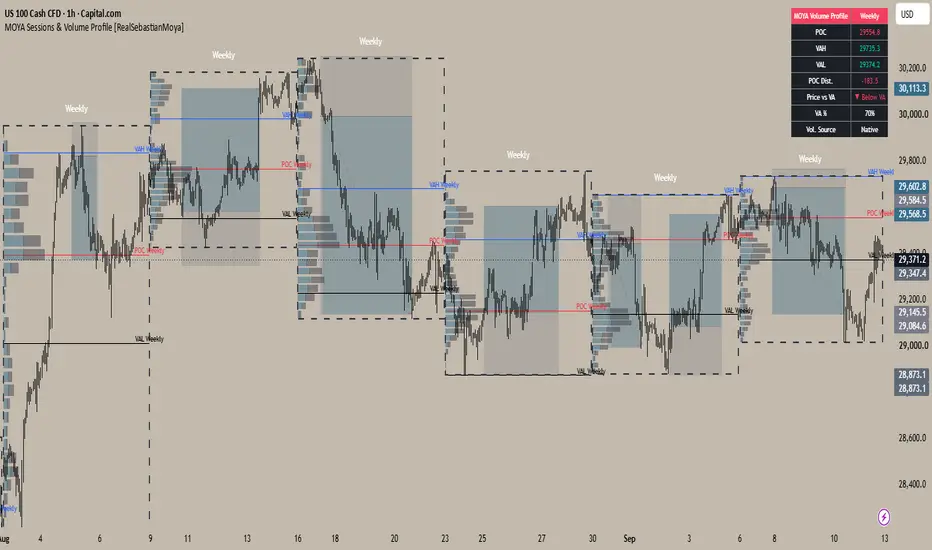
MOYA Sessions & Volume Profile [RealSebastianMoya]Hello traders!
Introducing: "MOYA Sessions and Volume Profile"
This script rebuilds a full Volume Profile for any session length you choose — from a single Tokyo/London/New York session up to a full Yearly cycle — and layers on POC, Value Area High/Low, a live in-progress profile, and (new) real futures volume normalization for Forex/CFD charts.
But before getting into the settings, it's worth explaining where this way of reading the market comes from, because the indicator has no real value if you don't know what questions it's actually answering.
The Underlying Theory: Auction Market Theory
The market isn't a line going up or down. It's a continuous auction. At every moment, buyers and sellers are negotiating a "fair" price, and price moves searching for the level where both sides are willing to transact in volume.
This theory — originally developed for Market Profile by J. Peter Steidlmayer at the CBOT — starts from a simple idea:
Price tells you where the market moved. Volume tells you how much conviction was behind that move.
A regular candlestick chart only shows you the time sequence of price. A Volume Profile rotates that information 90 degrees and asks a different question at every price level: "how much actually traded here?"
The level with the most activity is the Point of Control (POC) — the price the market has "voted" for most often as fair.
The Two Market Regimes
Under this theory, the market constantly alternates between two regimes:
Balance / Equilibrium
Technical name: Balance, Rotational Value Area
What it means: Buyers and sellers accept a range and price rotates inside it without clear direction
Profile shape: Bell curve (D-Shape) — POC centered
Imbalance / Trend
Technical name: Imbalance, Trend Day, Directional Auction
What it means: One side (buyers or sellers) dominates and price refuses to rotate, moving away from the range
Profile shape: Spike (P-Shape or b-Shape) — POC at one extreme
Knowing which regime the market is in completely changes what a touch of the POC or a Value Area edge should mean to you. This is what many newer traders miss: they apply the same rule ("buy at VAL, sell at VAH") regardless of regime, and end up fading strong trends as if they were reversions.
Correct Terminology — What Each Thing Is Actually Called
Here's the real vocabulary used when trading with Volume Profile, so you know exactly which term to use and what each one means:
Levels
POC (Point of Control): the price with the highest traded volume in the session. It's the center of gravity of price.
VAH (Value Area High): the upper boundary of the zone where 70% (adjustable) of volume occurred.
VAL (Value Area Low): the lower boundary of that same zone.
Value Area (VA): the full range between VAH and VAL — the fair price zone accepted by the market.
Naked POC: a POC from a previous session that price has not yet returned to touch. These act as strong magnets because they represent unresolved business.
Price Behaviors
Mean Reversion: when price moves away from the POC but returns to it because the market is in balance. This is the dominant behavior inside an equilibrium regime.
Continuation: when price breaks a Value Area extreme and keeps moving in that direction without returning, because the market is in imbalance.
Rejection: price touches a level (VAH, VAL, or POC) and snaps back quickly, leaving a wick — a sign that level was defended.
Acceptance: price enters a zone and stays there, building new volume — a sign the market considers that new range fair.
Excess: a long, thin wick with no volume behind it — a sign of violent rejection of a price, typical at range extremes.
Breakout: when price exits the Value Area with force and increasing volume. If acceptance follows the breakout, it confirms as a trend start; if there's no acceptance, it's a false breakout (fakeout) and price returns to the range (this is mean reversion after a failed breakout attempt).
Double Distribution (B-Shape): when the profile shows two high-volume zones separated by a low-volume zone — indicates the market was in two distinct price agreements during the session, typical of a trend that paused midway.
On Buyers and Sellers
Classic Volume Profile doesn't directly measure who bought or sold (that's what Delta/CVD does, not part of pure profile reading), but dominance can be inferred by observing:
If the POC shifts upward session after session, buyers are defending higher prices, buyer control.
If the POC shifts downward session after session, seller control.
If the POC stays relatively fixed while volume grows, both sides are actively negotiating without ceding ground, balance, indecisive market.
How the Indicator Works Within This Theory
The script tracks session boundaries using exact timeframe change detection and rebuilds the price/volume grid every time a new session starts.
Each candle's volume is distributed across the price levels its high-low range actually touched (body/wick weighted model), so the profile reflects where price genuinely spent time and volume — not just where it closed.
Once a session closes, the script locates the POC and expands outward, level by level, until the configured percentage of total volume (default 70%) is captured — that boundary becomes your Value Area.
Rather than just showing you where price moved, this helps you answer:
Where did volume concentrate during the session?
Was the session accepted (balance) or rejected (imbalance)?
Where is the fair price zone for this period?
How does that zone line up against higher or lower timeframe context?
While a session is still forming, the script keeps its profile, POC, and Value Area updating in real time (Live Zone) — not just the last closed session — so you can react to developing structure instead of only analyzing it afterward.
Trading Scenarios — How This Is Actually Traded
These are the real scenarios where this reading applies. You add the chart; here's the logic behind each one.
Scenario 1 — Mean Reversion Inside Balance
Regime context: The previous session's profile shows a bell-curve shape (D-Shape), POC centered, and a wide Value Area that has stayed stable across several sessions. This indicates a market in balance.
What you see on the Volume Profile: Current price is drifting away from the POC toward the VAH without growing volume behind it (little real push).
Reading: Since we're in a balance regime, the move toward VAH is likely testing the edge of the range, not the start of a trend.
How it's traded: Look for a short on rejection at the VAH, targeting the POC. Stop above the VAH with a small buffer. This is the classic fade trade — and it only makes sense because the regime is balance; the same signal in a trending regime would be a trap.
Scenario 2 — Continuation After a Breakout With Acceptance
Regime context: Price breaks above the previous session's VAH. Instead of falling back, price stays above that level for several candles, and the new forming profile (Live Zone) starts building its own POC above the old VAH.
What you see on the Volume Profile: Acceptance — the market is actively trading in the new price range, not just passing through it.
Reading: This is evidence of directional imbalance — control shifted hands (likely to buyers) and a new Value Area is forming higher up.
How it's traded: Look for a long entry on the first pullback into the old VAH (which now acts as support — the classic resistance-to-support flip), targeting the next significant volume level from a higher timeframe (e.g., the weekly POC if you're trading on Daily). Stop below the old POC.
Scenario 3 — False Breakout (Fakeout) — Reversion, Not Continuation
Regime context: Price breaks below the VAL with a strong candle, but in the following session (or in the indicator's Live Zone) price returns inside the original Value Area without building new volume below.What you see on the Volume Profile: No acceptance — the new profile forming outside the range has very little volume compared to the prior profile, a sign nobody is defending that price.
Reading: The breakout was a liquidity grab, not a real regime change. The market is still in balance.How it's traded: Look for a long entry on the return inside the Value Area, targeting the POC and potentially the opposite VAH. This is the scenario where confusing "breakout" with "continuation" costs the most money — which is why the indicator's Live Zone is key: it lets you see in real time whether the new profile is gaining volume (real continuation) or staying empty (fakeout).
Scenario 4 — Double Distribution (B-Shape) — A Pause Inside a TrendRegime context: The session's profile shows two separate high-volume zones with a thin low-volume "neck" between them.
What you see on the Volume Profile: The market traded heavily in one range, then migrated and traded heavily again in another range, without spending much time in the middle.Reading: This typically occurs inside a trend that paused — two distinct price agreements in the same session, usually connected by a fast directional move (the low-volume "neck" is where price moved without resistance).
How it's traded: The low-volume neck (the thin part of the profile) is a low-liquidity zone — if price returns there, it tends to cut through quickly in either direction, not stay. It's not a zone to trade reversion; it's a zone to wait for price to cross through and react at the POC of whichever side it's heading toward.
Scenario 5 — Multi-Timeframe Confluence (the Indicator's Most Powerful Use)Regime context: You run the indicator on Weekly and see current price touching the weekly VAL. You switch to Daily and see a daily POC also forming right at that same level.
What you see on the Volume Profile: Two different timeframes coinciding at the same price — the "why" (weekly context) and the "when" (daily execution) are aligned.Reading: This confluence across timeframes is the highest-probability signal in the whole system, because it doesn't depend on a single profile — it depends on the market respecting the same level from two different time perspectives.
How it's traded: Take the entry on Daily (precise execution), with directional bias given by the weekly regime (if weekly price is in balance, trade the reversion toward the weekly POC; if weekly is in imbalance, trade continuation toward the next relevant volume level). Stop goes outside the daily Value Area; target is the weekly POC or the opposite VAH/VAL, depending on the identified regime.
Scenario 6 — Using Real Futures Volume to Confirm Regime on Forex/CFDRegime context: You're trading XAUUSD on your CFD broker. Your broker's tick volume is synthetic (it counts price changes, not real contracts), so a profile built on that volume can show a different shape than actual market activity.
What you see on the Volume Profile: With External Futures Volume enabled and auto-detect pointing to COMEX:GC1! (Gold futures), the profile now reflects real futures market participation, while price levels still come from your XAUUSD chart.
Reading: This matters especially when your broker's tick volume gives you a POC in one place and real futures volume gives you a POC somewhere else — the difference tells you that real institutional market activity sits at a different level than what your broker is showing.
How it's traded: Prioritize the POC/VA calculated with real futures volume over native tick volume when the two diverge, because regulated futures volume (CME/COMEX/NYMEX) is auditable and reflects real participation, while tick count only reflects your specific broker's activity.Summary — Why Use This IndicatorThis script is designed for traders who read the market through:Volume Profile and Point of Control / Value Area (Auction Market Theory)Market regime identification (balance vs. imbalance)Multi-timeframe confluenceReal vs. synthetic volume on Forex/CFD instruments
Because you can run the same profile logic across completely different session lengths — from a single hourly cycle to a full year — you can compare how conviction built across timeframes: does the Daily POC sit inside last week's Value Area? Is price accepted or rejected at last month's VAH? That layered context is where this script earns its keep.Note: every scenario assumes you identify the market regime (balance vs. imbalance) first before deciding whether to trade reversion or continuation — trading the wrong signal for the wrong regime is the most common cause of losses when using Volume Profile.
Features
56 Session Lengths — 1 to 55 Minutes (1m, 2m, 3m, 4m, 5m, 6m, 7m, 8m, 9m, 10m, 12m, 15m, 20m, 25m, 30m, 35m, 40m, 45m, 50m, 55m), Tokyo, London, New York, 1 Hour through 12 Hours, Daily through 7 Days, Weekly through 5 Weeks, Monthly through 7 Months, Quarterly, Yearly.
POC, VAH, VAL with lines and text labels.
HVN/LVN — detects multiple volume peaks and valleys per session, not just the single POC.
External Futures Volume — auto-detects the real related futures contract for your symbol (metals, forex, indices, energy, crypto).
Live Panel — POC, VAH, VAL, distance, VA position, active volume source.
Configurable Styling — independent colors, widths, and sizes for every element.
Open Source Attribution and Credits
In strict compliance with TradingViews House Rules regarding open-source code reuse, I explicitly credit and thank the original developer @LeviathanCapital for their open-source script "Market sessions and Volume profile - By Leviathan", which served as the structural foundation for the session isolation and baseline volume array logic in this indicator.
Significant Algorithmic Enhancements and Added Value:
While the primary mathematical grid expansion retains architectural roots from open source, this script introduces massive procedural improvements, structural upgrades, and new calculations developed entirely by me to transform it into an institutional-grade utility:
Automated External Futures Volume Normalization (Forex/CFD Context): Implemented a dictionary algorithm (getAutoFuturesTicker) to auto-detect and scale native tick charts against centralized futures markets (e.g., CME:6E1!, COMEX:GC1!, CME_MINI:NQ1!). This replaces synthetic broker data with authentic trading volume while maintaining local price scales.
Volume Nodes Engine (Multi-Peak HVN / LVN Detection): Developed an array scanning filter that runs on closed sessions to automatically isolate contiguous high/low volume anomalies. This effectively flags multiple supply/demand zones (like the humps of a double-distribution profile) beyond the baseline single POC.
Real-Time Live Zone Tracking: Integrated a dynamic recalculation engine for ongoing unclosed trading sessions, updating developing POCs, VAHs, and VALs seamlessly on the active bar state.
Interactive Live Dashboard Panel: Programmed a comprehensive on-screen status table displaying absolute values for POC/VAH/VAL, current distance from point of control, value area boundary status, and status indicators of the active volume feed.
Expanded Graphical and Period Customization: Redesigned aesthetic configurations, text label sizing, box boundary styles, and added resolution adjustments alongside line right-extensions.
Open Source Attribution and Credits
In strict compliance with TradingViews House Rules regarding open-source code reuse, I explicitly credit and thank the original developer LeviathanCapital for their work.
The original script "Market sessions and Volume profile - By @LeviathanCapital served as the logical foundation for the session isolation and baseline volume array logic in this indicator. All rights and original logical baselines remain under their respective ownership.
Indicador

Smart Flow Imbalance [StrixEDGE]TRADINGVIEW CATEGORIES
1. Volume
2. Trend Analysis
3. Oscillators
SEARCH TAGS (9)
smart-flow-imbalance, overlay-signals, order-flow, volume, relative-volume, buying-selling-pressure, accumulation-distribution, momentum, market-structure
DESCRIPTION
StrixEDGE Smart Flow Imbalance is Engine #06 in the StrixEDGE indicator framework. It is a flow-focused market-state tool designed to identify changes in directional quality, liquidity behavior, volatility structure and confirmation strength without relying on a single conventional oscillator.
WHAT THIS INDICATOR IS DESIGNED TO DO
Blends persistent flow, displacement and range structure into a directional participation score.
Rather than treating one input as a complete signal, StrixEDGE combines the engine's dedicated core logic with an optional DNA layer. The final result is normalized into a 0–100 Strix Score so the same framework can be read consistently across different symbols and timeframes.
HOW TO READ THE STRIX SCORE
• Above 72: bullish state / long-side trigger zone.
• Below 28: bearish state / short-side trigger zone.
• Around 50: balanced or neutral state.
• A signal is generated on a transition into a trigger zone, not on every bar that remains inside it.
SIGNAL & POSITION FRAMEWORK
When a valid state transition is detected, the overlay version can create a structured trade plan containing:
• Entry
• DCA level
• TP1
• TP2
• TP3
• Stop Loss
Each projected level includes its percentage distance from Entry. When a level is reached, the same chart label is updated with a ✓ marker. TP and SL outcome tracking is mutually controlled so the dashboard does not report contradictory terminal results for the same setup.
PROFESSIONAL DASHBOARD
The built-in StrixEDGE dashboard summarizes the active market state in a compact TradingView table, including:
• Engine and category
• Strix Score and directional bias
• Signal / market regime
• Flow pressure and trend quality
• Relative volume and ATR volatility
• Structure / VWAP context
• Active position and signal age
• Entry, DCA, TP1, TP2, TP3 and SL
• Hit status for each projected level
COMBINATION PROFILE
• CORE BALANCE
• Active DNA modules: 3
• Lookback: 24
• Smoothing: 5
• Signal threshold: 72
ENGINE DNA
• Displacement Efficiency — Directional body displacement normalized by ATR and relative volume.
• Range Structure Balance — Maps close location inside rolling high/low structure to a signed state.
• Normalized Flow Acceleration — Smooths ATR-normalized return × relative volume to estimate directional flow.
MARKET / STYLE PROFILE
• Market focus: Crypto
• Intended style: Swing
• Core engine: #06 Smart Flow Imbalance
• Category: Flow
NON-REPAINT / DATA HANDLING
By default, signals require a confirmed chart-bar close. This reduces intrabar signal fluctuation and makes historical signal placement more stable.
ALERTS
The generated script includes alert conditions for:
• Long state shift
• Short state shift
• DCA reached
• TP1 reached
• TP2 reached
• TP3 reached
• Stop Loss reached
HOW I USE IT
StrixEDGE is designed as a market-state and trade-structure tool rather than a standalone prediction system. Stronger setups generally occur when the Strix Score, market regime, flow pressure, structure and volatility context agree instead of relying on the trigger alone.
LIMITATIONS
No indicator can predict future price movement with certainty. Signals can fail during sudden news events, illiquid conditions, gaps, abnormal volatility, regime transitions or unreliable volume. DCA, TP and SL levels are systematic projections derived from the active setup and should not be interpreted as guaranteed outcomes.
Users should validate the indicator on the symbol, exchange and timeframe they trade, and should apply independent position sizing and risk management. Historical behavior does not guarantee future performance.
ORIGINALITY
StrixEDGE Engine #06 is built from generic price, volume, volatility, structure and confirmed-context primitives arranged in a dedicated engine formula and optional DNA layer. It is not intended to reproduce or rename a specific community indicator.
DISCLAIMER
For research and educational purposes only. This indicator is not financial advice and does not guarantee profitability. Indicador

Volume Profile ML [PickMyTrade]🔷 WHAT IT MEASURES
🔸 A rolling volume profile — traded volume binned across price, weighted triangularly around each bar's typical price rather than spread evenly across its whole range
🔸 Nine properties of every ARRIVAL at a high or low volume node — its share of row volume, rank percentile, local thickness, approach displacement, distance from the Point of Control, position within the profile, volume surge on approach, profile concentration, and position within the Value Area
🔸 An arrival resolves as a hold or a break by real price movement, checked in that order — undecided arrivals are discarded, not counted as failures
🔸 The Point of Control, Value Area, and every high and low volume node redraw on a rolling cadence as the window moves
――――――――――――――――――――――――――――――――――――――
🔷 THE ML ENGINE
🔸 A Lorentzian K-nearest-neighbour classifier, weighted by distance rather than counted equally, trained continuously as arrivals resolve — no repainting, no lookahead
🔸 Nothing about a node's absolute price is used as a feature — only how price approached it and what the node itself looked like
🔸 The vote shrinks toward the chart's own base rate when few neighbours are close, so a thin library never reads as confident
🔸 When the nearest analogues in the library aren't actually close, the script says so — "no analogue" instead of a percentage built on a bad match
🔸 Below a configurable warmup count it reads LEARNING, not a guess
――――――――――――――――――――――――――――――――――――――
🔷 SIGNALS AND DISPLAY
🔸 A circle marks a high-conviction read, a triangle a standard one — shape carries strength, colour carries direction
🔸 Blue for acceptance, orange for rejection, grey for anything that hasn't earned a direction yet, the same three colours across the profile, the vote, and the dashboard
🔸 An info table with Point of Control, Value Area, library size, the chart's own base rate, and the live analogue distance against its configured ceiling
🔸 3 alertconditions, worded as observations of what the classifier's reading — never as trade instructions
――――――――――――――――――――――――――――――――――――――
🔷 INPUTS
Profile Lookback / Rows — bars the profile is built from, and how finely it's binned. Default 240 / 48.
Rebuild Cadence — bars between profile recalculations. Default 5.
HVN / LVN Percentile — the volume percentile a row must clear to count as a high or low volume node. Default 80 / 20.
Re-arm Distance — minimum bars before the same node can register a new arrival. Default 10, floored at the resolution timeout.
K Neighbours / Library Cap — how many analogues vote, and how many resolved arrivals are retained. Default 9 / 100.
Shrinkage Weight — how hard a thin neighbourhood is pulled toward the base rate. Default 4.0.
Max Analogue Distance — the ceiling above which the vote reads "no analogue" instead of a percentage. Default 4.0.
Reject / Break Threshold — how far price must travel back, or close beyond, a node to resolve a test. Default 0.8 / 0.5 ATR.
Resolution Timeout — bars before an unresolved arrival is discarded. Default 25.
Conviction Threshold — vote at or above which an arrival is marked high conviction. Default 0.65.
――――――――――――――――――――――――――――――――――――――
🔷 REQUIREMENTS AND LIMITATIONS
🔸 The library is built forward from the chart's own loaded history — scroll back to load more and the script relearns from the new starting bar, so earlier votes can differ from what you saw before. This is bar history dependence, not repainting — no value changes after its own bar closes within a single run.
🔸 On instruments with no volume feed the profile itself carries no meaning, and the dashboard says so rather than showing an empty one anyway
🔸 Below the warmup count a node's own read is thin — the library size travels with every vote so that's never hidden
🔸 This script reports how historical arrivals resolved. It does not predict, and it is not a trading system on its own.
――――――――――――――――――――――――――――――――――――――
Built in Pine Script v6. Open source — Mozilla Public License 2.0. Indicador

Mbedaiwi - Market Structure and Price Action mbedaiwi - Market Structure & Price Action
Overview
This Pine Script v6 overlay brings market structure, liquidity events, order blocks, volume estimates, price imbalances, and chart-pattern candidates into one configurable workspace. It helps users examine where price has broken structure, where earlier zones remain active, and how several observations align on the same chart.
The indicator is intended for discretionary analysis and chart study. It is not an automated execution system or a backtested TradingView strategy.
Purpose and benefits
Compare short-term internal structure with broader swing structure.
Organize potential reaction areas using order blocks, imbalances, liquidity levels, and range bands.
Compare the volume associated with visible order blocks through an overlay or a separate right-side display.
Select the modules and labels needed for a particular workflow, reducing chart clutter.
Use alerts to monitor defined events without continuously watching the chart.
The integration follows a practical sequence: establish structure, locate relevant areas, observe price interaction, and optionally evaluate a rule-based setup. The components provide context for one another; agreement between them does not establish a probability of success.
1. Market structure
Internal and swing structure can be configured separately. The script supports SMC leg-transition detection and symmetric pivot detection, with adjustable lengths.
BOS: a break classified as continuation of the current structural direction.
CHoCH: a break against the previous structural direction.
CHoCH+: a CHoCH supported by an intervening higher low for a bullish change, or lower high for a bearish change, under this script's pivot and sequence rules.
HH, HL, LH, and LL: higher highs, higher lows, lower highs, and lower lows.
Strong/Weak High-Low: structural classifications based on the current directional state, not forecasts of whether a level will hold.
Each structure selector offers All, BOS, CHoCH (All), CHoCH, CHoCH+, and None. CHoCH (All) includes both ordinary and supported changes; CHoCH and CHoCH+ select their respective classifications. The separate Show BOS and Show CHoCH switches also affect visibility.
Historical and Present display modes, candle coloring, label sizes, and colored or monochrome themes provide additional control.
2. Order blocks and volume display
The script includes independent swing-break, volume-pivot, and legacy structure-break order-block engines. Available controls include zone boundaries, mitigation rules, retained-zone counts, overlap suppression, midlines, and breaker display.
Volume information can appear on the price-chart overlay, in a right-side chart, or in both locations. Users can choose the volume accumulation interval, including the interval between a broken pivot and its break, an origin window, or an origin-based interval.
How to read the volume numbers
The displayed volume belongs to the selected calculation interval. The percentage is that block's share of the summed volume of currently displayed non-breaker blocks. Changing visible blocks, filters, or retention settings can therefore change the percentages. They are not win rates or percentages of the instrument's entire trading volume.
Internal buy/sell activity is an OHLCV-based estimate. Close-location mode allocates volume according to the close's position within each candle's range; candle-direction mode allocates it according to candle direction. These estimates do not measure actual bid/ask transactions, institutional orders, or order-book liquidity. Volume-dependent outputs rely on the data supplied for the symbol.
3. Liquidity tools
Equal Highs and Equal Lows use an adjustable ATR-based tolerance. Liquidity Grabs identify excursions beyond tracked levels followed by a return inside those levels, subject to the detection rules.
Grabs are displayed as hollow frames around the relevant candle wick: blue for bullish lower-wick grabs and red for bearish upper-wick grabs by default. Optional text can be enabled. Detection sensitivity and retained history are adjustable.
Live previews can change or disappear before the candle closes. Liquidity Grab alerts require a confirmed bar. Separate trendline tools and trendline-break alerts are also available.
4. Price imbalances
The imbalance selector displays one of five types:
FVG: a three-candle gap between the first and third candles' price ranges.
Inverse FVG: a tracked FVG that is breached and reclassified in the opposite direction.
Double FVG: an overlapping area between a new FVG and a tracked opposite-direction FVG.
Volume Imbalance: a gap between adjacent candle bodies while their wick ranges overlap. Despite the name, this detection is price-based.
Opening Gap: a gap between adjacent candle ranges.
Controls include source timeframe, volatility threshold, extension, mitigation method, and maximum retained zones. The imbalance timeframe must be the chart timeframe or higher. Higher-timeframe imbalance detection uses completed source candles, so it becomes available after source-bar confirmation.
To hide only the FVG/type text while retaining the shaded zones, disable Show Imbalance Type on Zones. Re-enable it at any time from Inputs.
5. Premium, equilibrium, and discount
Optional bands divide a selected Swing, Internal, or Impulse range into upper, middle, and lower reference areas. Band width and colors are adjustable. These areas describe relative position within the selected range; they do not measure fundamental fair value or guarantee a reversal.
6. Chart-pattern candidates
The pattern module classifies recent pivot geometry and can display pattern boundaries, shaded zones, and a Detected Pattern table. Candidate types include triangles, wedges, broadening wedges, double tops/bottoms, and head-and-shoulders formations.
Pattern drawings are separate from the trendline module. Detection depends on pivot length, available history, and tolerance settings. In this release, a displayed pattern can remain after price has moved outside its boundaries until the detection state updates. Treat the pattern name as a geometric candidate, not confirmation that a formation remains valid or that a breakout will succeed.
7. Additional context and optional setup planning
Optional Fibonacci retracements, an OTE region, extension levels, and previous daily/weekly/monthly/quarterly highs and lows provide additional reference points.
The optional setup layer combines structural events with configurable checks such as liquidity sweeps, order-block or imbalance interaction, displacement, higher-timeframe direction, EMA alignment, volume, and RSI. Score and Strict modes control how these conditions are evaluated.
When enabled, the trade layer can display a hypothetical entry, stop, and up to three targets using configurable zone, structure, ATR, or risk-multiple methods. These are rule-based planning levels, not executed orders or verified performance results. The default mbedaiwi profile suppresses the trade layer.
How to use
Add the indicator to a standard candlestick chart and choose an analysis profile. The default mbedaiwi profile uses internal length 5, swing length 50, and close-based structural breaks. Select Custom or enable Override profile lengths when you want the manual lengths to take effect.
Choose the internal and swing events you want to see. Start with structure and a small number of zones before enabling additional modules.
Enable order-block metrics if you want volume comparisons. Select the accumulation method and overlay/side-chart layout appropriate for your analysis.
Enable Liquidity Grabs and select detection sensitivity. Distinguish a live preview from a completed event.
Choose an imbalance type and its mitigation method. Add premium/discount bands or prior-period levels if they help define context.
Enable Patterns only when studying pivot-based formations, and check the actual candles against the displayed boundaries.
Use Clean chart mode, individual visibility switches, label sizes, and zone-count controls to manage clutter. The Show tables switch controls on-chart tables.
If using the optional setup layer, choose a compatible profile, review all filters and risk settings, and evaluate its behavior before relying on the planning levels.
Reading entries, stops, targets, and exits
Use the indicator as a sequence of observations: structural direction, an area to monitor, confirmation, and a predefined risk/target plan. A BOS, CHoCH, or Liquidity Grab on its own is not an automatic instruction to buy or sell.
Step 1 - Read the structural context
Start with Swing Structure for the broader context, then use Internal Structure to examine shorter movements. Higher highs and higher lows describe an upward structure; lower highs and lower lows describe a downward structure. A bullish BOS is classified as continuation, while a bullish CHoCH marks a potential change from the preceding bearish structure. CHoCH+ adds the script's supporting pivot-sequence condition; it does not guarantee a reversal.
An internal bullish change can occur while swing structure remains bearish. Always identify which structure level produced the label. Pivot confirmations can arrive after the turning point and be drawn back at the earlier pivot bar.
Step 2 - Identify an area to monitor
A bullish order block, bullish FVG, discount band, previous low, or Equal Lows can provide a reference area for studying a possible bullish reaction. Price entering an area only establishes an interaction; it does not confirm that a rebound has started. Order-block volume percentages are calculated volume shares, not probabilities that the area will hold.
Step 3 - Observe confirmation
The following is an illustrative manual reading sequence, not the mandatory algorithm behind every setup generated by the script:
Price reaches a previously identified reference area.
Price moves below a tracked low and closes back above it, producing a confirmed bullish Liquidity Grab if the detection conditions are met.
Price subsequently breaks an internal structural level upward, producing a bullish CHoCH or CHoCH+ under the script's rules.
The user evaluates the completed confirmation candle or a later retest of the broken level, together with the broader structure and the planned invalidation level.
A retest may never occur, and confirmation can still fail. Do not assume that a marker anchored to an earlier candle was available in real time on that candle.
Step 4 - Understand the optional planning layer
The planning layer displays hypothetical levels when its setup conditions are satisfied:
Entry method: Market, Fibonacci, or Zone determines the entry-reference calculation.
Stop method: Structure, ATR, or Zone determines the stop-reference calculation. The selected invalidation level defines where the planned idea no longer applies.
Target method: Risk multiple, Smart money, or Hybrid determines how target references are calculated.
TP1, TP2, and TP3: up to three target references, according to the selected method.
Move stop to breakeven after TP1: updates the hypothetical stop to the entry reference after the first-target condition is met.
These are chart calculations. They do not send orders to a broker, establish actual fills, or move a real stop order.
To make this layer available, choose a profile such as Custom, enable Show trade layer (entry / SL / TP), and disable Structure only. The default mbedaiwi profile suppresses the trade layer. Enabling the display does not guarantee that levels appear immediately: the selected signal conditions and filters must also be satisfied.
Step 5 - Read risk multiples: a numerical example
Consider a hypothetical entry at 100 and a stop at 98. The distance between them is 2 per share, so 1R equals 2. In Risk multiple target mode:
Entry reference: 100.
Stop reference: 98.
1R target: 102.
2R target: 104.
3R target: 106.
This example explains arithmetic only. It is not a trade recommendation, a prediction, or a result produced by a backtest. It excludes fees and slippage. A real fill can differ from the plotted reference, and an actual exit can differ from the stop price. If the hypothetical breakeven option is enabled, a qualifying TP1 event changes the plotted stop reference to 100; this does not guarantee a cost-free exit in actual trading.
Step 6 - Interpret exits and changes in structure
A TP reached alert means that the script's target condition has been met. A Stop-loss reached alert means that its stop condition has been met. Neither confirms that a broker executed an order.
A bearish CHoCH during an upward move provides information about a structural change. It does not automatically mean that the planning layer closed a position, nor that every internal change requires the same response. Target exits, invalidation exits, and any discretionary response to opposing structure should be defined before acting on a setup. The script does not automatically carry out partial sales or discretionary exits described by a user's plan.
Manual analysis versus calculated setups
The manual sequence above explains how the visual components can be read together. The optional planning layer instead evaluates its configured rules, filters, and calculation methods. It does not necessarily require that exact sequence. Neither workflow supplies verified profitability or guarantees that a displayed setup will succeed.
Alerts
Available conditions cover internal and swing BOS/CHoCH/CHoCH+, liquidity grabs and sweeps, equal highs/lows, imbalance formation, zone interactions, order-block breaks, trendline breaks, detected patterns, and optional setup/target/stop events.
Select this indicator in TradingView's Create Alert dialog, then choose the event. Use Once Per Bar Close when you want close-confirmed notifications. General CHoCH alerts also include supported changes; separate CHoCH+ conditions are available. Some touch conditions can remain true across consecutive bars, so they should not be interpreted as one notification per zone for its entire lifetime.
Timing, historical drawings, and limitations
Pivot-based features require later bars to confirm earlier turning points. Labels and zones may be anchored back to those earlier bars, although the information was not available at that time.
Live candles and enabled previews can change before close. This indicator is not presented as universally non-repainting.
Zone removal depends on mitigation, age, overlap, and retention settings. Older drawings can disappear as new observations replace them.
Results depend on the symbol, timeframe, session, available history, and settings. Different indicators can use different definitions and produce different results.
The confluence score is a rule-based score, not a calibrated probability. Volume percentages and Strong/Weak labels are not measures of signal accuracy.
The planning layer does not provide a broker execution model, Strategy Tester results, or verified profitability. No accuracy, return, or future-performance claim is made.
Source acknowledgment
The hierarchical pivot-detection logic used in the Liquidity Grabs module is adapted from LuxAlgo's open-source "Pure Price Action Liquidity Sweeps", licensed under CC BY-NC-SA 4.0. Modifications include wick-frame rendering, display controls, and alert handling. Credit for the adapted source logic belongs to LuxAlgo.
This acknowledgment concerns the identified open-source component and does not imply access to LuxAlgo's closed-source Price Action Concepts indicator. This publication is not affiliated with or endorsed by LuxAlgo.
Intended use
For educational chart analysis and discretionary decision support. Users remain responsible for validating the settings, interpreting signals, and managing risk. No displayed zone, pattern, or setup guarantees a particular market outcome.
Indicador

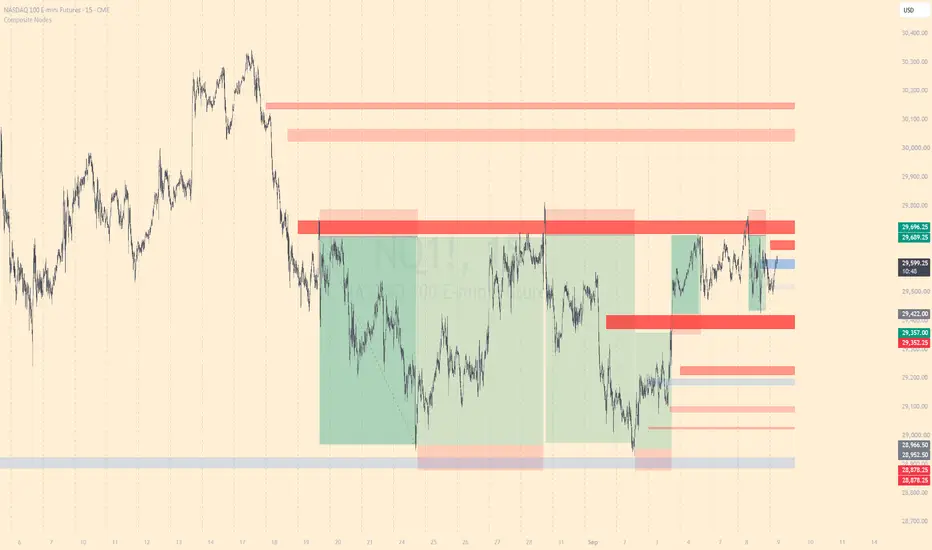
Composite HVN/LVN NodesComposite HVN/LVN Nodes
Most volume profile tools show one session at a time. This one accumulates high and low volume nodes across many sessions into a single map, so the prices that keep reappearing stand out from the ones that showed up once.
Each session is profiled separately. Its nodes are extracted and folded into a running composite where repeat sightings reinforce each other, unreinforced levels decay away, and levels price has torn through get demoted. Zones are shaded by relative strength — the darkest bands are the strongest currently on the map.
HOW IT WORKS
Detection finds a run of contiguous rows clearing the threshold, then anchors the zone on that run's actual volume peak. Anchoring on the first qualifying row instead biases every zone toward the lower peak of a multi-peak shelf.
Merging takes the union of two overlapping bands rather than the average of their centres. Averaging places the result in the valley between two shelves, covering neither.
Decay runs at every session close. A node that stops being reinforced fades and is eventually dropped.
Invalidation cuts a zone's weight hard when a single bar rips clean through it.
Conflict resolution removes one of any overlapping HVN/LVN pair. A price cannot be both a shelf and a gap.
Profiles are built from 1-minute intrabars rather than chart bars, so the map is the same on 1m as on 1h. Without this, coarse bars smear volume across rows they only passed through.
DEFAULTS ARE TUNED FOR NQ
Most thresholds are percentages of session range or session volume, so they travel between instruments reasonably well. The session times and the LVN threshold do not.
Sessions: Globex (1800-0930) and New York (0930-1700). For equities, use a single 0930-1600 and disable the other. Sessions must not overlap.
Resolution: 1 minute. The most important setting for consistency. The "Intrabars/bar" readout in the status line shows whether it is active; 0 means it has fallen back to chart bars, which happens past roughly 100k intrabars of history.
Detection: 200 rows, sensitivity 6, HVN 70%, LVN 10%. Roughly one row per point on a typical NQ session range. The thresholds are asymmetric on purpose: 70% is permissive enough to catch shoulders as well as the POC, while 10% is strict because on a liquid instrument nearly everything trades a little and a loose setting produces gaps that aren't really gaps. On thinner instruments 10% may find nothing.
Node width: max 12% of range. Mainly restrains LVNs. At a 10% threshold a genuinely dead pocket can run a long way, and without a ceiling one gap swallows half the range.
Volume weighting — each session's contribution is scaled by how active it was against a rolling 20-session average, capped at 3x either way so one event day cannot dominate. Sessions below 35% of average volume are skipped entirely, which filters holidays and half days on NQ. Set to 0 to disable.
Composite: half-life 50 sessions. Note that is sessions, not days: with both enabled that is two per weekday, so about five trading weeks. Halve it for a faster-moving map.
Conflicts: stronger wins. The lighter of an overlapping pair is removed, ties going to the HVN, since volume that demonstrably traded is harder evidence than volume that didn't. Zones that merely touch are left alone — an HVN against an LVN is a real structure, the edge of a shelf against a gap.
Archive: off. When on, invalidated nodes freeze in place with a dashed border instead of disappearing, so you can see where a level sat and how long it lasted. Useful for review, cluttered live.
ADAPTING IT
Start with the session times; everything depends on those being right. Then check LVN detection, which assumes NQ-like liquidity. If the map is too sparse or too crowded, adjust "Drop below weight" and "Max nodes kept".
NOTES
Nodes are computed at session close and are not recalculated afterwards, but their appearance changes as weights decay and merge — shading is relative to the strongest node currently on the map, not an absolute scale.
TradingView caps drawing objects at 500 boxes. Active and archived nodes share that budget.
This is an analysis tool, not a signal generator. It marks prices where volume repeatedly concentrated or repeatedly didn't. What that means for any given trade is up to you.
Indicador

Volume Footprints**Footprints (Volume Footprints) — Description**
Footprints breaks down each price bar to show where trading activity concentrated within it. Instead of a single volume number per bar, it splits a bar into horizontal price levels and reports how much volume traded at each level, along with an estimated buy/sell breakdown. Everything is presented in a compact, docked information box rather than drawn across the chart, keeping the price panel clean. The indicator's full name is "Volume Footprints," shown in the library and settings, while the chart legend displays the short name "Footprints."
**What it shows**
The indicator samples a finer timeframe inside each bar to reconstruct how volume was distributed across price. It then displays that distribution as a price ladder, with the highest price at the top. For each level it shows the volume attributed to buying, the volume attributed to selling, and the net difference between them (delta). A totals row at the bottom sums buying, selling, and net delta for the whole bar.
Two reference points are marked with colored dots in their own narrow columns: the Point of Control (P), which is the single price level where the most total volume traded, and the current price level (C), which shows where live price sits within the bar. A volume heatmap shades each row so that busier levels appear more saturated, making the most active prices easy to spot at a glance.
An optional candlestick column runs down the far-left side of the box, drawn to scale against the same price ladder so it mirrors the inspected bar's candle on the chart — a solid body between the open and close, thin wicks to the high and low, and colored green when the bar closed up or red when it closed down. Because it is drawn from table cells, its smoothness depends on how many rows the ladder has; a coarse ladder produces a blockier candle.
The information box also carries a title row showing the indicator name, which bar is being examined, the timeframe settings in use, and a live countdown to the close of the forming bar.
**Buy/sell estimation**
The buy and sell figures are estimated from price direction within the sampled sub-bars rather than from actual bid/ask transaction data. Rising sub-bars are counted as buying and falling sub-bars as selling. As a result, the buy, sell, and delta values are an approximation of activity, not a measurement of true order flow.
**Timeframe guidance and warnings**
For the indicator to work, the chart timeframe must sit between the two timeframe settings: the cell granularity must be below the chart timeframe, and the footprint bar timeframe must be at or above it. If the chart is on a higher timeframe than the footprint setting, the box displays a warning in place of the ladder. If the cell granularity is not below the chart timeframe, the box reports that as well. The footprint timeframe may also be left as "Chart" to match the chart's own timeframe, in which case no timeframe warning is shown.
**User Inputs**
- **Footprint bar timeframe** — Sets which bar the box analyzes, such as one hour. This should be at or above the chart's timeframe. Volume from finer sub-bars is accumulated across chart bars until this bar completes, then organized into price levels.
- **Cell granularity** — Sets the finer timeframe used to build the price levels inside each bar. This must be below the chart's timeframe; otherwise no data is returned and the box reports this.
- **Stable cells (closed sub-bars only)** — Affects the forming bar only. When on, buy/sell figures count only sub-bars that have fully closed, so numbers accumulate steadily instead of shifting between buy and sell as price moves; this introduces a slight lag at the live level. When off, the still-forming sub-bar is included for maximum responsiveness, at the cost of the current level's figures fluctuating.
- **Row bucketing mode** — Chooses how price levels are formed. Fixed price step builds a continuous ladder on a fixed price grid, giving every level from the bar's low to high a permanent row that does not shift as the bar develops. Range slices instead divides the bar's high-to-low range into a set number of equal parts, which rescales as the bar's range grows.
- **Price step (ticks)** — Used in Fixed price step mode. Sets the height of each row in ticks. Smaller values create more, finer rows; larger values create fewer, coarser rows. If a bar spans more levels than the display can hold, the highest levels are truncated, which is resolved by raising this value.
- **Price rows (Range slices mode)** — Used in Range slices mode. Sets the number of equal divisions of the bar's range. It has no effect in Fixed price step mode, which sizes the ladder automatically.
- **Footprint bar to inspect** — Selects which bar the box displays, counting back from the newest. Zero is the bar currently forming, one is the last completed bar, and so on.
- **Info box position** — Anchors the information box to a chosen area of the chart, such as a corner or middle edge, so it can be moved clear of price.
- **Info box text size** — Sets the font size inside the box, from tiny to large.
- **Show candlestick column** — Toggles the far-left candlestick column. When off, the column is removed entirely and the box narrows.
- **Show chart marker** — Toggles an on-chart arrow that points to the most recent candle of the bar being analyzed.
- **Marker color** — Sets the color of that on-chart arrow.
- **Buy color** — Sets the color used for net-buying delta figures.
- **Sell color** — Sets the color used for net-selling delta figures.
- **Candle up color** — Sets the candlestick column's color when the bar closed at or above its open. Defaults to a standard chart green.
- **Candle down color** — Sets the candlestick column's color when the bar closed below its open. Defaults to a standard chart red.
- **Heat (volume) tint** — Sets the hue of the volume heatmap that shades each row by activity, with the busiest level appearing brightest.
- **Info box background** — Sets the solid background color of the box, over which the heatmap tint blends.
- **Text** — Sets the color of the text inside the box.
- **Title text color** — Sets the color of the title-row text.
- **Title background** — Sets the background color of the title row.
- **POC dot color** — Sets the color of the dot marking the Point of Control.
- **Current price dot color** — Sets the color of the dot marking the row where live price currently sits. Indicador

Volume Delta Footprint Zones HeatmapVolume Delta Footprint Zones Heatmap (ΔFP)
Order-flow context from CVD. It marks the price levels where aggressive buying or selling showed up without moving price, and keeps those levels on the chart as horizontal lines that fade as they age.
The idea
Delta at a price level tells you how much aggression traded there — but most delta is just the cost of moving price. A bar that rallies 20 points obviously prints positive delta, and that part says nothing you couldn't read off the candle. What's worth marking is delta that did not produce a move: aggression that got absorbed by passive size sitting at a level.
So rather than accumulating raw delta, this script accumulates the residual:
It keeps a rolling average of delta per point of price movement over the last N bars.
For the current bar it computes the delta you would expect from that bar's price change.
Actual minus expected is the unexplained delta.
That residual is spread across the bar's footprint rows in proportion to each row's share of the bar's net delta, and added to a running total for that price.
A level therefore builds up value when trade happens there that the price move doesn't account for. Positive = unexplained buying, drawn green above price. Negative = unexplained selling, drawn red below price.
On a bar with essentially no price change the expected delta is ~zero, so the whole of the bar's delta counts as unexplained — which is the intended behaviour, not a special case.
Decay, not accumulation
Every stored level fades by a fixed percentage each bar, so the map is an exponentially weighted average rather than a session-long total, and recent flow dominates. A contribution keeps (1 − rate)^N of its weight after N bars — at the 5% default that is roughly 60% after 10 bars, 36% after 20, 8% after 50. Levels that fade below the minimum threshold are dropped.
Levels are also removed the moment price trades through them, and are barred from re-forming until price moves a configurable distance away. The display therefore stays on levels that have not been tested yet.
Reading it
Green line above price — unexplained buying that was absorbed there. Supply sat on it.
Red line below price — unexplained selling that was absorbed there.
The label on each line is the level's current residual delta. Red labels show sell-side magnitude as a positive number.
Lines get shorter-lived and thinner on the ground when flow is being explained by the move itself; they persist and stack when price is grinding against size.
Thicker clusters are simply several adjacent rows that each cleared the threshold. Up to 30 levels are kept per side; when both sides are full the furthest level is dropped first.
Limitations — please read before drawing conclusions
Footprint delta is approximated, not tape-derived. Treat magnitudes as relative to each other, not as absolute traded size.
Requires footprint data for your plan and symbol.
Decay only advances on bars where the footprint request actually returns data. On the 1S default, where sub-minute history is shallow, older levels freeze rather than fading — scroll back far enough and the map stops ageing.
The expected-delta baseline is a single rolling mean. It is a crude model of the delta/price relationship and it is symmetric — it does not distinguish up-moves from down-moves.
A level that replaces another in the same drawing slot on the same bar starts one bar late, and a level that lives only a couple of bars in a reused slot may not draw a line at all, though its label still appears.
No signals, no alerts, no directional calls. This is context only, and it is published for people who want to experiment with the idea rather than as a finished system.
Notes
Delta is accumulated per price grid, decays exponentially, and is never reinforced — a level only ever fades once the flow that built it stops. Zones are drawn with plot.style_linebr and the plot layer forces a break whenever a drawing slot changes level, so every segment is horizontal. Indicador

Relative Volume Breakout Context [Pineify]Relative Volume Breakout Context
Overview
Relative Volume Breakout Context tests an intraday price escape against normal volume at the same exchange-session position, then tracks price acceptance as participation changes.
Problem Definition
Intraday volume has a time-of-day shape: opening, midday and closing bars do not share one natural activity level. A rolling average mixes those positions, making routine opening activity look exceptional or meaningful midday volume look ordinary. A fixed channel break adds price displacement but not time-adjusted participation. A one-bar marker also loses whether price later holds its boundary on sustained or fading volume.
Design Rationale
Each bar is assigned a slot by elapsed minutes from a session start, and volume is compared only with prior observations from that slot. Exponentially weighted statistics let old sessions lose influence, trading stability for responsiveness. A dispersion floor controls unstable Z scores. Price must close beyond a prior range by a minimum ATR fraction. The joint score uses a geometric mean so weak price or volume constrains the result; an additive score could hide that weakness. Freezing the crossed rail adds state, but preserves an auditable acceptance boundary after confirmation.
Key Features
Prior-only same-position volume expectation with sample reliability and a dispersion floor.
ATR-normalized breakout joined with volume surprise in one qualified event.
Frozen acceptance zone, one-shot decay alert, bounded labels and dashboard.
How It Works
Exchange-local bar time becomes elapsed session minutes. On 1-30 minute charts, elapsed time divided by chart interval selects one of 1,440 slots. Each stores a count, exponential volume mean and variance. The current bar reads them before updating, preventing self-inclusion.
After enough samples, dispersion is the larger of observed deviation and a percentage of expected volume. Volume Z is current minus expected volume divided by dispersion, capped at plus or minus five. Relative volume is the current/expected ratio; reliability rises with sample count.
Price rails are the highest high and lowest low of preceding bars. A fresh event closes beyond a rail, exceeds minimum ATR distance and meets volume Z. Volume and distance form a reliability-scaled geometric score with directional sign.
Confirmation freezes the rail. The frontier keeps the greatest high or lowest low while price remains outside. Z falling to the decay threshold creates one thinning alert. Closing through the rail invalidates tracking; age can expire it. Transitions require a completed bar.
How Multiple Indicators Work Together
Slot normalization asks whether participation is unusual now; the prior range asks whether price left an observed boundary; ATR standardizes escape depth; reliability limits warm-up confidence; memory tests later acceptance. Without volume this is a routine breakout, without price it is only RVOL, and without memory it cannot distinguish sustained support from thinning participation.
Trading Ideas and Insights
Treat confirmation as context, not an order. A green or red zone shows accepted extension from the frozen boundary. Amber means price still holds outside while same-position participation has decayed. That can frame questions about consolidation, fragility or absorption, but does not predict failure. Compare events with one instrument, session template and interval.
Unique Aspects
Common RVOL blends unrelated day parts, while common breakout tools stop at the crossing. Here, prior-only per-slot statistics feed a frozen-boundary state. Initiation requires time-adjusted participation and volatility-scaled displacement; continuation separates price acceptance from volume support. The thinning state remains descriptive rather than claiming lower follow-through volume causes reversal.
How to Use
Match session start and length to the regular exchange session and use a standard 1-30 minute chart. Let each slot collect the minimum samples; the dashboard shows WARMING before readiness. Faint lines are candidate rails. A diamond and RVOL label mark confirmation; the band spans frozen rail to frontier. Pane Z explains volume and signed score shows joint context. Set alerts to Once Per Bar Close.
Customization
Short memory adapts faster but is noisier; long memory is steadier but lags change. Minimum samples trades availability for depth. Raise the dispersion floor when quiet history overreacts. Range length and ATR distance control price selectivity; volume Z controls participation. Decay Z sets cooling and event age bounds observation.
Assumptions and Limitations
Bars must align with the configured exchange-local session. Holidays, half days, halts, extended-hours mixing and template errors reduce comparability. Bars use opening minute and may span session end. Missing volume disables scoring; tick volume is not centralized traded volume. Exponential statistics are path-dependent, capped Z is not probability, and ATR or rails lag. The script does not infer order intent, fills, profitability or next direction. Feed revisions and parameters can alter history. Values move intrabar; transitions and alerts commit at close.
Conclusion
This indicator replaces mixed-time RVOL with a session-position benchmark and extends a qualified breakout into an acceptance path. It reports escape, participation and thinning as context, not a forecast.
Indicador

Adaptive Market Volume_Forex_more### Adaptive Market Volume – Forex & Gold
**Adaptive Market Volume** was designed to make volume/activity analysis more useful in markets where the volume displayed by the instrument does not necessarily represent the entire market, such as Forex, Gold, and index CFDs.
In decentralized markets such as Forex, the indicator **does not attempt to convert tick volume into true global volume**. Instead, it uses related centralized futures markets as institutional activity proxies. Each data source is normalized independently and, when available, combined with the instrument's local activity through a **Hybrid model**, producing a relative measure of market participation.
For example, **GBPUSD uses British Pound futures (6B)** as a reference, **EURUSD uses Euro futures (6E)**, and **XAUUSD uses Gold futures (GC)**. Supported index and energy CFDs use their corresponding futures markets as activity proxies as well.
The indicator also applies time-based normalization to reduce distortions caused by different trading sessions and typical intraday volume patterns.
Additional analysis modes include **Relative Momentum, Cumulative Effort, Efficiency, Micro Z-Score, and Micro Contrast**. Micro Contrast is especially useful on lower timeframes such as M1–M5, making differences between low, medium, and high activity easier to visualize without changing the underlying Adaptive Volume calculation.
**Recommended markets:**
**Forex:** EURUSD, GBPUSD, AUDUSD, NZDUSD, USDJPY, USDCHF, and USDCAD.
**Gold:** XAUUSD.
**Supported Indices:** Nasdaq 100, S&P 500, Dow Jones, Russell 2000, Nikkei 225, Hang Seng, DAX, and BRA50/Ibovespa when recognized through supported ticker aliases.
**Energy:** WTI Crude Oil and Natural Gas on supported symbols.
**Crypto, stocks, and futures:** use the native volume available from the instrument's own market/data feed.
**Important:** Adaptive Market Volume represents **relative market activity, not absolute global volume**. Results on Forex and CFDs depend on the availability and quality of both the local data feed and the corresponding futures proxy. Forex crosses without a direct proxy—such as EURJPY, AUDJPY, EURCHF, CADJPY, and CHFJPY—can still be used, but rely primarily on local activity and therefore do not have the same Adaptive coverage as the recommended Forex pairs.
Indicador

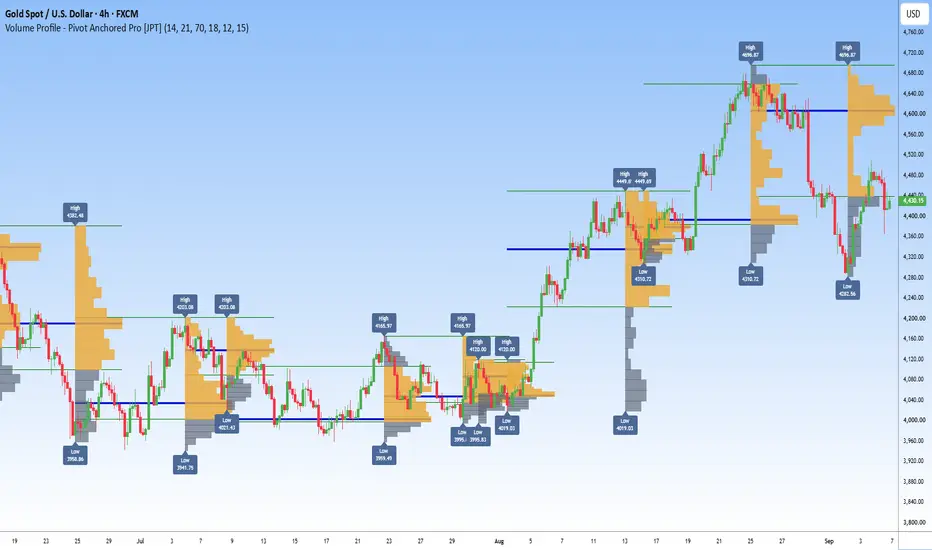
Volume Profile - Pivot Anchored Pro [JPT]🔷 OVERVIEW
Volume Profile – Pivot Anchored Pro is an educational volume analysis indicator that automatically creates volume profiles between confirmed swing highs and swing lows. It helps traders visualize where significant trading activity occurred throughout each market swing.
The indicator displays important volume-based levels including the Point of Control (POC) and Value Area High/Low (VAH/VAL), allowing traders to study areas where price may have experienced strong acceptance or rejection.
The indicator is designed to help traders analyze market structure, volume distribution, and key price areas. It does not predict future price movement or guarantee profitable trades.
🔷 FEATURES
• Automatic pivot high and pivot low detection
• Pivot-to-pivot volume profile generation
• Bullish and bearish volume visualization
• POC (Point of Control) level
• VAH (Value Area High) level
• VAL (Value Area Low) level
• High and Low labels for each profile
• Multiple historical volume profiles
• Customizable profile rows
• Adjustable Value Area percentage
• Adjustable profile width
• Customizable colors and display settings
• Clean chart layout with minimal clutter
🔷 HOW IT WORKS
• Detects confirmed swing highs and swing lows.
• Identifies completed price swings between pivot points.
• Calculates the volume distribution across different price levels within each swing.
• Identifies the POC, representing the price level with the highest traded volume.
• Calculates the Value Area, based on the selected Value Area percentage.
• Displays VAH and VAL to define the upper and lower boundaries of the Value Area.
• Draws the volume profile directly on the chart for easy market analysis.
🔷 HOW TO USE
Look for newly completed pivot-to-pivot volume profiles.
Use the POC to identify important high-volume price levels that may act as areas of support, resistance, or price acceptance.
Use VAH and VAL to understand the boundaries of the Value Area and observe how price reacts around these levels.
Compare multiple profiles to study how volume distribution changes from one market swing to another.
Consider combining the indicator with your own price action, market structure, support/resistance, liquidity, and risk management techniques.
🔷 IMPORTANT NOTE
This indicator is intended for educational and analytical purposes only. Volume Profile levels should be treated as reference areas rather than guaranteed support or resistance.
Always perform your own analysis and use appropriate risk management before making any trading decisions.
Volume Profile – Pivot Anchored Pro helps you see not only where price moved, but also where the market traded the most volume during each major swing. Indicador

Smooths Session Volume ProfileOverview
Smooths Session Volume Profile (SSVP) is built around a single volume-splitting engine that feeds three different views of the same underlying data: a per-bar footprint table, a compact mobile dashboard, and a session-scaled Volume Profile with Point of Control, Value Area, and Imbalance detection. Every number shown anywhere in the script traces back to one buy/sell volume calculation performed once per bar.
Why these are one script, not a mashup
The footprint table and the Volume Profile are not two indicators placed side by side — they are two resolutions of the identical volume model. The table shows that model at full per-bar detail over a short recent window; the profile aggregates the exact same bar-level buy/sell split over whichever session(s) the user selects. The session tools (highlight boxes, session-based profile scaling, Naked POC) extend that one model with time-of-day awareness rather than adding a separate feature. Removing the table would not simplify the script's purpose, it would just remove one lens on the same data the profile already uses.
Concepts used
Selectable volume engine: Geometric splits each bar's volume by where it closed inside its own high-low range. Intrabar reads real up/down volume from a lower timeframe via TradingView's own ta library. Footprint reads TradingView's native per-tick request.footprint() data (Premium/Ultimate plans only). Every other calculation in the script consumes whichever engine is active, unchanged.
Per-bar truncated-normal volume split: rather than splitting a bar's volume evenly across the ticks it traded, the script models the buy side and the sell side as separate truncated normal distributions inside the bar's own high-low range, centered toward where the bar actually closed. This produces a continuous, weighted density instead of a flat histogram bar.
Volume Profile as a summed density: the same per-bar truncated-normal components are summed across every included bar into one continuous curve, which is then sampled to locate the Point of Control (the price of maximum combined density), the Value Area (the narrowest band containing a chosen percentage of the modeled volume), and diagonal volume imbalances between adjacent price levels.
Session-aware scaling: Asia, London, and New York are each tracked independently — the script knows whether a session is currently forming or was last completed, and the profile can be built from the live union of whichever sessions are toggled on, instead of a fixed bar count.
Naked POC: the instant a session's occurrence closes, that session's own standalone Point of Control is computed independently of the combined profile and kept on the chart as an untested level until price actually trades back through it.
Self-checking math: the Overlap reading (OVL) measures what share of buy and sell volume occurred at the same prices, from 0 (fully separated, directional) to 1 (fully overlapping, balanced/rotational). The Residual reading (RES) independently re-integrates the density model and compares it back to the real volume it's supposed to represent, in parts-per-million, so the script can flag its own modeling error rather than silently drawing a profile that doesn't add up.
How to use it
Add it to any chart and timeframe. Use the Volume Profile's POC as a magnet level and its Value Area edges as boundaries between accepted and rejected price. Diagonal imbalances mark price levels where one side of the market overwhelmed the other. Toggle individual sessions in and out of "Include in Profile" to isolate one session's structure or build a composite of several. Switch to the footprint table or the mobile dashboard for the identical volume data at per-bar resolution instead of session-aggregated.
Originality
The per-bar truncated-normal volume model — shared by the footprint table and the Volume Profile alike — is the mechanism this script is built around, not an assembly of standard metrics. Session-aware profile scaling, Naked POC seeded independently per session, and the self-checking Residual metric are not reused from another publication; the detection, modeling, and rendering logic here were written for this script.
Inputs
Volume Profile — Profile Period/Session Scaling mode, Style (Line/Columns/Histogram), Width/Resolution, Gap From Chart, bell colors and fill
Session Profile Scaling — per-session time windows, time zone, Include in Profile and Show Highlight toggles, highlight colors
Metrics — Point of Control, Value Area, Imbalance thresholds, Naked POC, Balance Tilt, Residual Tolerance
Data Engine — volume engine selection and its parameters
Table Display — footprint table and mobile dashboard appearance
This indicator has no buy/sell signals, alerts framed as trade calls, or strategy logic — it is a volume-analysis tool. It does include TradingView alertcondition() entries for session starts and Overlap-state changes, which fire on data conditions, not trade recommendations. Indicador

SMC EngineSMC Engine
Overview
SMC Engine is a market-context indicator designed to identify potential liquidity sweeps and directional pressure around a selected session range.
The indicator combines an open-based NY range, candle spread analysis, and lower-timeframe volume pressure to classify market conditions such as Stop Hunts, directional aggression, and breakouts.
The default session is 09:30–10:30 New York time, but the session and timezone can be adjusted from the settings.
Key Features
Open-based NY session range
Automatic range box visualization
Projected range levels after the session
Candle spread anomaly detection
Lower-timeframe volume pressure
Stop Hunt High detection
Stop Hunt Low detection
Bullish Aggression detection
Bearish Aggression detection
Breakout Up/Down classification
Real-time sentiment dashboard
How It Works
1. Open-Based NY Range
During the selected session, the indicator tracks the highest and lowest candle opening prices.
These levels form the open-based range used by the sentiment engine.
Note: This is an open-based range, not a conventional opening range calculated from candle highs and lows.
2. Spread Analysis
The indicator compares the current candle's spread (High - Low) with its average spread over the selected baseline period.
Default settings:
Spread Baseline: 50 bars
Spread Anomaly Multiplier: 2.0
When the current spread exceeds the baseline multiplied by the anomaly multiplier, it is classified as a spread anomaly.
3. Volume Pressure
The indicator uses lower-timeframe candle data to estimate directional volume pressure.
Lower-timeframe close > open → volume is counted as positive
Lower-timeframe close < open → volume is counted as negative
Lower-timeframe close = open → volume is ignored
The resulting value is used as a volume-pressure proxy.
This is not true bid/ask volume delta.
Sentiment Conditions
Stop Hunt High
A Stop Hunt High is identified when:
The candle has an unusually large spread
Price trades above the open-based range high
The candle closes back at or below that level
Lower-timeframe volume pressure is negative
The signal is displayed with an orange downward triangle.
This can be viewed as a potential bearish liquidity-sweep setup.
Stop Hunt Low
A Stop Hunt Low is identified when:
The candle has an unusually large spread
Price trades below the open-based range low
The candle closes back at or above that level
Lower-timeframe volume pressure is positive
The signal is displayed with an orange upward triangle.
This can be viewed as a potential bullish liquidity-sweep setup.
Bullish / Bearish Aggression
When a spread anomaly occurs without meeting the Stop Hunt conditions, the indicator evaluates candle direction and volume pressure to identify:
Bullish Aggression
Bearish Aggression
Air Pocket/Uncertain
Breakouts
When the spread is not classified as an anomaly, the indicator can identify:
Breakout Up
Breakout Down
These classifications are based on price closing beyond the open-based range together with corresponding volume pressure.
How to Use It
The indicator is primarily intended as a market-context and confirmation tool, rather than a standalone buy/sell system
A simple way to use the Stop Hunt signals is:
Bullish Setup
Stop Hunt Low → wait for confirmation → consider long
When an orange Stop Hunt Low appears, avoid entering immediately. Observe the following price action and look for bullish confirmation before considering a long trade.
Bearish Setup
Stop Hunt High → wait for confirmation → consider short
When an orange Stop Hunt High appears, avoid entering immediately. Observe the following price action and look for bearish confirmation before considering a short trade.
The Stop Hunt signal should therefore be treated as a setup/area of interest, not an automatic entry signal.
Traders can combine the signal with their own market structure, price action, risk management, and higher-timeframe analysis.
Dashboard
The dashboard displays:
VSA Price Spread — current candle spread in ticks
Baseline Spread — average spread used for anomaly detection
Volume Pressure — calculated lower-timeframe directional volume pressure
Current Sentiment — current classification produced by the engine
Recommended Usage
The default configuration is designed around using a lower timeframe for volume-pressure analysis, such as a 1-minute lower timeframe on a 5-minute chart.
The appropriate settings can vary by market, symbol, and timeframe, so traders should test the indicator under the conditions in which they intend to use it.
Important Limitations
The range is based on candle opens, not highs and lows.
Volume Pressure is a directional-volume proxy and should not be interpreted as true bid/ask delta.
A Stop Hunt signal does not guarantee a reversal or profitable trade.
Breakout classifications do not guarantee that a breakout will continue.
The indicator does not determine stop-loss placement, take-profit levels, or position sizing.
Market conditions, liquidity, and data-feed characteristics can affect the behavior of lower-timeframe calculations.
Traders should independently test and validate the indicator before using it in live trading.
SMC Engine is intended for market analysis and educational purposes and should be used together with appropriate risk management. Indicador

The Magnet ModelThe Magnet Model — Opening Range Volume Profile
The Magnet Model ORVP is designed to turn the opening auction into a simple, repeatable map of where volume established value and where those levels may continue to matter throughout the trading session. It will automatically map the key volume-based levels established during New York opening range.
Instead of manually drawing a Fixed Range Volume Profile each morning, the indicator automatically builds the opening profile and identifies the Point of Control (POC), Value Area High (VAH), and Value Area Low (VAL). Once the opening range is complete, these levels extend to the right, allowing traders to monitor how price interacts with them throughout the session.
Key Features
Automatic 9:30–9:46 AM New York Opening Range Volume Profile
Automatically calculates VAH, POC, and VAL
70% Value Area by default
VAH, POC, and VAL automatically extend to the right
Shaded Value Area between VAH and VAL for quick visual reference
Current ORVP is highlighted pink
Previous ORVP zones can use different colors to distinguish sessions
Adjustable number of historical ORVPs displayed
Clean date labels such as 8/31 ORVP
Adjustable profile rows and profile width
Customizable colors, line widths, and line styles
Optional Overlap Detection Deletion to automatically remove older ORVP zones that overlap the newest value area
Designed to maintain a clean chart while preserving important historical opening-range levels
How It Can Be Used
The ORVP provides a structured framework for evaluating the market after the opening range has formed.
VAH, VAL, and POC can serve as important areas to monitor for:
Acceptance and rejection
Support and resistance
Breakouts and failed breakouts
Retests
Potential price magnets
Continuation or reversal opportunities
Historical ORVP levels can also remain on the chart, allowing traders to identify when price returns to areas of value established during previous sessions.
Best Used With Confluence
While The Magnet Model ORVP is powerful on its own, it can become even more effective when combined with other high-quality market references and confirmation tools.
Consider looking for confluence with VWAP, Simple Moving Averages (SMAs), Initial Balance (IB), key session levels, and order flow.
Some of the strongest areas of interest can develop when multiple independent levels or signals align with an ORVP VAH, VAL, or POC, providing additional context for potential support, resistance, acceptance, rejection, and directional movement.
The goal is not to trade an ORVP level blindly, but to use it as part of a broader framework of confluence.
Overlap Detection
When Overlap Detection Deletion is enabled, the indicator compares each newly completed value area with older ORVP zones.
If an older VAH-to-VAL value area overlaps the newest value area, the older profile is automatically removed.
This optional feature helps reduce chart clutter and keeps the focus on distinct opening-range value areas.
Default Configuration
Opening Range: 9:30–9:46 AM New York
Value Area: 70%
Profile Rows: 100
VAH / VAL / POC: Black, 2-width lines
Current Value Area: Pink, 20% opacity
Historical Value Areas: Differentiated by color
Send me a message with any questions or requests.
For educational and informational purposes only. This indicator does not provide financial advice or guarantee future market behavior. Indicador

Uranium VolumeUranium Volume — PVT Momentum
Uranium Volume is an experimental momentum indicator based on price percentage changes combined with the logarithm of trading volume. Its purpose is to provide a visual representation of relative price-volume pressure, helping traders observe moments of acceleration or weakening momentum.
🔬 How It Works
The indicator calculates a simplified PVT (Price-Volume Trend) change:
PVT Change = ((Current Price − Previous Price) / Previous Price) × log(Volume)
The price source used in the calculation can be selected by the user:
Close — closing price
HLCC4 — average of High, Low, and two Close values
HL2 — average of High and Low
HLC3 — average of High, Low, and Close
The resulting value is then smoothed using an EMA (Exponential Moving Average). The default period is 9.
📊 Visual Interpretation
The columns display the smoothed indicator value, while the column color is determined by the price/volume change of the current bar:
🟢 Lime: positive price change relative to the previous bar.
🔴 Red: negative price change.
🔵 Blue background: confirmed bar with a positive or neutral change.
🟠 Orange background: confirmed bar with a negative change.
The indicator can be used as a complementary tool to observe momentum, expansion, or loss of strength, together with price action, volume, trend analysis, and other technical-analysis tools.
⚙️ Settings
Price Mode: determines which price reference is used in the calculation.
MME Reactor Core: controls the EMA period applied to the PVT Change. Lower values make the indicator more responsive, while higher values provide a smoother reading.
⚠️ Important
Uranium Volume is a technical-analysis tool, not an automated buy or sell system. The indicator's colors and values should not be interpreted in isolation as guaranteed entry or exit signals.
The indicator uses price and volume data available on the chart and should be analyzed within the context of the selected asset and timeframe. Different markets may have different volume characteristics, so results may vary depending on the instrument.
No financial results are guaranteed. Users are responsible for their own investment decisions and risk management.
🧪 Indicator Name
The name "Uranium Volume" is a visual reference to the concept of energy and momentum and does not imply that the indicator is related to the uranium market or uranium-mining assets. Indicador

Regime Gated Confluence Score [Pineify]Regime Gated Confluence Score
Overview
This pane indicator combines trend, momentum, and volume after a four-state gate selects meaning and weight. The main score and dashboard reconcile signed contributions.
Problem Definition
Fixed-weight confluence hides a regime error. Positive RSI may confirm a trend but mark extension in a range. EMA separation can persist after efficient travel ends. Relative volume shows participation, not acceptance. A permanent sum can stay strong when path efficiency is low, factors disagree, or ATR leaves its baseline, so users cannot tell whether magnitude reflects agreement or one dominant input.
Design Rationale
ATR-normalized EMA separation and slope measure trend across price scales. Centered RSI supplies momentum; RANGE reverses it to express a fade. Volume pressure combines capped relative volume with close location without claiming aggressor flow. EMA spread and path efficiency classify structure; ATR versus baseline identifies displacement. Lower hold thresholds add hysteresis. A trained model would add hidden data assumptions, while fixed weights preserve the failure. Explicit rules accept sensitivity and lag for auditability.
Key Features
Four regimes with hysteresis.
Standardized trend, RSI, and participation factors.
Regime weights, range inversion, missing-volume renormalization, conflict attenuation, exact contribution totals, and confirmed alerts.
How It Works
EMA spread and fast-EMA change are normalized by ATR, blended 65/35, and clipped to -1 through +1. RSI is centered at 50, divided by 25, and clipped. Volume multiplies close location inside the bar by relative volume capped at 2.5 times baseline, then smooths it. If fewer than 80% of volume-window bars are usable, volume is omitted.
Trend strength is absolute normalized EMA spread. Path efficiency divides net movement by total one-bar movement. ATR relative to baseline measures displacement. VOLATILE has priority until its lower hold level clears. Otherwise, strong separation and efficiency enter TREND, weak evidence enters RANGE, and unresolved evidence is TRANSITION.
Trend/momentum/volume weights are 55/30/15 in TREND, 15/60/25 in RANGE, 40/35/25 in VOLATILE, and 35/40/25 in TRANSITION. RANGE reverses only RSI. Missing volume removes its weight and renormalizes the others. Agreement divides absolute net contribution by total absolute contribution and sets a 0.55-to-1 gate; VOLATILE adds an ATR penalty. Gated components sum to the score. Warm-up or invalid threshold and EMA ordering blocks output with a diagnostic.
How Multiple Indicators Work Together
Trend estimates structure, momentum locates bounded pressure, and volume tests participation plus bar acceptance. The regime interprets them before combination. Without range inversion, extension becomes a continuation vote; without trend, brief momentum can dominate; without volume, weights must be renormalized. Agreement converts remaining conflict into lower magnitude rather than hiding it.
Trading Ideas and Insights
Use the score as context, not an order. A confirmed threshold cross during TREND identifies aligned conditions. In RANGE, check whether trend or volume opposes inverted momentum before considering a fade. In VOLATILE, a compressed gate shows ATR displacement discounting the raw sum. A strong component beside a modest total indicates conflict.
Unique Aspects
The contribution is the sequence of classification, interpretation change, weighting, and attenuation. RANGE reverses momentum while other factors can veto it; hysteresis separates trend entry from persistence; missing volume is removed; and agreement scales every component so the ledger equals the score. The halo shows magnitude, the background shows regime, and the table exposes construction.
How to Use
Start with defaults and compare the regime label with visible path behavior. Wait for warm-up. Keep the ledger visible to see whether structure, oscillator pressure, or participation drives direction. Use confirmed alerts when closing-state transitions matter. Contribution lines are diagnostic; the halo and background form the primary view. Omitted volume means a disclosed two-factor score.
Customization
EMA lengths and slope lookback control structural response; RSI length controls momentum sensitivity. Volume baseline and smoothing trade speed for stability. Regime length changes path efficiency and the ATR baseline. Entry thresholds must exceed hold thresholds. Raising the score threshold reduces alert frequency but does not establish better forecasting. Visual switches change display only.
Assumptions and Limitations
The script uses chart OHLC and reported volume. Exchange, tick, and absent volume differ; close-location volume is only a proxy. EMA, ATR, RSI, and rolling baselines lag. RANGE can fade a breakout, hysteresis can delay exits, and attenuation can suppress an early shock.
Realtime factors, regime, colors, and score can change before close; alerts require confirmation. No request calls, future data, pivots, or negative offsets are used. The script does not model liquidity, news, sizing, entries, stops, or exits. Thresholds do not establish expected return. Sparse bars and unreliable volume can distort evidence.
Conclusion
This replaces a fixed sum with an inspectable state process. The score and ledger show weights, conflict attenuation, and missing-data effects. Keep separate risk and execution rules.
.
Indicador

Volume Surge Radar - 2x/4x/8x/16x# Volume Surge Radar — 2x / 4x / 8x / 16x
The goal is simple: don't just find unusual volume—find when unusual volume keeps coming back.
## Overview
**Volume Surge Radar** is designed to identify unusual and **repeated volume activity**, not just isolated volume spikes.
The indicator compares each bar's volume against the **average volume of the previous trading week** and classifies unusual activity into four customizable tiers:
**2x → 4x → 8x → 16x**
It then tracks how often these volume surges occur within a configurable rolling window and combines that information with price behavior to provide a **RISING, FALLING, MIXED, or QUIET bias**.
The idea is simple:
**One volume spike may be noise. Repeated volume surges can tell a much more interesting story.**
---
## Key Features
### 🔹 Relative Volume Multiples
Every bar's volume is compared with its 1-week average volume.
For example:
* **2x** = Volume is at least 2 times the weekly average
* **4x** = Volume is at least 4 times the weekly average
* **8x** = Volume is at least 8 times the weekly average
* **16x** = Volume is at least 16 times the weekly average
The tiers are cumulative. For example, a **9x volume bar qualifies as a 2x, 4x and 8x event**.
---
### 🔹 Dynamic 1-Week Baseline
The indicator can automatically calculate the appropriate number of bars representing approximately one trading week based on the chart timeframe.
For example, the baseline can adapt differently when viewing:
* Daily charts
* Hourly charts
* 15-minute charts
* 5-minute charts
Session minutes and trading days per week are configurable, making the indicator adaptable to different markets.
You can also disable automatic calculation and manually specify the baseline.
---
## 🔹 Repeat Volume Detection
This is one of the main features of Volume Surge Radar.
Instead of only asking:
**"Is volume unusually high right now?"**
the indicator also asks:
**"How many times has unusually high volume appeared recently?"**
For each tier, the dashboard counts how many bars inside the configured rolling window reached:
**2x / 4x / 8x / 16x volume**
This can help distinguish an isolated spike from repeated participation.
For example:
**2x volume once**
may simply represent a single event.
But:
**2x+ volume 4 times within 20 bars**
may deserve significantly more attention.
---
# Understanding the Dashboard
The dashboard provides a compact view of current and recent volume activity.
### NOW
Shows whether the current bar has reached each volume tier.
### Hit Count
Shows how many times each volume threshold has been reached within the configured rolling window.
### Ratio
Displays the exact current volume multiple.
For example:
**3.7x**
means the current bar's volume is approximately **3.7 times the calculated 1-week average volume**.
### Price Change
Displays the percentage price change over the same rolling window used for volume analysis.
### Up / Down Surge Count
Shows how many qualifying high-volume bars closed higher versus lower.
For example:
**5↑ 2↓**
means five qualifying surge bars were positive candles and two were negative candles.
---
# Volume Bias
Volume Surge Radar combines two pieces of information:
1. **Price change over the rolling window**
2. **Whether qualifying volume surges occurred more frequently on up or down bars**
The indicator then produces one of several possible readings.
### 🟢 RISING
Price direction and volume-surge direction both support a bullish interpretation.
Repeated high-volume activity is occurring alongside positive price behavior.
### 🟢 RISING?
Only one of the two measurements supports the bullish interpretation.
Consider this an early or weaker signal rather than confirmation.
### 🔴 FALLING
Price direction and volume-surge direction both support a bearish interpretation.
Repeated high-volume activity is occurring alongside negative price behavior.
### 🔴 FALLING?
Only one measurement supports the bearish interpretation.
Additional confirmation may be useful.
### ⚪ MIXED
Price movement and volume-surge direction disagree.
This may indicate conflicting participation, consolidation, absorption, or a transition period.
### ⚪ QUIET
Not enough qualifying volume events have occurred to establish a meaningful bias.
---
# How I Use It
The indicator is particularly useful as a **confirmation and discovery tool** rather than as a standalone buy/sell signal.
### Example 1 — Breakout Confirmation
A stock breaks above an important resistance level.
Instead of looking only at whether the breakout candle has high volume, Volume Surge Radar can show whether **multiple elevated-volume events have appeared around the breakout**.
Repeated 2x or 4x volume combined with a **RISING** bias can provide additional evidence of participation behind the move.
### Example 2 — Finding Unusual Accumulation
Price may initially move only modestly while several unusually high-volume bars appear within a relatively short period.
For example:
**4 separate 2x+ volume events within 20 bars**
can be more interesting than one isolated 4x spike.
The indicator helps make these repeated events easier to identify.
### Example 3 — Distribution / Weakness
Suppose a stock remains near its highs, but repeated high-volume bars increasingly close down.
The dashboard may begin showing more:
**↓ volume surges**
while the bias moves toward **FALLING?** or **FALLING**.
That divergence between price location and volume behavior may deserve additional investigation.
### Example 4 — Extreme Volume Events
An **8x or 16x** volume bar represents an unusually large departure from the recent baseline.
These events can occur around:
* Earnings
* News
* Breakouts
* Gap moves
* Institutional activity
* Capitulation
* Major reversals
The indicator highlights these extreme-volume bars so they can be investigated quickly.
---
# Alerts
Volume Surge Radar includes several built-in alert conditions.
### Single Volume Surge Alerts
Alerts are available when volume reaches:
**2x / 4x / 8x / 16x**
These are useful when monitoring individual extreme-volume events.
### Repeated Volume Alerts
You can also receive alerts when a particular volume tier occurs repeatedly within the rolling window.
For example:
**2x volume reached 4 times within the last 20 bars**
This allows you to detect persistent unusual-volume activity without constantly watching the chart.
### Bias Alerts
Alerts are also available when the volume/price bias changes to:
**RISING**
or
**FALLING**
### Custom Repeat Alert
A configurable alert allows you to choose:
**Volume Tier + Required Hits + Direction**
For example:
**4x Volume + 3 Hits + Rising Bias**
This makes it possible to create alerts around the specific type of volume behavior you want to monitor.
---
# Suggested Workflow
I generally recommend using Volume Surge Radar alongside market structure rather than interpreting volume in isolation.
Look for repeated volume activity around:
* Support and resistance
* Breakouts and breakdowns
* Consolidation ranges
* Moving averages
* Previous highs/lows
* Gap areas
* Earnings or news events
The indicator answers:
**"Is unusual volume appearing repeatedly, and what is price doing while that volume appears?"**
The trader still determines **why that activity matters within the broader chart structure.**
---
# Important Interpretation
High volume is **not automatically bullish**.
A 4x, 8x or even 16x volume event simply tells us that market participation is unusually high compared with the recent baseline.
That activity could represent:
**Accumulation, distribution, breakout participation, profit-taking, capitulation, news-driven trading, or other market activity.**
For this reason, volume should always be interpreted together with **price action and market structure**.
---
# Limitations
Volume Surge Radar is an analytical tool and should not be treated as an automatic trading system.
The RISING/FALLING bias is based on price movement and the direction of qualifying volume bars. It does **not** directly identify institutional buying or selling.
Extremely high volume can also occur because of earnings, news, index rebalancing or other one-time events.
Different assets have different volume characteristics, so the default thresholds and rolling-window settings may need adjustment depending on the instrument and timeframe.
---
## Final Thought
Traditional volume indicators tell you:
**"Volume is high."**
Volume Surge Radar goes one step further:
**"How high is it, how often has it happened recently, and what has price been doing while those volume surges occurred?"**
That is the core idea behind **Volume Surge Radar**.
The goal is simple: don't just find unusual volume—find when unusual volume keeps coming back.
Indicador

Contested Volume Bubbles█ OVERVIEW
Contested Volume Bubbles marks bars where both sides of the trade committed unusually hard, drawing a bubble at the price where the fight actually happened. It measures contested volume — the volume committed by whichever side lost the bar.
In practice it is used to find areas of interest. Bubbles cluster at prices where the two sides repeatedly disagreed, and those levels often matter again on a return. A large bubble late in an extended move reads differently: a push meeting real opposition rather than clean continuation, which is the shape exhaustion usually takes.
█ CONCEPTS
Contested volume
For each bar, contested volume is the smaller of the two sides:
contested = min(buy volume, sell volume)
Heavy volume that resolves cleanly in one direction gives you a low number. The same volume with both sides pushing and neither finishing ahead gives you a high one.
It's also exactly complementary to directional volume:
contested = (total volume − total delta) ÷ 2
Contested volume, total volume and directional volume are three views of the same thing. You can trigger on one and size the bubble by another, which is where most of the flexibility comes from.
Lower timeframe sampling
You can't get any of this off a chart bar. A candle that closes mid-range looks balanced. The activity underneath it may have been not have been: heavy pushes both ways that happened to cancel by the close.
So every candle gets broken into as many as twenty lower-timeframe samples and measured piece by piece. The useful part is placement. The bubble lands on the section of the candle that carried the fight, so it sits at a price that actually traded instead of an average of the bar.
█ TIME OF DAY NORMALIZATION
Normally, volume is heavy at the open, declines through the morning, flat around midday, building into the close. Anything that compares a bar to the bars right behind it will be inherently flawed since volume activity shifts throughout the session.
Time Of Day normalization gets rid of this issue. Instead of comparing a bar to whatever came before it, it compares the bar to what that clock slot USUALLY looks like. This minute against this minute, from previous sessions.
Session level
Time Of Day normalization can also account for how busy today is. Turn the setting down and a bubble means the bar was unusual for the time of day. Turn it up and the bar has to be unusual for the time of day and for today's own level.
There's a Standard mode as well, which ranks each bar against the bars right behind it. It needs no history and works on any chart type, and it carries the intraday bias described above.
█ WHAT EACH BUBBLE TELLS YOU
Three things drive each bubble:
• Whether it appears — If it appears, it says the bar's level of contested volume was unusual based on your selected percentile rank.
• Size — how big the bar's magnitude source is compared to the last 100 bars. By default, its Total Delta Volume. Other options are below.
Magnitude sources
• Total delta volume — Total cumulative volume delta.
• Contested volume — Total contested volume
• Total volume — Simply how much traded.
• Net delta — how directional the bar was end to end, ignoring churn that reversed inside it.
Hover any bubble and the tooltip gives you all four, the trigger rank, and in Time Of Day mode both the slot's normal level and how today is running against it.
█ NOTES
• Time Of Day needs a few sessions of each clock slot before it prints anything, so a chart you just loaded starts empty at the left edge. It falls back to Standard on daily and above and on non-time-based charts.
• Intrabar precision depends on lower-timeframe data, which may vary by symbol and by account plan. Without lower-timeframe data, the indicator will still work, but with much less precision.
• Three alerts are available: any bubble, bubbles on a positive net delta bar, bubbles on a negative one. All initiate on bar close. Indicador

Structure Participation Matrix [MQLSoftware]OVERVIEW
Structure Participation Matrix turns confirmed structure breaks into auditable records. It shows price-travel and chart-feed participation context, then compares endpoints across frozen score buckets. Each record has four readings, a score, and one delayed observation. It is research, not entries, stops, targets, sizing, execution, or forecasts.
Its distinct contribution is the complete frozen event ledger: strict delayed pivots, four disclosed measurements fixed at the break close, explicit UNSCORED handling, and one outcome check aggregated by frozen bucket. It links structure, participation, and later observation rather than merely combining standard indicators.
CONCEPTS
Strict symmetric pivots require a unique extreme on both sides; ties are rejected. A pivot becomes eligible only after its full right-side delay. A break requires a confirmed close beyond the armed level plus the ATR buffer; a wick alone is not an event.
Four 0-100 components freeze at that close. PATH measures displacement against the leg's total path. CLOSE averages directional close location over its final bars. REL VOL compares average leg volume with a rolling median. BALANCE weights volume by close location. The fixed score is 30% EFF/PATH, 25% CLOSE, 25% RVOL/REL VOL, and 20% BAL/BALANCE, normalized once for displays, buckets, and alerts.
RVOL uses reported or tick volume; BAL is an OHLCV proxy. They are not bid/ask delta, order flow, or a footprint; neither proves participant identity or predicts future behavior. Missing leg volume or bounded history makes an event UNSCORED and excludes it from bucket statistics.
After exactly N confirmed bars, the close is checked once. HELD N means the endpoint is beyond the broken level; FAILED N means it is not. HELD does not mean price stayed beyond the level throughout. The result is fixed.
FEATURES
Confirmed BREAK UP and BREAK DOWN events
Latest-event PATH, CLOSE, VOL, BAL rail
LOW, MODERATE, HIGH, and VERY HIGH score bands
HELD N or FAILED N endpoint checks
Sample-aware count and held-at-N rate by bucket
Break, direction, score-60+, and outcome alerts
HOW TO USE
Start with defaults. Higher Strict Swing Strength gives fewer pivots and a longer delay. Break Buffer sets the required closing distance in ATR units. Maximum Measured Leg Bars bounds history; an older leg remains a visible UNSCORED break.
Read the latest label first. In the rail, PATH describes travel efficiency; CLOSE, final-bar commitment; VOL, relative chart activity versus baseline; and BAL, a directional OHLCV proxy. The score summarizes a frozen event, not an instruction or probability.
The newest event keeps its expanded label and rail. Older events become compact labels; Historical Detailed Rails restores detail. Visual switches and retention affect drawings only, not calculations, counts, or alerts.
The matrix uses events recalculated from the history currently loaded on the chart. Counts and rates change with symbol, timeframe, inputs, or the history boundary. Small buckets remain collecting. HELD N rates are historical endpoint observations, not future estimates.
CONCLUSION
The result is an inspectable break record with transparent measurements, compact history, one timed outcome, and visible data limits. Indicador

Intraday Relative Volume+Intraday Relative Volume+
This indicator is intended to measure whether an individual intraday volume bar is unusually active for its specific time of day.
It is designed as the intraday companion to Daily Relative Volume+.
Same-Time Relative Volume
Rather than comparing every intraday bar with a generic rolling volume baseline, the indicator evaluates each bar against historical activity from the same point in the trading session.
This helps account for the fact that normal volume can differ significantly between the open, midday, and the close.
The current session is kept separate from its historical benchmark, and available historical observations are used when full history is not present.
Why Time-of-Day Context Matters
Intraday volume naturally follows a strong time-of-day pattern.
A generic rolling comparison can therefore make normal opening activity look unusually high or normal midday activity look unusually low.
Intraday RVOL+ is designed to reduce that distortion by comparing each bar with more relevant historical context.
The methodology also preserves time alignment across irregular sessions, including missing bars, trading halts, and shortened trading days.
Developing Bars
A live bar is evaluated using the volume it has accumulated at that point in time, so its relative-volume classification can change as the bar develops.
Average Volume MA
The indicator also includes a conventional rolling Average Volume MA.
This is independent of the same-time RVOL methodology and provides a familiar view of recent chart-volume activity.
The MA can be shown or hidden, and its current value can be displayed on the volume scale.
Volume Coloring
When Color Bars Based On Previous Close is enabled, direction is based on the current close versus the previous close.
When disabled, direction is based on the current close versus the current bar's open.
Volume-bar classification is driven by the relative-volume methodology, not by the conventional Average Volume MA.
Sessions
The indicator follows the chart's displayed session data.
On a regular-hours chart, regular-session bars are analyzed.
With Extended Hours enabled, available premarket and postmarket bars can also participate.
Usage and Limitations
Designed for minute-based intraday charts.
Second-based and tick charts are not supported.
Requires a standard time-based chart.
Synthetic chart types such as Heikin Ashi, Renko, Line Break, Kagi, and Point & Figure are not supported.
Relative Volume Length is limited to 68 sessions.
The conventional Average Volume MA is not subject to that RVOL lookback limit.
Methodology
Traditional intraday RVOL can be distorted when it compares volume from very different parts of the trading session.
Intraday RVOL+ improves on this by adding time-of-day context, making the relative-volume signal more appropriate for intraday analysis while retaining a conventional Volume MA as a separate reference. Indicador

Daily Relative Volume+Daily Relative Volume+
This indicator is designed to show how active the current session is relative to recent history and whether volume is developing at an unusually strong or weak pace.
It is intended specifically for the 1D chart and focuses on regular-session volume.
Relative Volume
RVOL provides a straightforward view of how current session volume compares with recent completed sessions.
The current developing session is kept separate from the historical reference so the comparison remains anchored to completed trading days.
RVOL Pace
RVOL Pace adds time-of-day context to traditional daily RVOL.
Instead of treating an unfinished trading session as directly comparable with completed days, it evaluates how current activity is progressing relative to the stock's own historical intraday volume behavior.
The live RVOL Pace calculation begins once one minute of regular-session data is available.
This is intended to make live daily RVOL more useful earlier in the session, when a simple comparison with completed daily volume can otherwise be misleading.
After the session is complete, RVOL Pace converges with realized RVOL.
Average Volume and Dollar Volume
The indicator also includes:
A conventional daily Average Volume MA.
Average Dollar Volume for a broader view of typical trading liquidity.
These use a separate Average Volume Length setting.
The Average Volume MA can be shown or hidden independently.
Volume Coloring
When Color Bars Based On Previous Close is enabled, price direction is based on the current close versus the previous close.
When disabled, direction is based on the current close versus the current bar's open.
Live-session coloring incorporates RVOL Pace, while completed sessions reflect realized RVOL.
Dashboard
The configurable table can display:
RVOL
RVOL Pace
Average Volume
Average Dollar Volume
Usage and Limitations
Designed only for the 1D timeframe.
RVOL-related calculations focus on regular-session activity.
RVOL Pace is a historical volume-based estimate, not a prediction of price direction.
News, catalysts, and unusually event-driven sessions can cause final volume to differ substantially from the pace reading.
Methodology
Traditional daily RVOL is useful, but it can be difficult to interpret while the trading day is still developing.
Daily RVOL+ improves on this by adding a time-aware view of current volume progression, giving more context to whether today's activity is merely high so far or is developing into an unusually active session. Indicador

Volume + RVOL + Directional Delta [Clean]# Volume + RVOL + Directional Delta
## What this is
A volume pane with three layers: raw volume colored by relative volume, a
signed Directional Delta histogram, and a dashboard that reports **how each
number was actually produced**.
The third layer is the point. Relative volume and volume delta both depend on
data that is not always available, and most implementations substitute a
different measurement when the real one is missing — without saying so. This
indicator computes the same things everyone else computes, then tells you when
what you are looking at is not what the label claims.
Every fallback in the script is visible in the dashboard. There are no silent
substitutions.
---
## The problem it addresses
Two silent substitutions happen constantly in volume tooling.
**1. Time-of-day RVOL that isn't.** Comparing a bar to prior bars at the same
clock time is the right way to do intraday RVOL — 9:30 volume and 2:00 volume
are not the same population. But it only works if session bars land on
consistent clock times. On a 65-minute regular-hours chart there are six bars
per session and the opens repeat cleanly. Turn on extended hours and the
session runs about 14.8 bars, the opens drift, and the same-time search returns
almost nothing. Most scripts fall back to a rolling average at that point and
keep displaying the number as though nothing changed.
**2. Volume delta that is really just bar direction.** Estimating delta
requires summing signed intrabar volume from a lower timeframe. TradingView's
intrabar budget is finite — at 65m/1m that is 65 intrabars per chart bar,
covering roughly a year of history before `request.security_lower_tf()` starts
returning empty arrays. The usual fallback is a chart-bar proxy: positive if
the bar closed up, negative if it closed down. That proxy can only ever return
exactly ±volume, i.e. ±100% delta. It is not a noisier version of intrabar
delta. It is a different measurement with a different range, and a single proxy
bar contributes the largest value any bar can contribute.
Both substitutions are reasonable as fallbacks. Neither is acceptable as a
silent one.
---
## Relative volume
**Baseline statistic.** Median by default rather than mean. The mean is dragged
upward by exactly the news-driven spikes RVOL exists to detect, which makes a
fixed threshold like 2.0x mean different things on different tickers and in
different regimes. The median keeps the threshold comparable across names.
**Time-of-day mode** walks backward collecting prior bars whose open lands on
the same hour and minute as the current bar, then takes the median of those.
The setting is a **target sample count, not a search window**. This matters
more than it sounds. A search-window setting produces a completely different
statistical baseline on every timeframe — 120 bars finds about 20 samples on
65m, 12 on 39m, and 4 on 15m. Asking for 20 comparable sessions instead means
20 sessions wherever they are reachable. A separate maximum search distance
bounds how far the scan may walk to find them.
Sizing guidance, on a 390-minute regular-hours session:
Chart TF Bars/session Search distance for 20 samples
10m 39 ~780
15m 26 ~520
39m 10 ~200
65m 6 ~120
78m 5 ~100
130m 3 ~60
195m 2 ~40
The default 1000-bar ceiling reaches 20 samples down through 10m. Some
combinations are simply unreachable — 20 sessions on a 1-minute chart would
need 7800 bars — and those degrade to the rolling baseline and say so.
**Attainment is a three-state result**, because once the setting means "20
sessions", clearing a bare minimum of 10 is not the same as meeting the
request:
MODE TOD target met — the baseline you configured
MODE TOD* minimum met, target missed — usable, but not what you asked
MODE ROLL* minimum missed — fell back to rolling entirely
The middle state keeps a useful 15-sample baseline rather than discarding it,
while refusing to report it as though 20 sessions had been achieved.
**Coloring.** Gray below the high threshold, green at high RVOL, gold at
extreme. Thresholds are configurable.
---
## Bar completion, and why nothing is projected
RVOL divides a **partial** current bar by a median of **completed** bars. It
therefore reads low at the start of a bar and climbs throughout. A 0.4x forty
minutes into a 65-minute bar is not the same statement as a 0.4x at the close.
This is deliberately not projected to a full-bar estimate. Intraday volume is
U-shaped, so scaling linearly by elapsed time overstates near the open and
understates into the close — and an extrapolated figure displayed to two
decimals invites more trust than it has earned. The honest fix is a baseline
built from the same elapsed *fraction* of prior same-time-of-day bars, which
requires intrabar history for every baseline bar and is a substantially larger
build.
So the indicator reports completion instead and lets you discount. The `BAR%`
cell turns amber below 95%, which is precisely when the RVOL cell beside it is
understated.
One caveat: this is wall-clock elapsed against nominal bar duration. A bar
truncated by a session boundary or a holiday early close reads below 100% even
at its close. In time-of-day mode such bars are compared against other bars at
the same clock time, so RVOL itself stays meaningful — only the completion
figure misreports.
---
## Directional Delta
Each lower-timeframe bar's entire volume is signed by that bar's own candle
direction, with dojis resolved against the prior close, and the signed values
are summed across the chart bar.
**It is called Directional Delta because that is what it is.** It is not
market-buy volume minus market-sell volume. No lower-timeframe reconstruction
can see bid/ask trade classification; it can only sign small bars by their
direction. That is genuinely useful information about intrabar pressure, and it
is not order flow, and the name should not imply otherwise.
**Cumulative Directional Delta uses real intrabar bars only.** Bars that fell
back to the proxy are excluded from the total rather than included and flagged.
This is worth explaining, because it drives the display. Proxy bars are not
scattered randomly through the window — the intrabar budget runs out going
*backward*, so they form the oldest contiguous block. Filtering therefore
produces a **shorter, more recent window**, not a cleaned full-length one. The
column header reports the real bar count for that reason:
57B DΔ +8.7M
57B DΔ% +12.6%
VALID 57/60
You asked for 60 bars and you are looking at a clean measurement over 57. With
zero valid bars both cells read `n/a` rather than a confident `+0`.
Cumulative delta % is total delta divided by total volume across those same
valid bars — not the average of per-bar percentages.
The lookback is left in bars rather than normalized to sessions, deliberately.
It means different amounts of market time on different charts — 60 bars is ten
sessions on 65m but 2.3 sessions on 15m — and the tooltip says so. Which span
you want is a judgment, not something the script should make for you.
---
## Dashboard reference
RVOL current bar volume / active baseline
BAR% bar completion; amber below 95%, when RVOL is understated
MODE TOD / TOD* / ROLL / ROLL*, plus "med" or "avg"
SAMP 20+ (target met with margin) / 20 (met exactly) / 15/20 (short)
BAR DΔ current bar Directional Delta
BAR DΔ% as a share of bar volume
nB DΔ cumulative over valid bars; header states how many
nB DΔ% cumulative delta / cumulative volume, same bars
VALID valid bars / requested bars
Δ TF intrabar timeframe in use, or why there isn't one
The `Δ TF` cell distinguishes four outcomes, because "no intrabar data" has
causes that call for different responses:
1 / 15S intrabar data genuinely in use
Chart* a valid lower timeframe was requested, no data came back
INVALID manual timeframe is not lower than the chart — fix the setting
Chart no lower timeframe exists at all (1-second chart)
`INVALID` exists because entering 65m as the delta timeframe on a 65m chart
used to display a calm white "Chart", identical to the legitimate case. Both
fall through to the proxy; only one is a mistake.
**Color convention.** Amber means one thing throughout: *the number is usable
but is not the measurement you asked for.* Red appears in exactly one place and
means *this setting cannot work as entered*. Keeping those separate is what
makes the pane readable at a glance.
---
## Settings guidance
- **65m regular hours:** defaults work as-is. About 120 bars of search finds
the 20-sample target.
- **15m and 10m:** also fine at the 1000-bar default, but the scan runs much
further. If the script becomes slow, turn off *Compute Time-of-Day Baseline
on History* — historical bar coloring then uses the rolling baseline while
the dashboard uses time-of-day, which is a real inconsistency and is why it
is a visible toggle rather than a silent optimization.
- **Extended-hours charts:** time-of-day will degrade to `ROLL*`. Session bar
opens do not repeat. Either switch to regular hours or accept the rolling
baseline knowingly.
- **Daily and above:** time-of-day is inapplicable and is bypassed.
- **Delta timeframe:** leave on automatic. It steps down correctly including on
1-minute charts. Sub-minute intrabar data requires a higher TradingView plan
tier; on a lower tier the request returns empty and `Δ TF` reports `Chart*`.
- **Below ~15 samples**, the median becomes sensitive to holiday early-close
sessions, whose truncated final bars carry structurally low volume.
---
## Alerts
Six conditions. High RVOL and Extreme RVOL are straightforward.
The two combined alerts — extreme volume with positive or negative Directional
Delta — **require real intrabar data**. On a proxy bar the delta sign is
nothing more than the candle body's direction, so an ungated version would fire
on "heavy volume, bar closed up" while appearing to describe something more.
Two ungated variants are provided separately and named for what they actually
test: *Extreme Volume + Up Bar* and *Extreme Volume + Down Bar*, each stating in
its own message that it does not test Directional Delta.
---
## What this is not
- It does not project or estimate finished bar volume.
- Directional Delta is not bid/ask trade classification and does not claim to be.
- It makes no directional claim, generates no entries, and has no backtest.
- The proxy fallback is not "close enough." It is excluded from cumulative
figures and labeled where it appears, so you can decide whether a number is
usable for what you are doing.
---
## Implementation notes
Both rolling statistics (`ta.sma` and `ta.median`) are evaluated
unconditionally and then selected, rather than being called inside a
conditional branch, which would produce an inconsistent series.
The sample scan probes for one more than the target, then discards it. That is
what makes `20+` truthful: it means a 21st match genuinely existed, not merely
that the loop stopped. A bare `20` means the target was met with no margin left
in the window, which is worth distinguishing.
The scan exits as soon as the target is met, so the search ceiling costs
nothing on timeframes that reach it — 65m stops near bar 126 regardless of the
setting. It is not free where the target is unreachable: the loop then runs the
full distance on every bar, which is what the history toggle is for.
`todActive` reflects what the code actually used, never what was requested. The
dashboard reads that flag rather than the input, which is what prevents MODE
from displaying `TOD` while a rolling baseline is in use.
The compact number formatter uses `"#0"` rather than `"#"` for sub-thousand
values — a bare `"#"` drops the digit on sub-1 values and renders a lone minus
sign.
Open source. Indicador