
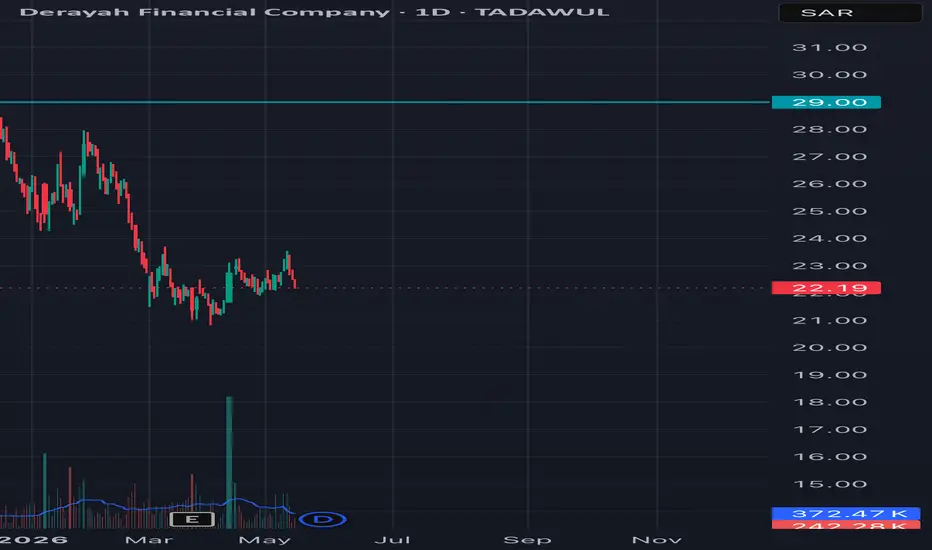
Drayah Financial 💫
Drayah Financial is gradually transforming into a broader digital financial platform with strong fintech expansion potential.
For those who still see it as “just a brokerage company,” the story today is becoming much bigger than that. 👍🏻
## Q1 2026 Results
- Operating income: SAR 228M (+9%)
- Core net profit: SAR 127M (-3%)
- Assets under custody: SAR 35B (+5%)
- Total accounts: 637K (+3%)
- Revenue growth accelerated to 43.3% vs. 37.2% previously
The company still relies heavily on:
- Trading activity
- Retail speculation
- Market commissions
However, management is clearly expanding into:
- Asset management
- Subscription-based products
- Investment solutions
This explains the strong revenue acceleration to 43.3%. 👍🏻
## Segment Breakdown
- Brokerage revenue: SAR 133M
- Special commissions income surged +54% to SAR 65M
- Asset management revenue declined -17%
Operating expenses increased by +29% mainly due to:
- Technology investments
- Marketing expansion
- D360 Bank spending 🫣
Yes, higher expenses are currently pressuring net profit margins, but these can also be viewed as future growth investments.
## D360 Bank 🤬
This project could completely transform the company long term, but success depends on:
- Serious execution
- Strong management
- Long-term strategic vision
If management succeeds, Drayah could eventually evolve into something similar to Interactive Brokers or Robinhood — but with a Saudi fintech ecosystem.
## Valuation
- Closing price: SAR 22.60
- Shares outstanding: 242.67M
- Free float: 31.54% 👍🏻
- Market cap: SAR 5.48B
### Expected Annual Profit
Quarterly profit:
SAR 127M × 4 = SAR 508M
### Forward EPS
508M / 242.67M = SAR 2.09
### Forward P/E
22.60 / 2.09 = 10.8x
## Dividend Analysis
The company announced a quarterly dividend of SAR 0.33.
Annualized dividend:
0.33 × 4 = SAR 1.32
### Dividend Yield
1.32 / 22.60 = 5.75%
### Payout Ratio
80.7M / 127M = 63.5%
## Fair Value Estimate
In my opinion, the stock still looks undervalued.
The current P/E of 10.8x does not fully reflect:
- Growth potential
- Fintech expansion
- Strong dividend profile
I believe the company deserves a valuation closer to 14–16x earnings.
Using forward EPS of SAR 2.09:
- 14x P/E → SAR 29.3
- 16x P/E → SAR 33.4
### Fair Value Range:
SAR 29–33 within a one-year horizon 😉
If D360 Bank succeeds, the stock could trade well above SAR 33+.
## Technical View
Technically, I believe the breakout starts above the SAR 23 leve

免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。