
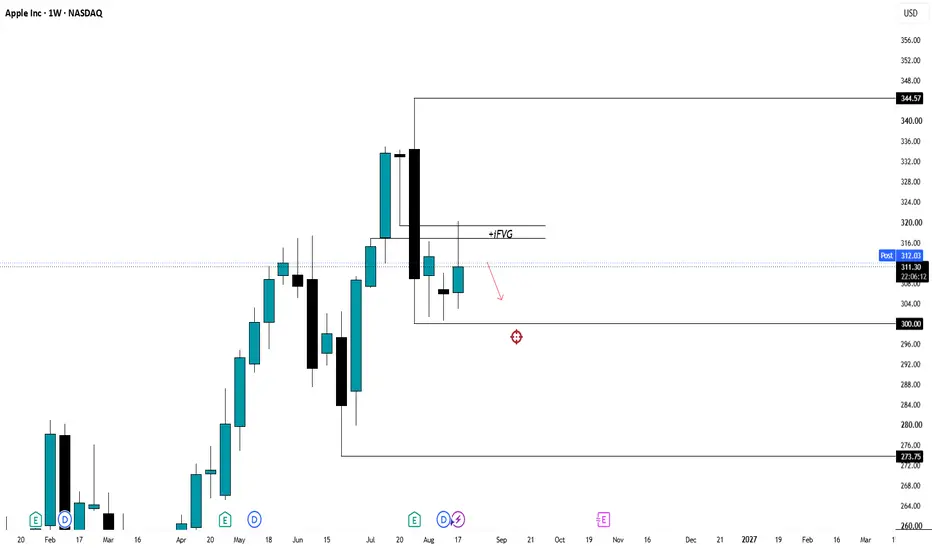
My long-term outlook on Apple is bearish from current valuations, although short-term momentum remains strong.
Apple delivered excellent Q3 results, with revenue growing 16% YoY and iPhone sales reaching record June-quarter levels. However, forward growth is expected to slow, while rising memory costs are beginning to pressure gross margins.
The bigger structural concern is Services. Increasing antitrust regulation in the U.S. and Europe is weakening Apple's control over App Store payments and commissions, putting pressure on one of the company's highest-margin businesses.
Apple also trades around 35x earnings and above a $4T valuation, leaving relatively little room for slower growth or execution problems.
Additional risks include intense competition in China, rising component costs, uncertainty around AI monetization, and the September CEO transition from Tim Cook to John Ternus.
The upcoming iPhone cycle could support the stock in the short term, but from a longer-term perspective I see increasing risk of valuation compression if earnings and Services growth fail to justify Apple's premium multiple.

免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。
免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。