
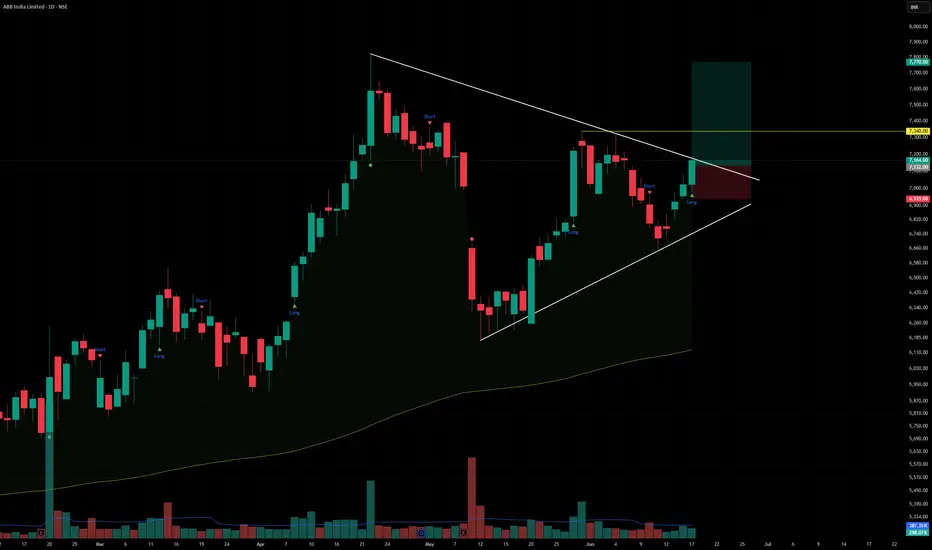
ABB India Ltd. (CMP ₹7,164.00, NSE: ABB)
Prepared by Sucrit Patil | The SmartWay Research Desk | 18 June 2026
A Bengaluru‑based engineering and automation company, incorporated in 1949. ABB India operates across electrification, robotics, industrial automation, and motion solutions, serving power, manufacturing, transport, and infrastructure sectors.
Promoter Holding (Mar 2026): ABB Asea Brown Boveri Ltd. — 75.00% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹12,842 Cr vs ₹11,215 Cr in FY25 (+14.5% YoY). → Good
Net Profit: FY26 PAT ₹1,215 Cr vs ₹1,048 Cr in FY25 (+15.9% YoY). → Good
Operating Margin: FY26 EBITDA ₹2,312 Cr, margin 18.0% vs 17.2% last year (+80 bps). → Good
Equity Capital: Stable, face value ₹2. → Good
Dividend Policy: Dividend ₹25.00/share declared for FY26. → Good
Asset Building: Investments in robotics, EV charging, and smart grid solutions. → Good
Sales: Strong demand from industrial automation and electrification projects. → Good
Expense: Raw material cost pressures (steel, copper) remain. → Neutral/Good
EPS: FY26 EPS ₹72.15 vs ₹62.20 last year (+16%). → Good
Institutional Interest & Ownership Trends (Mar 2026)
Promoter Holding: 75.00% (no pledges)
FII Holding: 8.12%
DII Holding: 10.34%
Retail & Others: 6.54%
Strategic Moves & Innovations
Expansion in EV charging infrastructure and smart grids.
Focus on industrial robotics and automation solutions.
Partnerships with state utilities for electrification projects.
Diversification into renewable energy integration and digital solutions.
Cash Flow & Balance Sheet Strength
Market cap ~₹1,52,800 Cr.
Debt‑to‑equity ratio ~0.18 (low leverage).
Book value per share ₹412.00; P/B ~17.4.
EPS (TTM) ₹72.15; P/E ~99.3.
Risk Factors
High P/E ratio ~99.3, indicating premium valuations.
Dependence on industrial capex cycles.
Exposure to commodity price volatility (steel, copper).
Competition from Siemens India, Schneider Electric, and GE India.
Investor Takeaway
ABB India has delivered robust FY26 performance, supported by electrification, automation, and robotics demand. With strong promoter backing, dividend payouts, and leadership in industrial technology, ABB remains a premium play on India’s industrial automation and electrification growth story. At CMP ₹7,164.00, valuations are expensive (P/E ~99.3, P/B ~17.4), reflecting high growth expectations but also significant risk.

Sucrit.D.Patil
免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。
Sucrit.D.Patil
免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。