
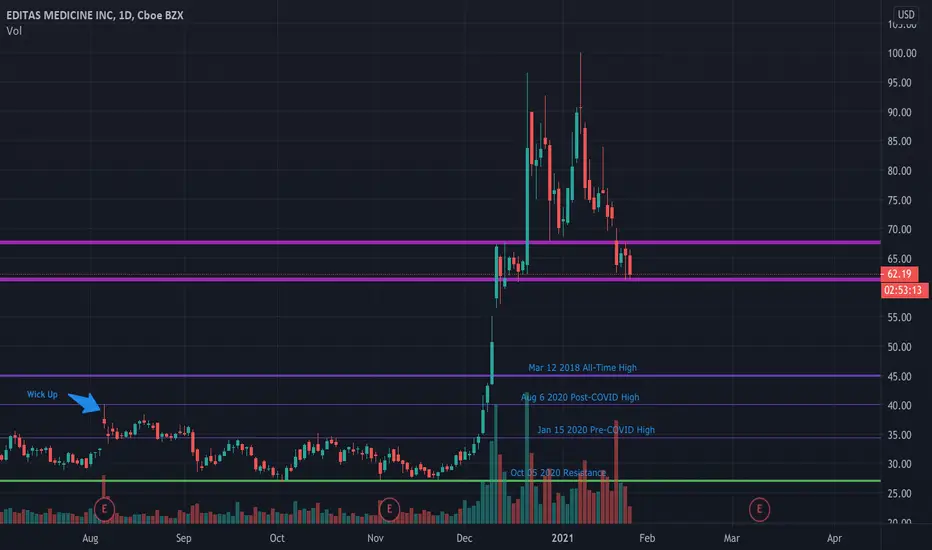
Clearly a lot of value has been lost in the past month. The CSO stepped down and analysts downgraded projected revenue. EDIT has very lucrative candidates in the pipeline treating sickle cell anemia. Long-term, this company will most certainly be profitable, with significant patent protection. This is a short term down draft that is consolidating, for the near term, around a non-speculation, fair price of $63.

免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。