
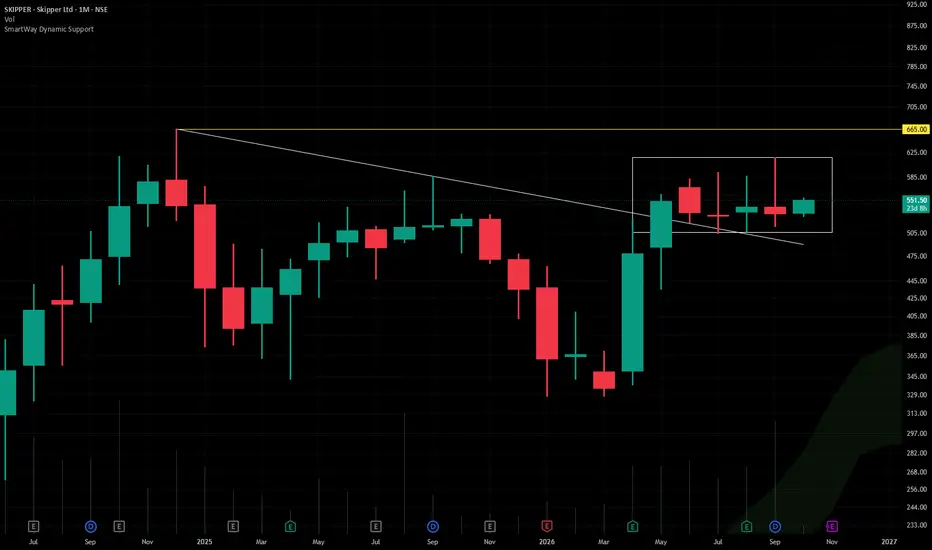
Skipper Ltd. (CMP ₹552.00, NSE: SKIPPER)
The SmartWay Research Desk | 7 October 2026
A Kolkata‑based infrastructure and engineering company, incorporated in 1981. Skipper Ltd. is one of India's leading manufacturers of power transmission towers, telecom towers, railway electrification structures, PVC pipes, and polymer products. The company serves major utilities, infrastructure developers, and government projects across India and exports to multiple countries.
Promoter Holding (Jun 2026): Sharan Family — ~68.1% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹5,242 Cr vs ₹4,512 Cr in FY25 (+16.2% YoY). → Good
Net Profit: FY26 PAT ₹312 Cr vs ₹252 Cr in FY25 (+23.8% YoY). → Good
Operating Margin: FY26 EBITDA ₹612 Cr, margin 11.7% vs 10.8% last year (+90 bps). → Good
Equity Capital: Stable, face value ₹1. → Good
Dividend Policy: Consistent focus on growth while maintaining shareholder returns. → Good
Asset Building: Investments in power transmission, engineering capacity expansion, and polymer business growth. → Good
Sales: Strong demand from power T&D projects, railways, and infrastructure spending. → Good
Expense: Steel price volatility remains a key input cost risk. → Neutral
EPS: FY26 EPS ₹17.25 vs ₹13.90 last year (+24.1%). → Good
Institutional Interest & Ownership Trends (Jun 2026)
Promoter Holding: ~68.1% (no pledges)
FII Holding: ~5.8%
DII Holding: ~10.4%
Retail & Others: ~15.7%
Strategic Moves & Innovations
Expansion of power transmission and distribution infrastructure business.
Focus on railway electrification and EPC opportunities.
Strengthening export presence in Africa, South America, and Asia.
Growth in PVC pipes and polymer products segment.
Cash Flow & Balance Sheet Strength
Market cap ~₹6,200 Cr.
Debt‑to‑equity ratio ~0.55 (moderate leverage).
Book value per share ₹92.00.
P/B ~6.0.
EPS (TTM) ₹17.25.
P/E ~32.0.
Risk Factors
Dependence on government infrastructure and power sector capex.
Exposure to steel and commodity price fluctuations.
Working capital intensity due to large EPC and transmission projects.
Competition from Kalpataru Projects, KEC International, and Techno Electric.
Investor Takeaway
Skipper Ltd. has emerged as a strong beneficiary of India's power transmission, railway electrification, and infrastructure expansion cycle. The company combines a growing engineering business with a stable polymer products segment, providing diversification and earnings support. With strong promoter backing (Sharan Family holding ~68.1%), improving profitability, and a healthy order pipeline, Skipper remains a mid‑cap infrastructure growth story. At CMP ₹552.00, valuations are moderately premium (P/E ~32.0, P/B ~6.0), reflecting expectations of continued growth driven by India's infrastructure and power sector investments.

Sucrit.D.Patil
免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。
Sucrit.D.Patil
免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。