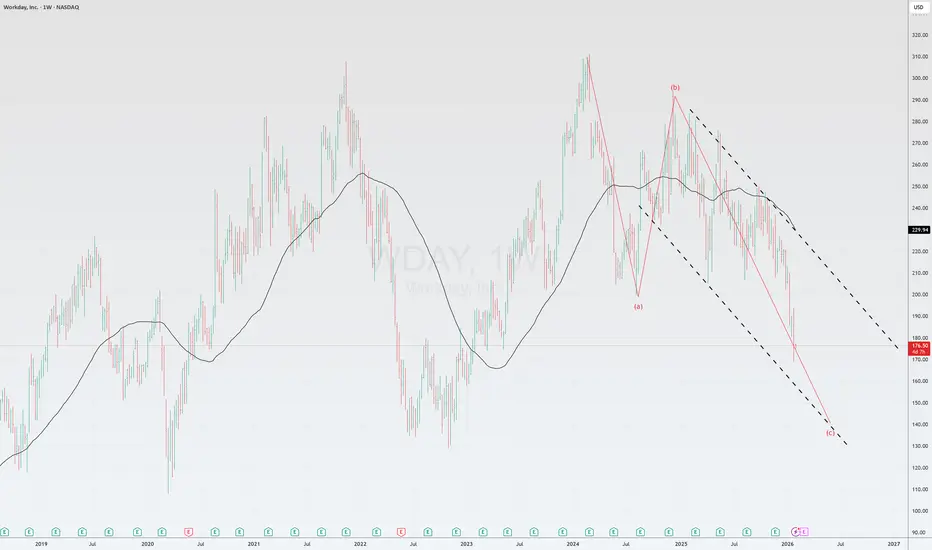
 WDAY
Workday is a leading cloud-based provider of HR and financial management solutions.
Key Strengths:
High switching costs: ERP systems typically have a 5–15 year lifecycle. Workday maintains a 97% customer retention rate and is consistently recognized as a leader in Gartner’s Magic Quadrant.
Strong Gross Revenue Retention (GRR): This highlights the product’s "stickiness" among large enterprise clients.
Healthy Cash Flow
AI Integration: The new Illuminate platform and the acquisition of Sana embed AI directly into enterprise workflows.
Why is the stock under pressure?
M&A-driven growth: Recent gains in cRPO (calculated remaining performance obligations) were partly fueled by acquisitions. Investors are concerned that organic demand for core products may be slowing.
Decelerating growth: The subscription revenue forecast for FY2027 is around 13%. If growth slips toward 10% or lower, the market to compress valuation multiples.
AI fear: There is a growing concern that AI might lead to headcount reductions. Since Workday’s pricing is often seat-based, fewer employees mean fewer licenses.
WDAY remains a high-quality asset. From a technical perspective, the stock in Wave C, with target $140.

免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。
免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。