OPEN-SOURCE SCRIPT
VWAP Mean Reversion Strategy Range Bound Forex RSI Volume
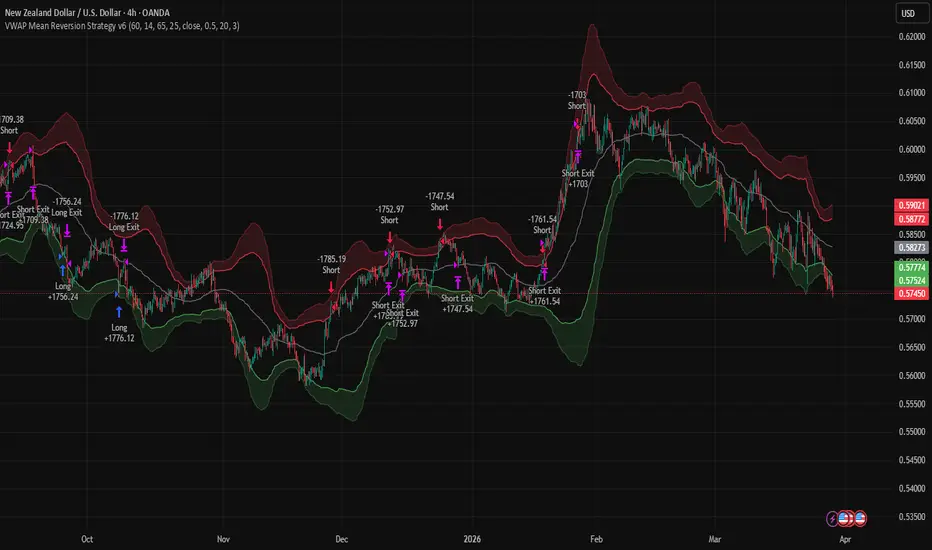
### 🔷 Overview
VWAP Mean Reversion Strategy v6 is a systematic intraday trading model designed specifically for **range-bound forex markets**, where price oscillates around a fair value rather than trending.
The strategy leverages a **custom rolling VWAP (volume-weighted mean)** combined with deviation bands to identify statistically stretched price conditions and execute mean-reversion trades.
---
### ⚙️ Core Logic
This strategy operates on three key principles:
**1. VWAP-Based Mean Reversion**
* Uses a rolling VWAP (not session VWAP) as dynamic equilibrium
* Constructs deviation bands using volume-weighted absolute deviation
* Trades occur when price deviates significantly from fair value
**2. RSI Confirmation Filter**
* Long trades: RSI below oversold threshold
* Short trades: RSI above overbought threshold
* Helps avoid premature entries
**3. Volume Exhaustion Filter**
* Avoids trades during abnormal volume spikes
* Filters out potential breakout conditions (non-mean-reverting environments)
---
### 📊 Entry Conditions
**🔽 Long Setup**
* Price crosses below Lower Band (2σ deviation)
* RSI confirms oversold condition
* No extreme volume spike
**🔼 Short Setup**
* Price crosses above Upper Band (2σ deviation)
* RSI confirms overbought condition
* No extreme volume spike
---
### 🎯 Exit Logic
* **Take Profit:** Return to VWAP (mean reversion target)
* **Stop Loss:** Fixed % risk from entry price
* Designed for **high-probability, small-edge trades**
---
### 💱 Best Use Case (Forex Focus)
This strategy performs best in:
* **Range-bound currency pairs** (e.g., EUR/USD, GBP/USD, USD/JPY)
* **Low to moderate volatility sessions**
* **Non-trending market phases**
Avoid during:
* High-impact news events
* Strong directional trends
* Breakout environments
---
### ⚠️ Strategy Profile
* Type: Mean Reversion
* Market Condition: Sideways / Consolidation
* Frequency: Moderate to High
* Risk: Tight stops, frequent trades
---
### 🧠 Notes
* VWAP length controls sensitivity (shorter = faster signals)
* RSI thresholds can be tightened for higher precision
* Volume filter is critical to avoid false reversals
---
### 📌 Disclaimer
This strategy is for educational and research purposes only.
Not financial advice. Always validate with forward testing and proper risk management.
---
### 🔖 Credits
Concept based on VWAP mean reversion principles and statistical deviation modeling.
Customized into a systematic trading framework for forex markets.
开源脚本
秉承TradingView的精神,该脚本的作者将其开源,以便交易者可以查看和验证其功能。向作者致敬!您可以免费使用该脚本,但请记住,重新发布代码须遵守我们的网站规则。

免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。
开源脚本
秉承TradingView的精神,该脚本的作者将其开源,以便交易者可以查看和验证其功能。向作者致敬!您可以免费使用该脚本,但请记住,重新发布代码须遵守我们的网站规则。
免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。