VIX Term Structure
VIX Term Structure Regime
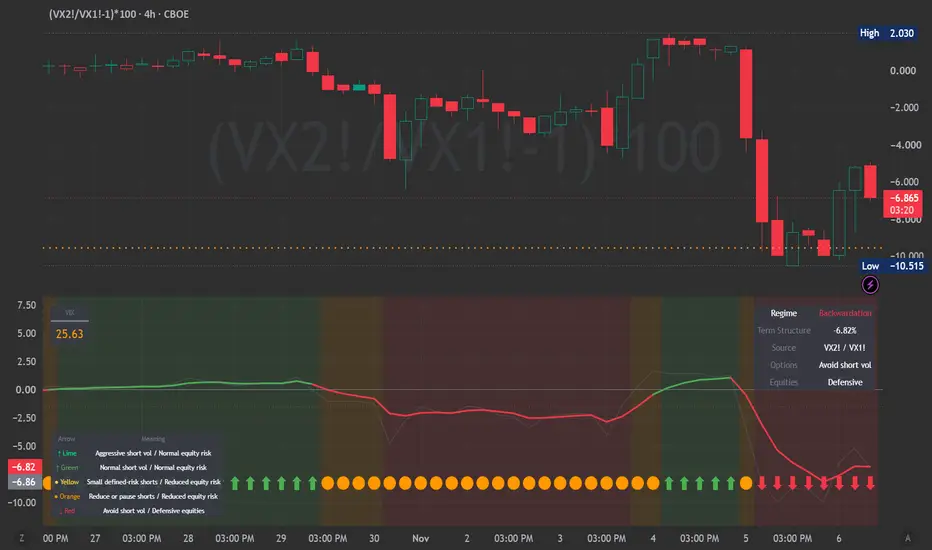
This indicator measures the VIX term structure to help identify the current volatility regime and guide options and equity risk decisions.
It calculates the percentage difference between longer-dated and near-term volatility, then classifies the market as Strong Contango, Mild Contango, Flat, or Backwardation. The result is shown with a clear dashboard, color-coded background, action arrows, and optional VIX level box.
How to use it
- Contango (positive) generally favors short premium strategies and normal equity risk.
- Backwardation (negative) is a warning to reduce or avoid short volatility exposure and tighten equity risk.
- Use the smoothed line and background color as the primary filter. The raw line shows the underlying noise.
- Toggle between VIX / VIX3M (steadier, recommended) and VX2! / VX1! (more reactive).
Formula
When using VIX / VIX3M (default):
(VIX3M / VIX - 1) * 100
When using VX2! / VX1!:
(VX2! / VX1! - 1) * 100
A light EMA is applied to reduce one-bar noise. Positive values = contango. Negative values = backwardation.
Features
- Adjustable dashboard, VIX box, and legend (position + size)
- Action arrows with legend
- Clear scale levels
- Alerts for regime shifts
- Options and equity guidance based on the combined regime
Setup
Add the indicator to any chart (recommended: SPY or QQQ). It pulls VIX, VIX3M, VX1!, and VX2! automatically via request.security(). No special ticker is required.
VIX, Term Structure, Volatility, Contango, Backwardation, Options, Risk Management, VIX Futures, Regime, Short Volatility
This indicator measures the VIX term structure to help identify the current volatility regime and guide options and equity risk decisions.
It calculates the percentage difference between longer-dated and near-term volatility, then classifies the market as Strong Contango, Mild Contango, Flat, or Backwardation. The result is shown with a clear dashboard, color-coded background, action arrows, and optional VIX level box.
How to use it
- Contango (positive) generally favors short premium strategies and normal equity risk.
- Backwardation (negative) is a warning to reduce or avoid short volatility exposure and tighten equity risk.
- Use the smoothed line and background color as the primary filter. The raw line shows the underlying noise.
- Toggle between VIX / VIX3M (steadier, recommended) and VX2! / VX1! (more reactive).
Formula
When using VIX / VIX3M (default):
(VIX3M / VIX - 1) * 100
When using VX2! / VX1!:
(VX2! / VX1! - 1) * 100
A light EMA is applied to reduce one-bar noise. Positive values = contango. Negative values = backwardation.
Features
- Adjustable dashboard, VIX box, and legend (position + size)
- Action arrows with legend
- Clear scale levels
- Alerts for regime shifts
- Options and equity guidance based on the combined regime
Setup
Add the indicator to any chart (recommended: SPY or QQQ). It pulls VIX, VIX3M, VX1!, and VX2! automatically via request.security(). No special ticker is required.
VIX, Term Structure, Volatility, Contango, Backwardation, Options, Risk Management, VIX Futures, Regime, Short Volatility

免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。