OPEN-SOURCE SCRIPT
Quantile Drift Engine [forexobroker]
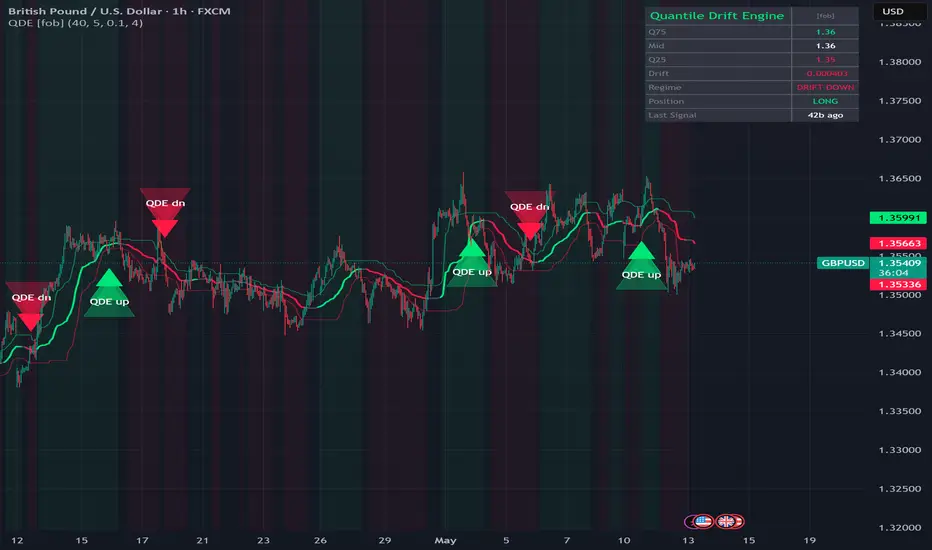
Quantile Drift Engine uses the rolling 25th and 75th percentiles of close as a robust analogue to mean and variance. The midpoint between Q25 and Q75 is the "interquartile median," which drifts directionally and is far less sensitive to spikes than a moving average. The drift, normalised by ATR, provides the regime gate; close cross of the midpoint provides the entry.
🔶 ALGORITHM
1. q25 = ta.percentile_linear_interpolation(close, N, 25); q75 = same at 75.
2. mid = (q25 + q75) / 2; drift = mid - mid[lag].
3. Trending regime when |drift| > k * ATR.
4. Buy entry: trending up AND close crosses mid up.
5. Sell entry: trending down AND close crosses mid down.
🔶 SIGNAL LOGIC
- Buy: trending up AND close crosses mid up AND not already long AND cooldown elapsed AND barstate.isconfirmed.
- Sell: trending down AND close crosses mid down.
- Position-lock state machine.
🔶 INPUTS
- Quantile Window (default 40)
- Drift Lag (default 5 bars)
- Drift Threshold x ATR (default 0.10)
- Cooldown Bars (default 4)
- Visual: dashboard, glow, quantile bands, buy / sell colors
🔶 ALERTS
QDE Buy, QDE Sell, QDE Any Signal, QDE Drift Up, QDE Drift Down, QDE Mid Cross Up, QDE Mid Cross Dn, QDE Outside IQR, QDE Webhook JSON.
🔶 LIMITATIONS
- Percentile estimators need >= ~10 samples to be meaningful; short windows produce step-like quantiles.
- Linear interpolation between samples introduces minor smoothing; raw ranking would be slightly more responsive.
- Drift lag of 5 bars dampens noise but causes slight delay during sharp directional moves.
- IQR midpoint is robust but ignores tail behaviour; for tail-driven instruments pair with a separate volatility filter.
开源脚本
秉承TradingView的精神,该脚本的作者将其开源,以便交易者可以查看和验证其功能。向作者致敬!您可以免费使用该脚本,但请记住,重新发布代码须遵守我们的网站规则。

🔵Gain access to our powerful tools : kestutisbalciunas.com/tradingview/
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。
开源脚本
秉承TradingView的精神,该脚本的作者将其开源,以便交易者可以查看和验证其功能。向作者致敬!您可以免费使用该脚本,但请记住,重新发布代码须遵守我们的网站规则。
🔵Gain access to our powerful tools : kestutisbalciunas.com/tradingview/
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
免责声明
这些信息和出版物并非旨在提供,也不构成TradingView提供或认可的任何形式的财务、投资、交易或其他类型的建议或推荐。请阅读使用条款了解更多信息。