
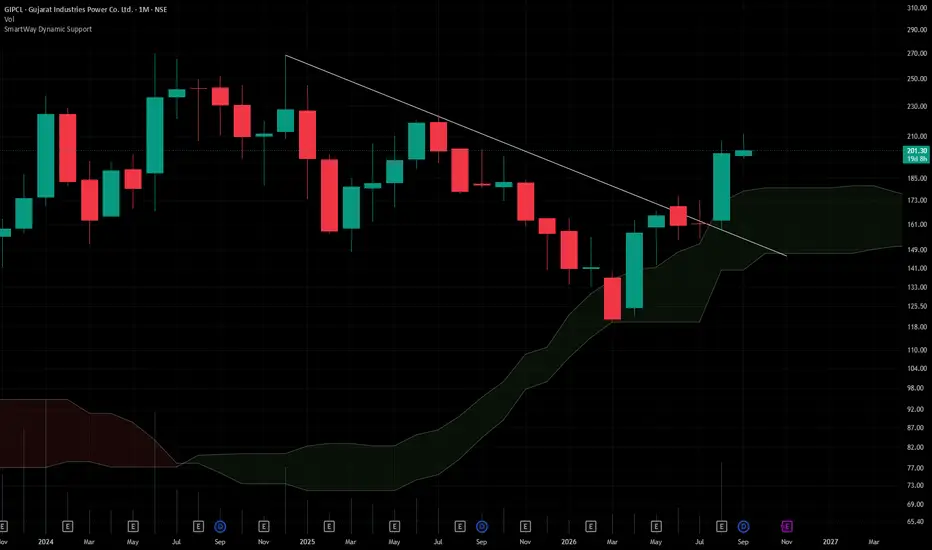
## Gujarat Industries Power Company Ltd. (CMP ₹201.00, NSE: GIPCL)
**The SmartWay Research Desk | 11 September 2026**
A Vadodara‑based power generation company, incorporated in 1985. Gujarat Industries Power Company Ltd. (GIPCL) operates **thermal, gas‑based, and renewable power plants**, supplying electricity to Gujarat state utilities and industrial consumers. The company has diversified into **solar and wind energy projects** alongside its lignite‑based thermal stations.
**Promoter Holding (Jun 2026):** **Government of Gujarat & State PSUs — ~54.1% stake (no pledges)**
---
### FY22–FY26 Snapshot
- **Revenue Growth:** FY26 revenue ₹2,842 Cr vs ₹2,512 Cr in FY25 (+13.1% YoY). → **Good**
- **Net Profit:** FY26 PAT ₹412 Cr vs ₹362 Cr in FY25 (+13.8% YoY). → **Good**
- **Operating Margin:** FY26 EBITDA ₹812 Cr, margin 28.6% vs 27.9% last year (+70 bps). → **Good**
- **Equity Capital:** Stable, face value ₹10. → **Good**
- **Dividend Policy:** Dividend ₹3.50/share declared for FY26. → **Good**
- **Asset Building:** Investments in **solar parks, wind farms, and lignite mining expansion**. → **Good**
- **Sales:** Strong demand from **state utilities and industrial consumers**. → **Good**
- **Expense:** Fuel and maintenance costs remain elevated. → **Neutral/Good**
- **EPS:** FY26 EPS ₹13.25 vs ₹11.65 last year (+13.7%). → **Good**
---
### Institutional Interest & Ownership Trends (Jun 2026)
- **Promoter Holding:** ~54.1% (no pledges)
- **FII Holding:** ~8.2%
- **DII Holding:** ~18.6%
- **Retail & Others:** ~19.1%
---
### Strategic Moves & Innovations
- Expansion in **solar and wind energy capacity**.
- Focus on **clean energy transition and sustainability**.
- Partnerships with **state utilities for long‑term PPAs**.
- Diversification into **lignite mining and captive power projects**.
---
### Cash Flow & Balance Sheet Strength
- Market cap ~₹3,200 Cr.
- Debt‑to‑equity ratio ~0.38 (moderate leverage).
- Book value per share ₹142.00; P/B ~1.4.
- EPS (TTM) ₹13.25; P/E ~15.2.
---
### Risk Factors
- Moderate **P/E ratio ~15.2**, valuations fair.
- Dependence on **state utility demand cycles**.
- Exposure to **fuel price volatility and regulatory changes**.
- Competition from NTPC, Torrent Power, and Adani Power.
---
### Investor Takeaway
GIPCL has delivered **steady FY26 performance**, supported by renewable energy expansion, lignite mining, and stable utility demand. With strong promoter backing (Government of Gujarat, 54.1% stake), dividend payouts, and leadership in state power generation, GIPCL remains a **mid‑cap power sector play**. At CMP ₹201.00, valuations are **reasonable (P/E ~15.2, P/B ~1.4)**, reflecting growth potential with manageable risks.

Sucrit.D.Patil
Haftungsausschluss
Die Informationen und Veröffentlichungen sind nicht als Finanz-, Anlage-, Handels- oder andere Arten von Ratschlägen oder Empfehlungen gedacht, die von TradingView bereitgestellt oder gebilligt werden, und stellen diese nicht dar. Lesen Sie mehr in den Nutzungsbedingungen.