
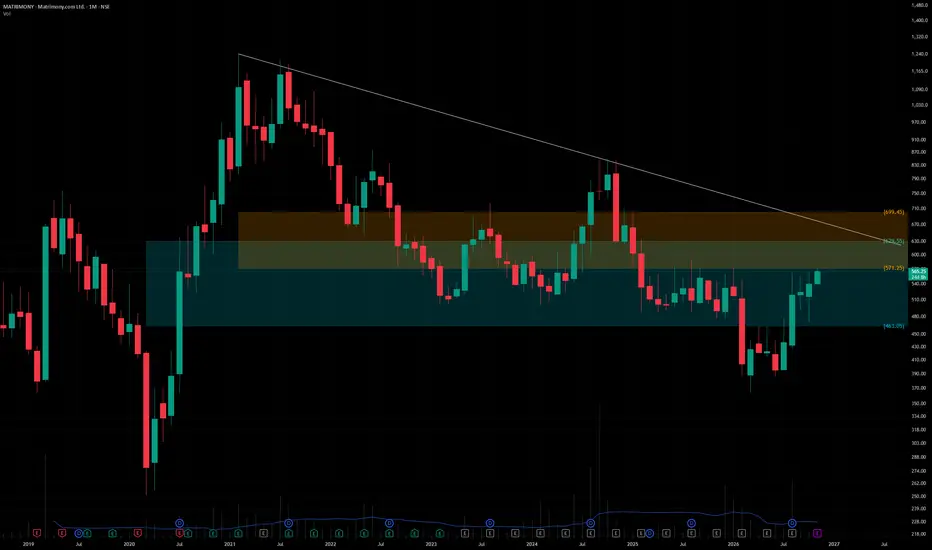
Matrimony.com Ltd. (CMP ₹566.00, NSE: MATRIMONY)
The SmartWay Research Desk | 6 November 2026
A Chennai‑based consumer internet company, incorporated in 2001. Matrimony.com Ltd. is India's leading online matchmaking platform, operating well‑known brands including BharatMatrimony, CommunityMatrimony, EliteMatrimony, and Jodii. The company also has interests in wedding-related services and relationship platforms, serving millions of users across India and overseas markets.
Promoter Holding (Jun 2026): Murugavel Janakiraman & Promoter Group — ~50.1% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹682 Cr vs ₹612 Cr in FY25 (+11.4% YoY). → Good
Net Profit: FY26 PAT ₹92 Cr vs ₹78 Cr in FY25 (+17.9% YoY). → Good
Operating Margin: FY26 EBITDA ₹168 Cr, margin 24.6% vs 23.1% last year (+150 bps). → Good
Equity Capital: Stable, face value ₹5. → Good
Dividend Policy: Consistent dividend payouts supported by strong cash generation. → Good
Asset Building: Investments in technology platforms, mobile applications, AI-driven matchmaking, and customer engagement tools. → Good
Sales: Strong contribution from subscription services, premium memberships, and matchmaking platforms. → Good
Expense: Marketing and customer acquisition expenses remain key operating costs. → Neutral
EPS: FY26 EPS ₹40.25 vs ₹34.10 last year (+18.0%). → Good
Institutional Interest & Ownership Trends (Jun 2026)
Promoter Holding: ~50.1% (no pledges)
FII Holding: ~11.4%
DII Holding: ~16.8%
Retail & Others: ~21.7%
Strategic Moves & Innovations
Expansion of AI-powered matchmaking and recommendation engines.
Focus on increasing monetization from premium subscriptions.
Strengthening presence across regional and community-specific matrimony platforms.
Investment in mobile-first customer experiences and digital engagement.
Cash Flow & Balance Sheet Strength
Market cap ~₹1,300 Cr.
Debt‑to‑equity ratio ~0.01 (virtually debt‑free).
Book Value per Share ~₹155.00.
P/B ~3.7.
EPS (TTM) ~₹40.25.
P/E ~14.1.
Risk Factors
Dependence on consumer spending in online matchmaking services.
Increasing competition from dating apps and digital relationship platforms.
Customer acquisition costs may rise due to digital advertising competition.
Technology disruptions and changing user preferences may impact growth.
Investor Takeaway
Matrimony.com remains India's leading organized online matchmaking platform with strong brand recognition, recurring subscription revenues, and a debt‑free balance sheet. The company benefits from increasing internet penetration, digital adoption, and the shift toward online partner discovery across India. With strong promoter backing (Murugavel Janakiraman & Promoter Group holding ~50.1%), healthy profitability, robust cash generation, and leadership in the matrimonial services segment, Matrimony.com remains a quality digital platform business. At CMP ₹566.00, valuations are reasonable (P/E ~14.1, P/B ~3.7), offering investors exposure to a niche internet business with strong cash flows and established market leadership.
The SmartWay Research Desk | 6 November 2026
A Chennai‑based consumer internet company, incorporated in 2001. Matrimony.com Ltd. is India's leading online matchmaking platform, operating well‑known brands including BharatMatrimony, CommunityMatrimony, EliteMatrimony, and Jodii. The company also has interests in wedding-related services and relationship platforms, serving millions of users across India and overseas markets.
Promoter Holding (Jun 2026): Murugavel Janakiraman & Promoter Group — ~50.1% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹682 Cr vs ₹612 Cr in FY25 (+11.4% YoY). → Good
Net Profit: FY26 PAT ₹92 Cr vs ₹78 Cr in FY25 (+17.9% YoY). → Good
Operating Margin: FY26 EBITDA ₹168 Cr, margin 24.6% vs 23.1% last year (+150 bps). → Good
Equity Capital: Stable, face value ₹5. → Good
Dividend Policy: Consistent dividend payouts supported by strong cash generation. → Good
Asset Building: Investments in technology platforms, mobile applications, AI-driven matchmaking, and customer engagement tools. → Good
Sales: Strong contribution from subscription services, premium memberships, and matchmaking platforms. → Good
Expense: Marketing and customer acquisition expenses remain key operating costs. → Neutral
EPS: FY26 EPS ₹40.25 vs ₹34.10 last year (+18.0%). → Good
Institutional Interest & Ownership Trends (Jun 2026)
Promoter Holding: ~50.1% (no pledges)
FII Holding: ~11.4%
DII Holding: ~16.8%
Retail & Others: ~21.7%
Strategic Moves & Innovations
Expansion of AI-powered matchmaking and recommendation engines.
Focus on increasing monetization from premium subscriptions.
Strengthening presence across regional and community-specific matrimony platforms.
Investment in mobile-first customer experiences and digital engagement.
Cash Flow & Balance Sheet Strength
Market cap ~₹1,300 Cr.
Debt‑to‑equity ratio ~0.01 (virtually debt‑free).
Book Value per Share ~₹155.00.
P/B ~3.7.
EPS (TTM) ~₹40.25.
P/E ~14.1.
Risk Factors
Dependence on consumer spending in online matchmaking services.
Increasing competition from dating apps and digital relationship platforms.
Customer acquisition costs may rise due to digital advertising competition.
Technology disruptions and changing user preferences may impact growth.
Investor Takeaway
Matrimony.com remains India's leading organized online matchmaking platform with strong brand recognition, recurring subscription revenues, and a debt‑free balance sheet. The company benefits from increasing internet penetration, digital adoption, and the shift toward online partner discovery across India. With strong promoter backing (Murugavel Janakiraman & Promoter Group holding ~50.1%), healthy profitability, robust cash generation, and leadership in the matrimonial services segment, Matrimony.com remains a quality digital platform business. At CMP ₹566.00, valuations are reasonable (P/E ~14.1, P/B ~3.7), offering investors exposure to a niche internet business with strong cash flows and established market leadership.

Sucrit.D.Patil
Haftungsausschluss
Die Informationen und Veröffentlichungen sind nicht als Finanz-, Anlage-, Handels- oder andere Arten von Ratschlägen oder Empfehlungen gedacht, die von TradingView bereitgestellt oder gebilligt werden, und stellen diese nicht dar. Lesen Sie mehr in den Nutzungsbedingungen.
Sucrit.D.Patil
Haftungsausschluss
Die Informationen und Veröffentlichungen sind nicht als Finanz-, Anlage-, Handels- oder andere Arten von Ratschlägen oder Empfehlungen gedacht, die von TradingView bereitgestellt oder gebilligt werden, und stellen diese nicht dar. Lesen Sie mehr in den Nutzungsbedingungen.