
Insulet Corporation (PODD): A Strong Buy Anchored by Platform Dominance, Strategic Execution, and Robust Financials
Insulet Corporation (PODD), a leader in innovative insulin delivery systems, is strategically positioned for sustained growth in the coming quarters. The company’s trajectory is being powered by the exceptional market adoption of its flagship Omnipod 5 platform, disciplined execution against long-term strategic priorities, and a rock-solid financial foundation. While macroeconomic headwinds and product concentration present inherent risks, the confluence of operational strength, market expansion, and upward earnings revisions makes PODD a compelling investment case, as reflected in its Zacks Rank #1 (Strong Buy).
Investment Thesis and Market Performance
Insulet’s focus on driving penetration, deepening its competitive moat, unlocking new market opportunities, and scaling profitably is yielding tangible results. This execution is mirrored in its stock performance, which has risen 10.6% over the past year, significantly outperforming its industry’s modest 1.5% growth. Although this trails the S&P 500’s 18.9% gain, it underscores the stock’s resilience and growth within its sector. With a market capitalization of $20.19 billion and an earnings yield of 1.7%—far superior to the industry average of 0.2%—the company demonstrates efficient value generation. Furthermore, PODD has a stellar track record of exceeding earnings expectations, delivering an average positive surprise of 17.8% over the last four quarters.
Core Growth Drivers: The Omnipod 5 Ecosystem and Strategic Execution
Omnipod 5: A Market Share Catalyst: Insulet’s Omnipod 5 is a transformative product, distinguished as the only FDA-cleared, fully disposable, pod-based Automated Insulin Delivery (AID) system. Its superior on-body wearability, simplicity, and broad accessibility continue to drive rapid adoption. The platform is a key growth engine internationally, where Q3 2025 revenues surpassed $200 million for the first time, fueled by the Omnipod 5 rollout. In the critical U.S. market, Omnipod revenues grew an impressive 25.6%, exceeding guidance, driven by strong demand across both Type 1 and, notably, Type 2 diabetes populations. The expansion into the Type 2 segment is a monumental opportunity, commercially opening the system to an estimated 5.5 million additional people in the U.S. alone.
Multi-Pronged Strategic Expansion: Insulet is executing a comprehensive growth strategy:
Commercial Investments: The company is ramping up demand generation through direct-to-consumer (DTC) campaigns and mass media to boost global brand awareness.
Platform Innovation: To maintain its technological edge, Insulet continues to enhance Omnipod 5 with key sensor integrations (Dexcom G6/G7, Abbott FreeStyle Libre 2 Plus) and has launched the Omnipod 5 App for iPhone. The pipeline is robust, with the STRIVE pivotal trial for a next-gen hybrid closed loop and the EVOLUTION 2 study for a fully closed loop in Type 2 diabetes underway.
Operational Scaling: Significant capacity investments at manufacturing facilities in Acton and Malaysia, coupled with the integration of AI and cloud-based tools, are designed to streamline service operations and support global scale.
Financial Resilience: Insulet’s balance sheet provides a substantial buffer. The company ended Q3 2025 with a strong liquidity position of $757.4 million in cash and cash equivalents against minimal current debt of $80 million. This financial health is a critical advantage in navigating economic uncertainty. Long-term debt stood at $935 million, showing a slight sequential decrease.
Acknowledged Risks and Challenges
Despite the strong outlook, investors must consider several risk factors:
Macroeconomic and Geopolitical Volatility: Global economic uncertainty can pressure demand, intensify competition, and lengthen sales cycles. Persistent supply chain disruptions and reliance on third-party suppliers, particularly in China, expose the company to risks from political instability, labor issues, and rising tariffs—the reinstatement of which is expected to increase product costs through 2025.
Product Concentration Risk: Insulet’s financial performance remains heavily dependent on the Omnipod System. Any material decline in market acceptance or adverse changes affecting its sales could significantly impact results. Additionally, international expansion introduces exposure to adverse currency fluctuations.
Earnings Estimate Momentum and Technical Perspective
The fundamental optimism is crystallizing in analyst projections. The Zacks Consensus Estimate for Insulet’s 2025 EPS has risen 6.3% over the past 30 days, a clear signal of strengthening confidence. Revenue estimates for 2025 stand at $2.69 billion, implying a substantial 30% year-over-year growth.
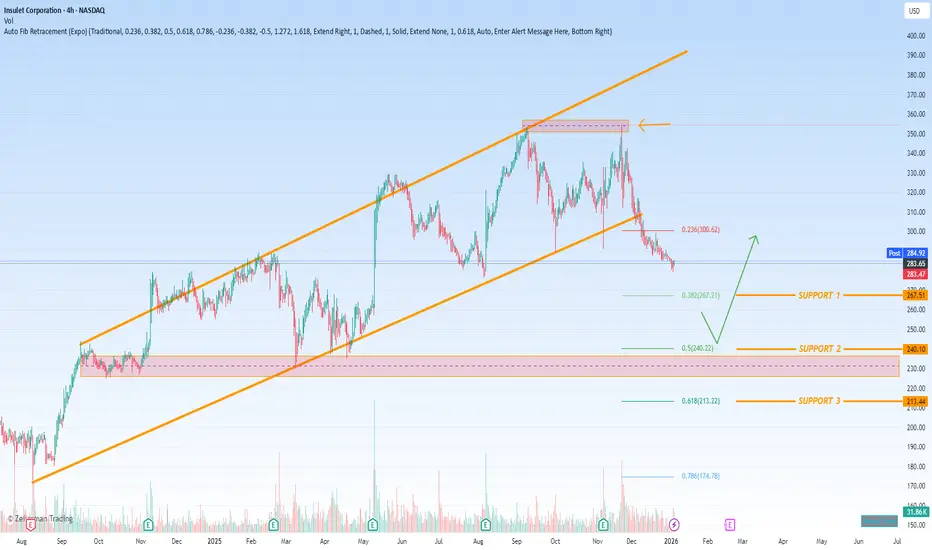
From a technical analysis standpoint, the chart reveals three defined Fibonacci retracement levels that could serve as crucial support zones during any market pullbacks, providing strategic reference points for entry or risk management:
Primary Support Zone: $240.22 - This level, corresponding to the 0.5 Fibonacci retracement, represents a key midline support and a likely area for consolidation and renewed buying interest.
Secondary Support Zone: $267.21 - Aligning with the 0.382 retracement, this zone indicates a shallower, healthier pullback within a strong uptrend if price holds above it.
Tertiary Support Zone: $213.22 - The 0.618 retracement level represents a deeper retracement support, often considered the last defense for a bull trend before a potential reversal.
Conclusion
Insulet Corporation (PODD) presents a compelling investment narrative centered on a dominant growth platform, meticulous strategic execution, and financial strength. The upward revision in earnings estimates and the stock’s Strong Buy Zacks Rank underscore the positive fundamental trajectory. While macroeconomic and concentration risks warrant monitoring, the company’s initiatives to expand its total addressable market, innovate its platform, and scale operations globally position it well for long-term value creation. For investors, the combination of strong fundamentals, positive estimate momentum, and clear technical support levels offers a structured framework for evaluating this high-potential medical technology leader.
Trade ist aktiv
SUPPORT 1 HIT
Haftungsausschluss
Die Informationen und Veröffentlichungen sind nicht als Finanz-, Anlage-, Handels- oder andere Arten von Ratschlägen oder Empfehlungen gedacht, die von TradingView bereitgestellt oder gebilligt werden, und stellen diese nicht dar. Lesen Sie mehr in den Nutzungsbedingungen.
Haftungsausschluss
Die Informationen und Veröffentlichungen sind nicht als Finanz-, Anlage-, Handels- oder andere Arten von Ratschlägen oder Empfehlungen gedacht, die von TradingView bereitgestellt oder gebilligt werden, und stellen diese nicht dar. Lesen Sie mehr in den Nutzungsbedingungen.