OPEN-SOURCE SCRIPT
Kalman Trend State [forexobroker]
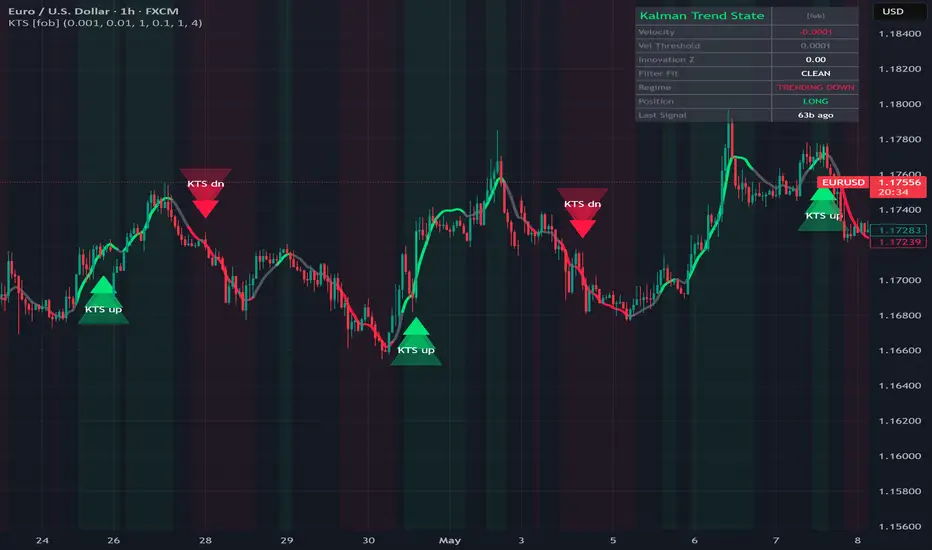
Kalman Trend State applies a recursive Kalman filter to price, treating the unobserved trend as a hidden state with two components: instantaneous price level and per-bar velocity. Unlike a moving average, the filter's smoothing gain updates bar-by-bar from the residuals (innovation), so it adapts to volatility automatically without any length knob.
🔶 ALGORITHM
1. State [px, vx] tracks price and velocity. Transition F = [[1,1],[0,1]] (constant-velocity model).
2. Process noise Q is ATR-adaptive: Q = q_base + q_scale * (ATR / close). Higher volatility = larger Q = faster adaptation.
3. Measurement noise R is fixed (user input). Higher R = filter trusts the model more, smoother output.
4. At each bar: predict (px, P) -> measure close -> update gain K = P_pred * H' / S where S = P_pred[0,0] + R -> correct (px, vx, P).
5. The innovation z-score (close - prediction) / sigma quantifies how well the filter is tracking.
🔶 SIGNAL LOGIC
- Buy: velocity > k * ATR AND |innovation z| <= sigma gate AND close crosses Kalman line up AND not already long AND cooldown elapsed AND barstate.isconfirmed.
- Sell: mirror with velocity < -k * ATR.
- Position-lock state machine prevents same-side over-firing.
🔶 INPUTS
- Process Noise Base Q (default 0.001)
- Q ATR-Pct Scale (default 0.01)
- Measurement Noise R (default 1.0)
- Velocity Threshold x ATR (default 0.10)
- Innovation Sigma Gate (default 1.0)
- Cooldown Bars (default 4)
- Visual: 3-layer glow toggle, Kalman line toggle, dashboard toggle, buy / sell colors
🔶 ALERTS
KTS Buy, KTS Sell, KTS Any Signal, KTS Trend Up Start, KTS Trend Down Start, KTS Clean Fit, KTS Cross Up, KTS Cross Down, KTS Webhook JSON.
🔶 LIMITATIONS
- Kalman is optimal under linear-Gaussian assumptions; price is heavy-tailed, so the filter occasionally lags during regime breaks.
- Warm-up: about 14 bars (ATR seed). Earlier bars have NaN-guarded fallbacks but signals stay flat.
- Defaults tuned for liquid majors and indices on 5m-1H. Re-tune R for tick-driven micro-instruments.
- Velocity threshold scales with ATR but the filter itself does not change shape; for highly seasonal assets, a session-aware variant may help.
Open-source Skript
Ganz im Sinne von TradingView hat dieser Autor sein/ihr Script als Open-Source veröffentlicht. Auf diese Weise können nun auch andere Trader das Script rezensieren und die Funktionalität überprüfen. Vielen Dank an den Autor! Sie können das Script kostenlos verwenden, aber eine Wiederveröffentlichung des Codes unterliegt unseren Hausregeln.

🔵Gain access to our powerful tools : kestutisbalciunas.com/tradingview/
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
Haftungsausschluss
Die Informationen und Veröffentlichungen sind nicht als Finanz-, Anlage-, Handels- oder andere Arten von Ratschlägen oder Empfehlungen gedacht, die von TradingView bereitgestellt oder gebilligt werden, und stellen diese nicht dar. Lesen Sie mehr in den Nutzungsbedingungen.
Open-source Skript
Ganz im Sinne von TradingView hat dieser Autor sein/ihr Script als Open-Source veröffentlicht. Auf diese Weise können nun auch andere Trader das Script rezensieren und die Funktionalität überprüfen. Vielen Dank an den Autor! Sie können das Script kostenlos verwenden, aber eine Wiederveröffentlichung des Codes unterliegt unseren Hausregeln.
🔵Gain access to our powerful tools : kestutisbalciunas.com/tradingview/
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
Haftungsausschluss
Die Informationen und Veröffentlichungen sind nicht als Finanz-, Anlage-, Handels- oder andere Arten von Ratschlägen oder Empfehlungen gedacht, die von TradingView bereitgestellt oder gebilligt werden, und stellen diese nicht dar. Lesen Sie mehr in den Nutzungsbedingungen.