OPEN-SOURCE SCRIPT
Kalman Regime [Jamallo]
(2025)
Intro
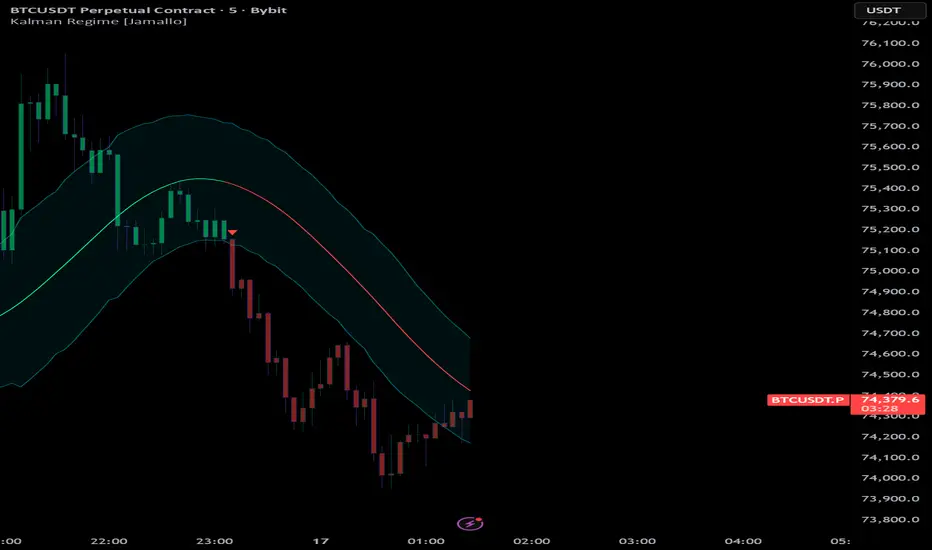
Kalman Regime filters price through two stages — a Gaussian kernel weighted average followed by an adaptive Kalman filter — to produce a smooth, noise-resistant baseline. ATR is used throughout to make the system volatility-aware.
Breakdown
The Gaussian kernel pre-smooths price using a bell-shaped weight profile that blends recency bias (recent bars matter more) with center localization (edge bars contribute less). This pre-smoothed value is then passed into an adaptive Kalman filter, which recursively estimates the "true" price state by balancing how much to trust the new measurement versus the prior state — with that balance dynamically scaled by current ATR.
The resulting baseline drives regime detection through a two-tier state machine. A strong signal fires when price breaks the ATR envelope and the baseline slope confirms direction. A weaker signal fires when price crosses the baseline and slope exceeds an ATR-scaled threshold. This dual-gate structure reduces whipsaws without adding lag.
END
A two-stage price filter combining a Gaussian kernel pre-smoother with an adaptive Kalman filter, using ATR envelopes and slope confirmation for regime detection.
Open-source Skript
Ganz im Sinne von TradingView hat dieser Autor sein/ihr Script als Open-Source veröffentlicht. Auf diese Weise können nun auch andere Trader das Script rezensieren und die Funktionalität überprüfen. Vielen Dank an den Autor! Sie können das Script kostenlos verwenden, aber eine Wiederveröffentlichung des Codes unterliegt unseren Hausregeln.

Join the Growing (Econophysics Trading) Community! ⚛️
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
Haftungsausschluss
Die Informationen und Veröffentlichungen sind nicht als Finanz-, Anlage-, Handels- oder andere Arten von Ratschlägen oder Empfehlungen gedacht, die von TradingView bereitgestellt oder gebilligt werden, und stellen diese nicht dar. Lesen Sie mehr in den Nutzungsbedingungen.
Open-source Skript
Ganz im Sinne von TradingView hat dieser Autor sein/ihr Script als Open-Source veröffentlicht. Auf diese Weise können nun auch andere Trader das Script rezensieren und die Funktionalität überprüfen. Vielen Dank an den Autor! Sie können das Script kostenlos verwenden, aber eine Wiederveröffentlichung des Codes unterliegt unseren Hausregeln.
Join the Growing (Econophysics Trading) Community! ⚛️
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
Haftungsausschluss
Die Informationen und Veröffentlichungen sind nicht als Finanz-, Anlage-, Handels- oder andere Arten von Ratschlägen oder Empfehlungen gedacht, die von TradingView bereitgestellt oder gebilligt werden, und stellen diese nicht dar. Lesen Sie mehr in den Nutzungsbedingungen.