
🎯 STOCK TO WATCH
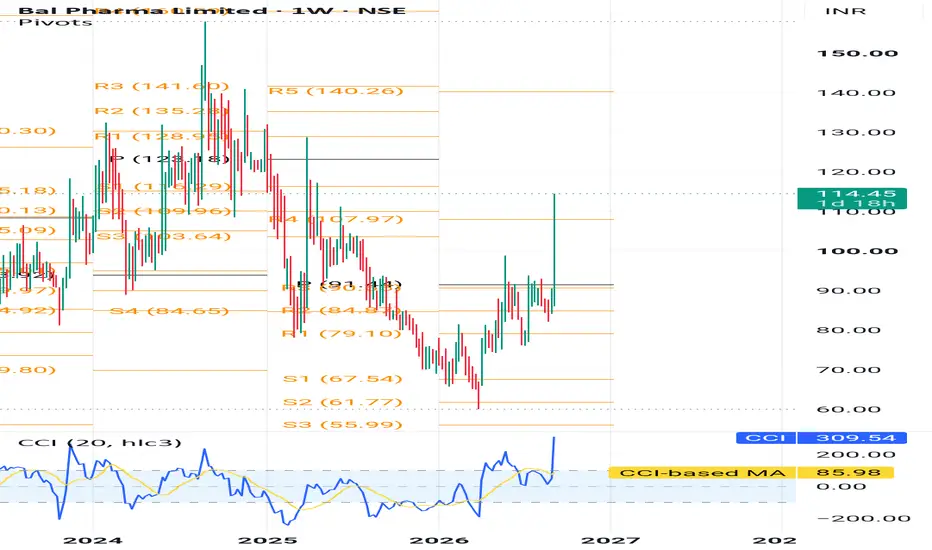
WEEKLY R4 MOMENTUM BREAKOUT SETUP
₹110–114 → ₹160 → ₹294 → ₹362
A small-cap pharma + API + export-oriented momentum setup appearing on my Weekly R4 Momentum Breakout Scanner.
💊 BAL PHARMA LTD
NSE: BALPHARMA
📌 TRADE LEVELS
🟢 Buy Zone: ₹110–114
🟠 Breakout Zone: ₹107
🔴 Stop Loss: ₹82
🎯 Target 1: ₹160
🚀 Target 2: ₹294
🔥 Target 3: ₹362
🔥 WHY BAL PHARMA?
• Revenue momentum: Q1 FY27 consolidated revenue was about ₹89 Cr, up ~34% YoY.
• API + formulations business: Bal Pharma operates across bulk actives, prescription/generic medicines, OTC products, IV infusions and formulations.
• Export-oriented platform: Its APIs and formulations are supplied across Europe, Australia, Japan, Far East, Latin America, Africa and Middle East markets.
• Integrated manufacturing: The company has manufacturing facilities across Bengaluru, Pune, Rudrapur, Sangli and Udaipur.
• Niche product portfolio: Its API portfolio spans areas including anti-diabetic, anti-histamine, anti-inflammatory, cardiovascular and other therapeutic segments.
• Fresh promoter capital: On 7 September 2026, Bal Pharma allotted 10 lakh convertible warrants to promoter Shailesh Siroya at ₹84 per warrant, aggregating ₹8.40 Cr.
👀 WHY IT CAUGHT MY ATTENTION
📈 ₹107 is the key breakout reference on my scanner.
📈 Buy zone sits at ₹110–114.
📈 Revenue growth has accelerated YoY.
📈 Export/API exposure provides multiple geographical markets.
📈 Small-cap pharma can produce sharp momentum when earnings and technical structure align.
📈 Promoter warrant allotment at ₹84 is worth tracking as a recent corporate-development signal.
⚠️ IMPORTANT — THIS ONE NEEDS DISCIPLINE
The Q1 headline growth is stronger than the sequential earnings picture. Operating profit was ₹7.95 Cr, down 24.8% QoQ, while net profit was ₹1.12 Cr, down 68.8% QoQ.
So I would not treat this as a pure fundamental compounder yet. The technical setup needs confirmation through sustained revenue growth, margins and cash generation.
Also, the recent ₹84 preferential warrant issue to the promoter should be factored into any detailed dilution/shareholding analysis.
Risk Defined. Reward Visible.
⚠️ This content is for educational purposes only and not investment advice. Please do your own due diligence before making any investment decisions.
© 20K Microcap Investing | R4 Momentum Desk
#BalPharma #BALPHARMA #PharmaStocks #APIStocks #SmallCapStocks #MomentumStocks #BreakoutStocks #IndianStocks #R4Momentum #StockToWatch

Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.
Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.