
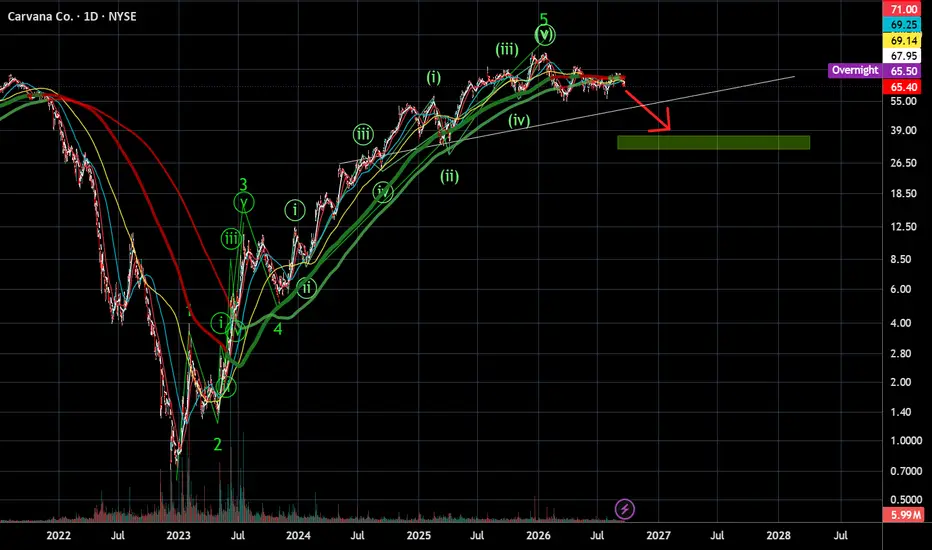
Whether there is fraud or not, the car and loan markets are experiencing serious pressure as consumer discretionary spending is weakening.
This is the end of an extended 5th wave.
Google it.
This is the end of an extended 5th wave.
Google it.
Nota
Carvana is reporting earnings in 16 days.You are witnessing an extended 5th wave ending here, which typically results in explosive moves to the downside.
$35/share is a minimum downside target here per the extended 5th wave technical structure.
I'll be watching this stock closely.
Nota
Carvana's Own Debt: The company needs to refinance operations and fund inventory. A rising 2-year yield makes corporate borrowing more expensive. Carvana recently raised a $1 billion term loan (rated BB by Fitch as of August 2026), and when Treasury yields spike, the spread Carvana must pay over those risk-free benchmarks typically widens, increasing its cost of capital.Customer Financing Costs: While auto loan rates track the 5-year Treasury yield more closely, the 2-year yield influences short-term funding costs that cascade into the broader lending market. As short-term rates rise, lenders face higher costs to fund car purchases, which they pass on to borrowers through higher APRs. This reduces customer demand, as higher monthly payments make vehicles less affordable—especially for Carvana's core demographic of lower- and middle-income consumers.
Carvana's Unique Financing Model and Vulnerability
Carvana's business model creates particular sensitivity to interest rate changes:
The Securitization Model
Carvana originates auto loans and immediately packages them as asset-backed securities (ABS) to investors, rather than holding debt on its books. This means:
When Treasury yields rise, the yields investors demand on auto loan securities also rise, making it more expensive for Carvana to sell securitized loans at favorable terms.
Credit spreads widen during uncertainty, meaning investors demand higher premiums over Treasuries to buy auto loan ABS.
Higher yields on ABS reduce the net present value of origination gains Carvana records upfront.
Operación activa
Prepare for blood in the streets.My downside target is still $35-40 over the next 6 months.
Nota
Could see this $35-40 target in 1-2 months from now, if this plays out similarly to the 2022 selloff. 
Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.
Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.