
UNIP – Scrap Value vs. Financial Reality 📉📦
The Reality: A classic "Value Trap" in the penny stock realm. 🕸️
While revenue sits at EGP 1.37 billion, net income has collapsed by 87% to a mere EGP 13.05 million.
With a razor-thin net profit margin of 0.95%, the company is effectively dancing on the edge of a loss. ⛸️🔴
The Cash Squeeze: The balance sheet is under heavy fire. 📉
Less than 40% of operating profit is turning into cash, as liquidity remains trapped in slow-moving inventory.
With a staggering 111.7% Debt-to-Equity ratio, UNIP is gasping for air in this high-interest environment.
It’s currently "dead money" unless a miracle restructuring or merger occurs. 🩹🏦
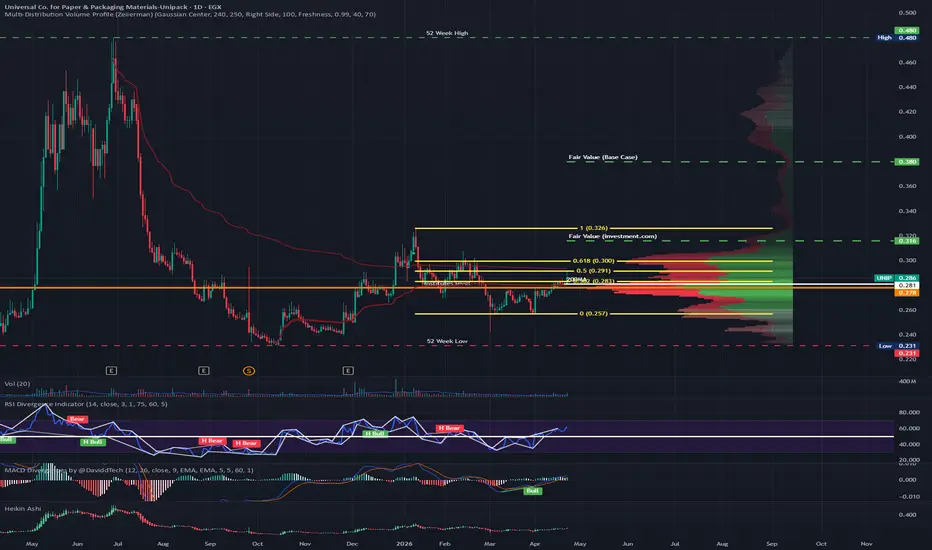
The Valuation: On paper, it looks like a bargain, trading at EGP 0.28 less than half its Book Value of 0.63 EGP. 📚
While my mathematical Fair Value estimate of 0.380 EGP (using a recovery P/E of 18.5x) suggests upside, the market is currently pricing it at "scrap" value for a reason. 🧱⚖️
Sharia Status: ❌ Non-Compliant. UNIP fails the quantitative screens for the EGX33 Shariah Index (April 2026).
The heavy debt used to finance production and non-permissible interest income from its cash management break both the 30% and 5% thresholds. ☪️🚫
Verdict: A Cyclical Gamble.
UNIP is at a "Cyclical Bottom," but without a catalyst, it’s just a falling knife.
I don't even need to technical analysis this stock; enter at your own risk, but at least wait until it is over 0.30. 🛡️📉
If you like my posts, please follow and boost 🙌
🎁 Get a $15 discount on your next subscription:
🔗 tradingview.com/pricing/?share_your_love=mnmabroukw36ix ✨💸
The Reality: A classic "Value Trap" in the penny stock realm. 🕸️
While revenue sits at EGP 1.37 billion, net income has collapsed by 87% to a mere EGP 13.05 million.
With a razor-thin net profit margin of 0.95%, the company is effectively dancing on the edge of a loss. ⛸️🔴
The Cash Squeeze: The balance sheet is under heavy fire. 📉
Less than 40% of operating profit is turning into cash, as liquidity remains trapped in slow-moving inventory.
With a staggering 111.7% Debt-to-Equity ratio, UNIP is gasping for air in this high-interest environment.
It’s currently "dead money" unless a miracle restructuring or merger occurs. 🩹🏦
The Valuation: On paper, it looks like a bargain, trading at EGP 0.28 less than half its Book Value of 0.63 EGP. 📚
While my mathematical Fair Value estimate of 0.380 EGP (using a recovery P/E of 18.5x) suggests upside, the market is currently pricing it at "scrap" value for a reason. 🧱⚖️
Sharia Status: ❌ Non-Compliant. UNIP fails the quantitative screens for the EGX33 Shariah Index (April 2026).
The heavy debt used to finance production and non-permissible interest income from its cash management break both the 30% and 5% thresholds. ☪️🚫
Verdict: A Cyclical Gamble.
UNIP is at a "Cyclical Bottom," but without a catalyst, it’s just a falling knife.
I don't even need to technical analysis this stock; enter at your own risk, but at least wait until it is over 0.30. 🛡️📉
If you like my posts, please follow and boost 🙌
🎁 Get a $15 discount on your next subscription:
🔗 tradingview.com/pricing/?share_your_love=mnmabroukw36ix ✨💸

Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.
Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.