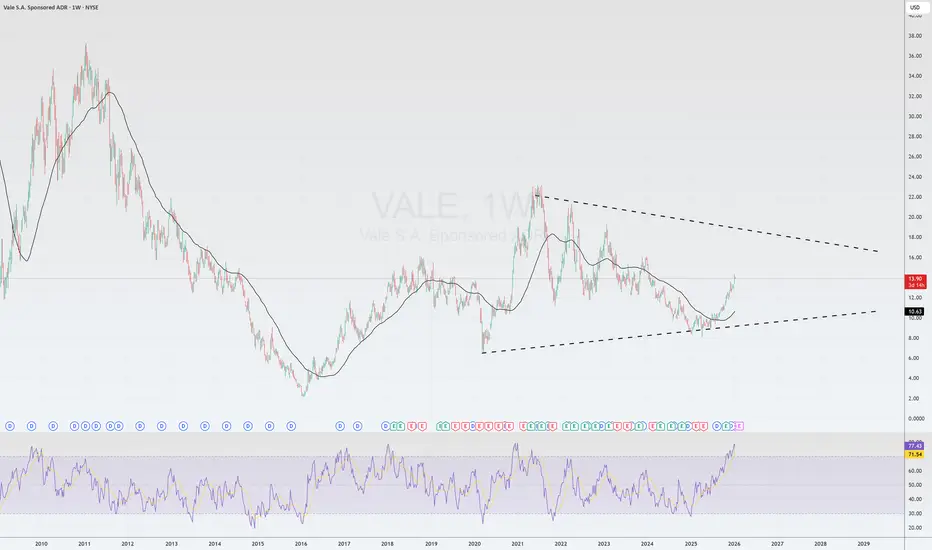
 VALE: Thesis for 2026
1. Strategic Pivot: From Iron Ore Proxy to Base Metals Leader
The most significant development for Vale in 2026 is the transformation of its base metals segment (nickel and copper) from a secondary unit into a primary profit engine.
Nickel Supply Shock: Indonesia, which controls over 50% of global supply, has implemented a 34% production cut for 2026. This has already triggered a >25% price surge within a month.
EBITDA Outperformance: This supply-side pressure could increase Vale’s consolidated EBITDA by ~8%. Current projections suggest the non-ferrous division could exceed $4 billion in EBITDA for 2026, significantly outperforming market consensus of $3 billion.
Copper Growth: Vale’s copper production is forecasted to grow at a 7% CAGR through 2035, outstripping global peers. Strategic moves, such as the Glencore joint venture in the Sudbury Basin, solidify this growth trajectory.
2. Operational Excellence and Cost Leadership
🔎

Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.
Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.