
🔵 WHY BACKTEST AT ALL
A backtest is the cheapest way to discover that your edge does not exist. Better to find it in data than in your account. But a backtest is only as honest as its rules — and most backtests are dishonest in the same, quiet way.
🔵 THE EXACT-MECHANICS RULE
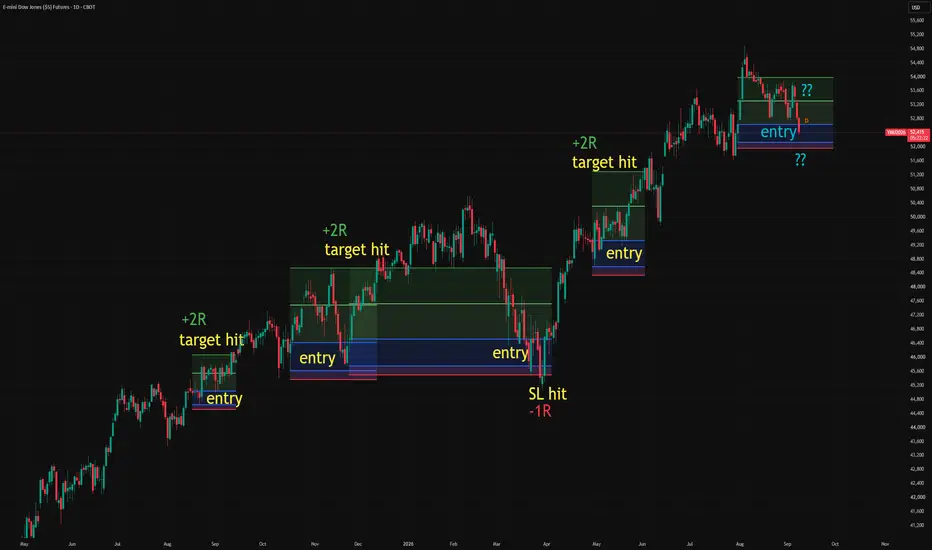
Before any test, write the trade in full mechanical detail: the exact entry condition, the exact stop, the exact target, the exact size. "Enter near support" is not testable — "buy on a daily close above X, stop below Y, first target Z" is. If two people reading your rules would trade differently, the rules are not rules yet.
🔵 THE SILENT LIES
Watch for the classics: curve-fitting (the rules were tuned on the same data they are tested on), ignoring costs (spread, commission, slippage — they eat small edges whole), cherry-picking the start date, and "after-the-fact" entry — entering at the exact low because the chart is already drawn. Every one of these inflates the result.
🔵 THE 80% RULE
A realistic backtest should survive a haircut: subtract costs, assume worse fills, test a different start date. If the edge disappears under the haircut, it was never an edge — it was precision disguised as insight.
Next lesson: the journal — the tool that turns your own trading into data.
Educational content only. Not investment advice.

Full multi-TF zones + COT + Macro Bias + Seasonality → confluenceedge.net
Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.