Actualizado
Joint-state Kalman Filter (Linear / Extended / Unscented)
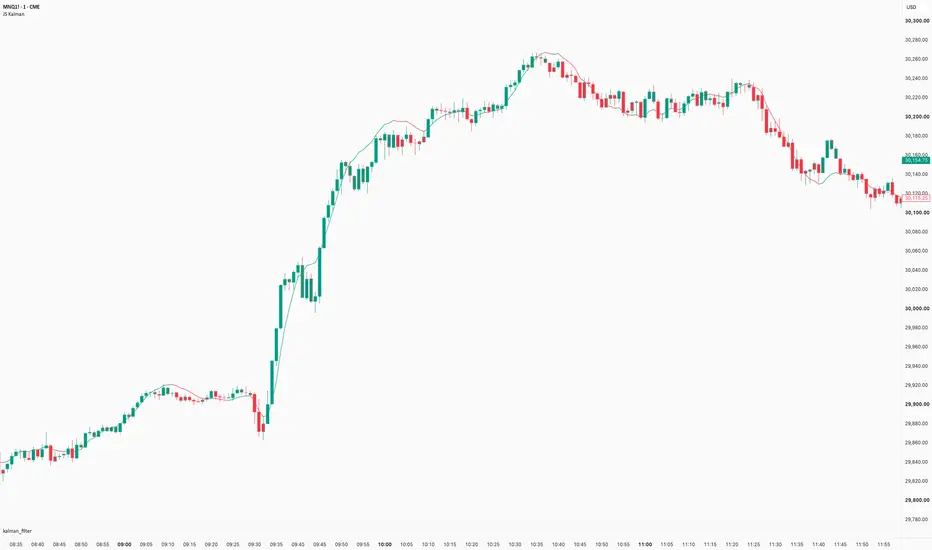
Joint-state Kalman Filter (Linear / Extended / Unscented) · JS Kalman
A joint-state price filter — not a typical 1D random-walk smoother. It estimates coupled [level, velocity] (and optionally acceleration) in one shared covariance, so trend tracking and reversal behaviour move together.
Filter types
State models
Switching filter type reuses the same internal state (you may see a one-bar discontinuity).
On the chart
Settings at a glance
Licence
Indicator and library © igor_sinkovec — Mozilla Public License 2.0.
A joint-state price filter — not a typical 1D random-walk smoother. It estimates coupled [level, velocity] (and optionally acceleration) in one shared covariance, so trend tracking and reversal behaviour move together.
Filter types
- Linear — kinematic Kalman; less lag on trends, can overshoot at sharp reversals (more with C.Accel).
- Extended — same layout with velocity damping v' = v × (1 − damping × |v|); analytic Jacobian.
- Unscented — same nonlinearity via sigma points (falls back to Extended if the covariance square root fails).
State models
- C.Veloc — constant velocity: [level, velocity]
- C.Accel — constant acceleration: [level, velocity, acceleration] (default)
Switching filter type reuses the same internal state (you may see a one-bar discontinuity).
On the chart
- Filtered price — teal while rising, red while falling (optional).
- Candle paint — same trend colours on the bars (optional).
Settings at a glance
- Model — filter type, state model, source, velocity damping (Extended / Unscented).
- Noise — process noise per component and measurement noise.
- Unscented — alpha, beta, kappa (Unscented only).
- UI — show filtered line, paint candles.
Licence
Indicator and library © igor_sinkovec — Mozilla Public License 2.0.
Notas de prensa
UI improvementsAbility to choose plot and candle colors.

Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.
Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.