OPEN-SOURCE SCRIPT
Kalman Regime [Jamallo]
(2025)
Intro
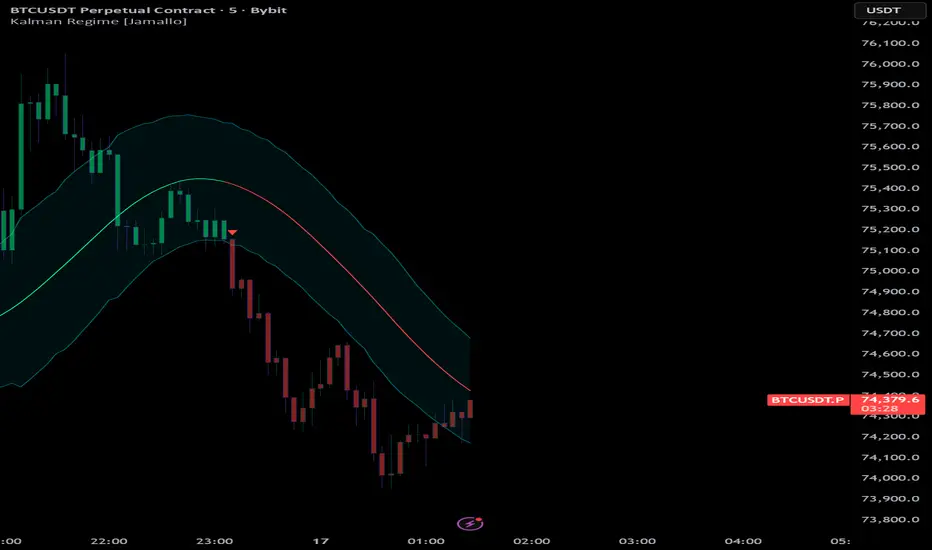
Kalman Regime filters price through two stages — a Gaussian kernel weighted average followed by an adaptive Kalman filter — to produce a smooth, noise-resistant baseline. ATR is used throughout to make the system volatility-aware.
Breakdown
The Gaussian kernel pre-smooths price using a bell-shaped weight profile that blends recency bias (recent bars matter more) with center localization (edge bars contribute less). This pre-smoothed value is then passed into an adaptive Kalman filter, which recursively estimates the "true" price state by balancing how much to trust the new measurement versus the prior state — with that balance dynamically scaled by current ATR.
The resulting baseline drives regime detection through a two-tier state machine. A strong signal fires when price breaks the ATR envelope and the baseline slope confirms direction. A weaker signal fires when price crosses the baseline and slope exceeds an ATR-scaled threshold. This dual-gate structure reduces whipsaws without adding lag.
END
A two-stage price filter combining a Gaussian kernel pre-smoother with an adaptive Kalman filter, using ATR envelopes and slope confirmation for regime detection.
Script de código abierto
Fiel al espíritu de TradingView, el creador de este script lo ha convertido en código abierto, para que los traders puedan revisar y verificar su funcionalidad. ¡Enhorabuena al autor! Aunque puede utilizarlo de forma gratuita, recuerde que cualquier republicación del código está sujeta a nuestras Normas internas.

Join the Growing (Econophysics Trading) Community! ⚛️
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.
Script de código abierto
Fiel al espíritu de TradingView, el creador de este script lo ha convertido en código abierto, para que los traders puedan revisar y verificar su funcionalidad. ¡Enhorabuena al autor! Aunque puede utilizarlo de forma gratuita, recuerde que cualquier republicación del código está sujeta a nuestras Normas internas.
Join the Growing (Econophysics Trading) Community! ⚛️
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.