OPEN-SOURCE SCRIPT
Louis Bachelier's Random Walk
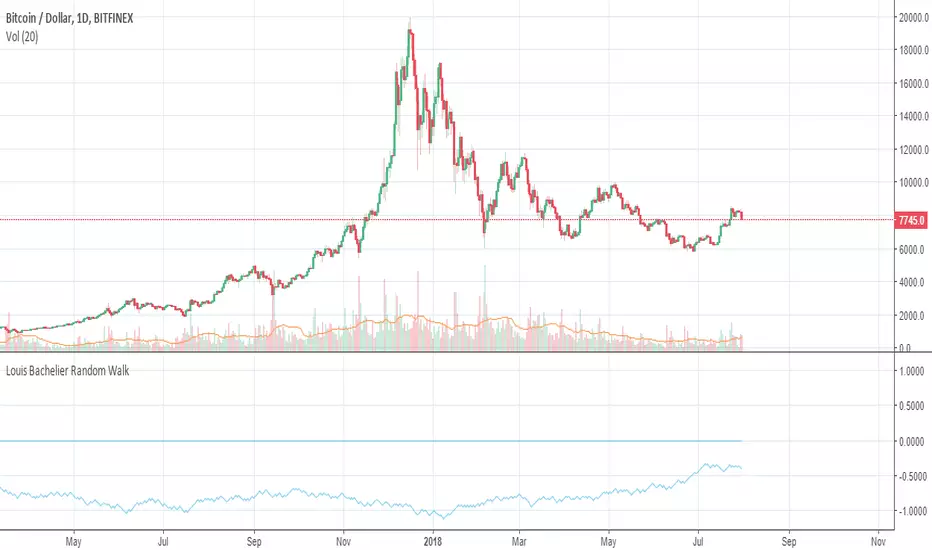
Several tests of market efficiency have been developed over the years. The very first test, constructed by Louis Bachelier in 1900, measured the probability of a number of consecutively positive or consecutively negative price changes, or “runs.”
The randomness of runs is rejected with 95 percent statistical confidence whenever the plotted value is greater than 0. The randomness of runs cannot be rejected if it's < 0.
The randomness of runs is rejected with 95 percent statistical confidence whenever the plotted value is greater than 0. The randomness of runs cannot be rejected if it's < 0.
Script de código abierto
Fiel al espíritu de TradingView, el creador de este script lo ha convertido en código abierto, para que los traders puedan revisar y verificar su funcionalidad. ¡Enhorabuena al autor! Aunque puede utilizarlo de forma gratuita, recuerde que cualquier republicación del código está sujeta a nuestras Normas internas.

Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.
Script de código abierto
Fiel al espíritu de TradingView, el creador de este script lo ha convertido en código abierto, para que los traders puedan revisar y verificar su funcionalidad. ¡Enhorabuena al autor! Aunque puede utilizarlo de forma gratuita, recuerde que cualquier republicación del código está sujeta a nuestras Normas internas.
Exención de responsabilidad
La información y las publicaciones no constituyen, ni deben considerarse como, asesoramiento o recomendaciones financieras, de inversión, de trading u otro tipo, proporcionadas o respaldadas por TradingView. Obtenga más información en Condiciones de uso.