
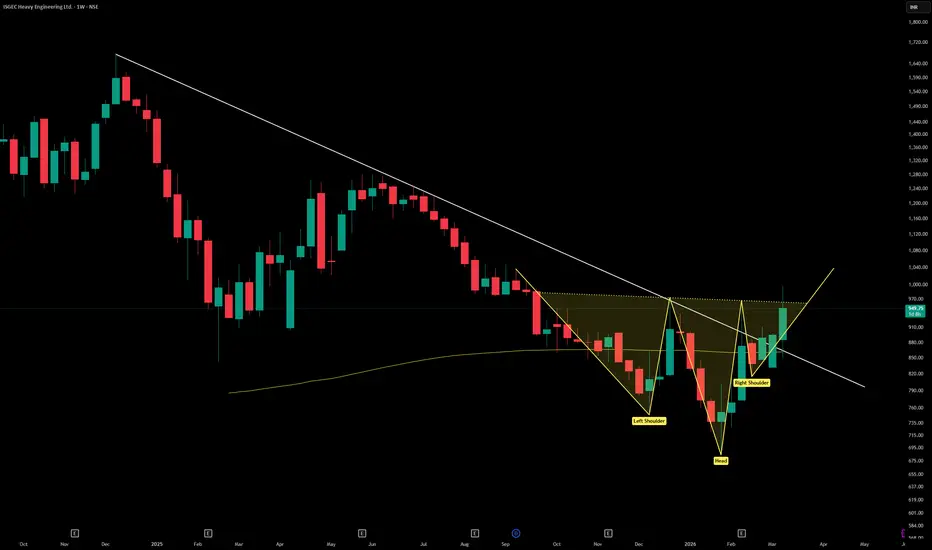
ISGEC Heavy Engineering Ltd. (NSE: ISEG) is a diversified capital goods and heavy engineering company, incorporated in 1933. It manufactures boilers, sugar machinery, process equipment, presses, contract manufacturing solutions, and executes EPC projects across India and abroad.
Promoter: Indian Promoter Group – 62.43% holding (Dec 2025)
FY22–FY26 Snapshot
Revenue Growth: CAGR ~11% over FY22–FY26, driven by EPC contracts and industrial equipment demand. → Good
Net Profit: FY26 PAT ~₹420 Cr, reflecting steady growth. → Good
Operating Margin: Maintained ~10–12%, moderate compared to peers like Thermax. → Neutral
Equity Capital: Stable, no major dilution. → Good
Dividend Policy: Conservative, yield ~1.2% (FY26). → Neutral
Asset Building: Expansion of manufacturing facilities and EPC portfolio. → Good
Sales: FY26 revenue crossed ₹7,800 Cr, supported by domestic and export contracts. → Good
Expense: Raw material and project execution costs remain high. → Neutral
EPS: ~₹28.5 in FY26, reflecting consistent profitability. → Good
Institutional Interest & Ownership Trends
Largest Promoter: Indian Promoter Group – 62.43%
Largest FII: Collective foreign institutional investors – 3.6%
Largest DII: Mutual funds – 9.26%
Others (Retail & Institutions): ~23.5%
Strategic Moves & Innovations
Expansion into boilers, sugar machinery, and process equipment.
Focus on EPC contracts in power, oil & gas, and infrastructure.
Investment in automation and advanced manufacturing technologies.
Strengthening exports to Asia, Africa, and the Middle East.
Cash Flow & Balance Sheet Strength
Strong operating cash flows supported by EPC projects.
Debt levels moderate, manageable with steady profits.
Consistent profit growth supports scalability.
Risk Factors
Dependence on industrial capex cycles.
Margin sensitivity to raw material and project execution costs.
Competition from Thermax, BHEL, and L&T.
Regulatory risks in large infrastructure projects.
Investor Takeaway
ISGEC Heavy Engineering Ltd. is a diversified heavy engineering company with strong promoter backing and moderate institutional interest. With most snapshot parameters rated Good, the company shows consistent EPS growth, robust asset building, and strong sales momentum. Investors should monitor project execution costs and industrial demand cycles, but overall the outlook remains positive.

Sucrit.D.Patil
Clause de non-responsabilité
Les informations et publications ne sont pas destinées à être, et ne constituent pas, des conseils ou recommandations financiers, d'investissement, de trading ou autres fournis ou approuvés par TradingView. Pour en savoir plus, consultez les Conditions d'utilisation.