
Tech Breakout, Narrow Participation — Strength Is Real, Confirmation Is Incomplete
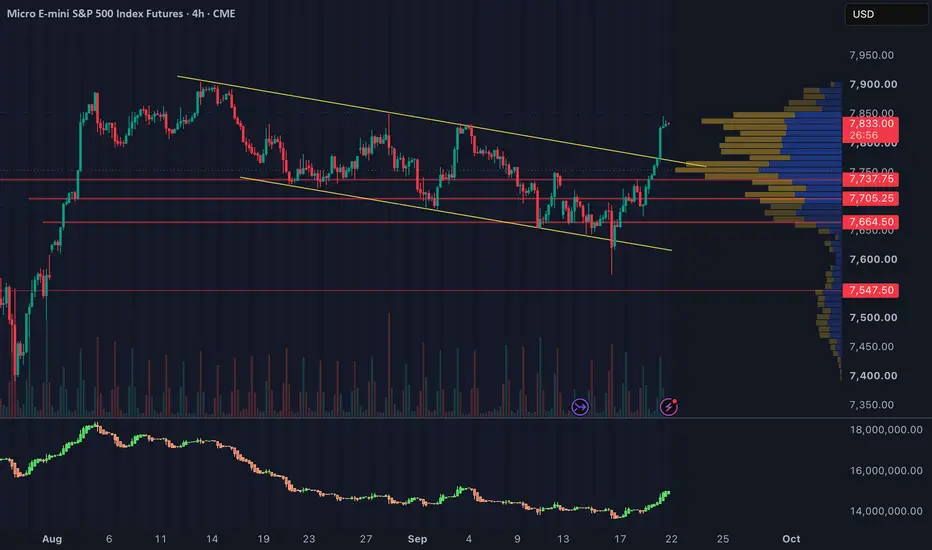
U.S. equities pushed sharply higher Monday, led by another major acceleration in technology and semiconductors. MES broke through several important resistance areas and traded into the 7,830s, while MNQ extended above 30,800. SPY is once again pressing toward all-time highs.
The important distinction is that the price strength is real, but the broader market is still not confirming it cleanly.
Semiconductors were the clear leadership group. SOX and SMH surged, NVDA reclaimed its major trend structure, AMD produced another outsized move, and META, MSFT, GOOGL, AMZN and other large technology names participated. This gives the NQ move considerably more legitimacy than a rally driven by one or two names.
However, breadth remains the primary contradiction. Equal-weight RSP materially lagged SPY, the RSP/SPY ratio continued lower, and the percentage of S&P 500 stocks above key moving averages remains depressed. KRE also remains structurally weak while broader financials have not matched the strength in technology.
Internals were mixed rather than outright bearish. ADD finished positive and VOLD improved, but cumulative TICK remained soft. Several strong technology names also showed weaker CVD relative to their price advances, suggesting that price is currently outrunning some measures of aggressive buying.
Volatility remains supportive of equities. VIX is near 14.9, VIX1D near 10, and VX futures remain subdued. One item worth monitoring is continued strength in VX CVD despite lower volatility pricing. It is not a bearish signal by itself, but the divergence deserves attention if equity leadership begins to weaken.
Rates provided another tailwind. Treasury yields declined across much of the curve while TLT rallied, reducing pressure on long-duration growth stocks. Yet HYG/LQD weakened again, leaving credit as another area that has not confirmed the equity breakout.
The broader cross-asset picture therefore remains unusually dispersed:
Tech / semiconductors: Strong
ES / NQ price structure: Strong
Volatility: Supportive
Rates: More supportive
Breadth / equal weight: Weak
Regional banks: Weak
Credit: Soft
Implied correlation: Very low
SITCo Read
The market remains in a tech-led risk-on / high-dispersion regime.
The mistake would be treating weak breadth as an automatic reason to fade strong price. As long as MES/MNQ maintain acceptance above reclaimed structure and semiconductor leadership remains intact, price continues to deserve respect.
The vulnerability appears if the market loses its leadership while RSP, KRE and credit remain weak. That would turn today's narrow participation from a background concern into meaningful downside confirmation.
For now:
Respect the breakout. Monitor the internals. Do not confuse index strength with broad market health.

Clause de non-responsabilité
Les informations et publications ne sont pas destinées à être, et ne constituent pas, des conseils ou recommandations financiers, d'investissement, de trading ou autres fournis ou approuvés par TradingView. Pour en savoir plus, consultez les Conditions d'utilisation.
Clause de non-responsabilité
Les informations et publications ne sont pas destinées à être, et ne constituent pas, des conseils ou recommandations financiers, d'investissement, de trading ou autres fournis ou approuvés par TradingView. Pour en savoir plus, consultez les Conditions d'utilisation.