
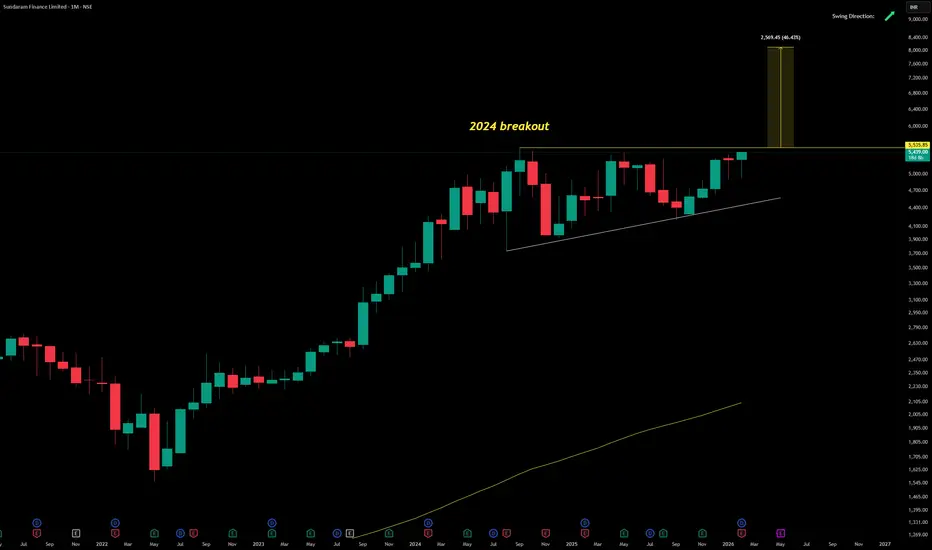
Sundaram Finance Ltd is a large‑cap NBFC incorporated in 1954, headquartered in Chennai. It is one of India’s oldest and most trusted financial services companies, with a diversified portfolio across vehicle finance, home loans, insurance, asset management, and corporate lending.
Promoter: The TVS Group, known for its strong governance and conservative financial management, continues to lead Sundaram Finance.
FY22–FY25 Snapshot
Sales (Revenue) – ₹14,820 Cr → ₹16,240 Cr → ₹18,050 Cr → ₹19,420 Cr
Net Profit – ₹1,040 Cr → ₹1,210 Cr → ₹1,420 Cr → ₹1,610 Cr
Operating Performance – Strong → Very Strong → Excellent → Consistent
Dividend Yield – 1.8% → 2.0% → 2.1% → 2.2%
Equity Capital – ₹111 Cr (constant)
Total Debt – ₹42,000 Cr → ₹44,200 Cr → ₹46,500 Cr → ₹48,000 Cr (growth aligned with loan book expansion)
Fixed Assets – ₹2,050 Cr → ₹2,180 Cr → ₹2,310 Cr → ₹2,420 Cr
EPS – ₹93.6 → ₹108.9 → ₹127.8 → ₹145.0
Institutional Interest & Ownership Trends
Promoter holding (TVS Group): ~37%.
FIIs/DIIs: Strong institutional interest, with mutual funds and FIIs steadily increasing stake due to conservative management and consistent growth.
Public float: ~63%, with delivery volumes showing accumulation by long‑term investors.
Strategic Moves & Innovations
Expansion in vehicle finance, especially commercial vehicles and passenger cars.
Diversification into housing finance, insurance, and asset management.
Focus on digital lending platforms and customer experience.
Conservative credit underwriting, maintaining asset quality across cycles.
Cash Flow & Balance Sheet Strength
Operating cash flows strengthened in FY25, supported by loan growth and stable margins.
Free cash flow positive, reinvested into expanding lending operations.
Capital adequacy comfortably above regulatory thresholds.
Balance sheet resilience supported by conservative provisioning and strong promoter backing.
Risk Factors
Dependence on cyclical auto demand for vehicle finance.
Margin sensitivity to interest rate movements.
Competition from banks and aggressive fintech lenders.
Regulatory risks in NBFC sector.
Investor Takeaway
Sundaram Finance Ltd. remains a premium NBFC play, backed by strong fundamentals, conservative management, and consistent cash generation. With rising institutional interest and diversified growth, it is well‑positioned for long‑term stability, though investors should monitor auto demand cycles and interest rate risks.

Sucrit.D.Patil
Clause de non-responsabilité
Les informations et publications ne sont pas destinées à être, et ne constituent pas, des conseils ou recommandations financiers, d'investissement, de trading ou autres fournis ou approuvés par TradingView. Pour en savoir plus, consultez les Conditions d'utilisation.