
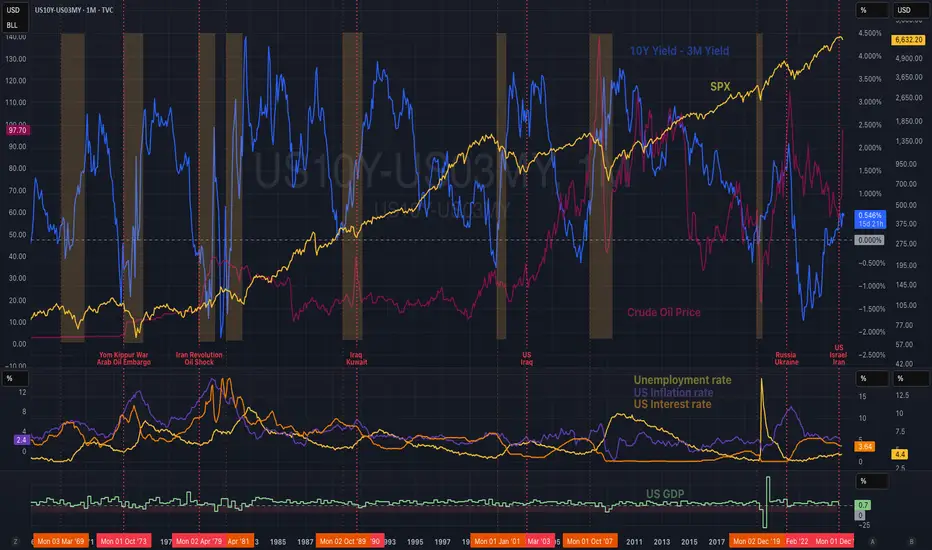
Almost two years ago, in my post “A Recession Is Coming - Brace for Impact”, I talked about the inverted yield curve as a warning sign. Now the curve has already un-inverted, and that part matters a lot.
In my opinion, the inversion is usually the warning, and the un-inversion is often when the economy starts to feel the pressure that the bond market had already priced in earlier.
The U.S. economy was already slowing down before this recent oil shock and the rising tension in the Middle East. U.S. real GDP growth for Q4 2025 was revised down to 0.7%, versus 4.4% in Q3, and the unemployment rate in February 2026 was 4.4%. That is not a collapse, but it is not a strong backdrop either.
In my recent post, “S&P and a very timely correction for the U.S. president”, I mentioned this chain:
Higher Oil Price --> Higher Inflation --> Higher Rates (or fewer cuts) --> Lower Corporate Profits --> Lower Equities
I still think that chain is very relevant.
Why? Because this is not just about oil going up on a headline. Oil is up sharply, and the Strait of Hormuz disruption is threatening a route that carries a very large share of global oil supply, more than 20%. If this persists, it can push transportation costs, production costs, and consumer costs higher again. That is how a geopolitical shock turns into a macro problem.
And we have seen this type of reaction before. During major geopolitical conflicts that affected energy markets, like the 1973 oil embargo, the 1979 Iranian shock, the 1990 Gulf crisis, and even the 2022 Russia-Ukraine war. As a result, oil moved higher, inflation pressure increased, and equities came under stress. Of course every cycle is different, but the pattern is often similar: when energy becomes more expensive, margins get tighter, growth slows down, and the S&P starts repricing that risk.
This is where the word stagflation becomes important.
For anyone new to the term, recession means slower growth, weaker demand, and a softer labor market.
Stagflation is when growth slows down while inflation stays high or moves higher again.
That is a much more difficult environment for the market, because the Fed cannot support the economy as easily if inflation is still being pushed up by energy. So even if growth weakens, policy may stay tighter than the market wants.
Then we have the private credit side of the story.
This part is also important. When firms like Morgan Stanley, BlackRock, and BlackStone among others, start limiting withdrawals in private credit funds, it tells us something. It doesn't automatically mean crisis but it does mean that liquidity is not as strong as it looks in calm markets. That is the kind of thing we need to watch closely, because credit stress can spread into risk assets very quickly.
So for me, the bigger picture is this:
That doesn't mean 2026 has to become another 2008 GFC. The structure of the risk is different. But it means that the probability of recession or even stagflation is higher than many people want to admit right now.
So when I look at the S&P 500 chart here, I do not just see a technical setup. I see a market that may still be underpricing a macro environment that can get worse before it gets better.
What do you think? Do you think a recession is looming?
Share your thoughts with me in the comments.
In my opinion, the inversion is usually the warning, and the un-inversion is often when the economy starts to feel the pressure that the bond market had already priced in earlier.
- The New York Fed’s model, updated with data through January 2026, shows a January 2027 recession probability of 18.8%
The U.S. economy was already slowing down before this recent oil shock and the rising tension in the Middle East. U.S. real GDP growth for Q4 2025 was revised down to 0.7%, versus 4.4% in Q3, and the unemployment rate in February 2026 was 4.4%. That is not a collapse, but it is not a strong backdrop either.
In my recent post, “S&P and a very timely correction for the U.S. president”, I mentioned this chain:
Higher Oil Price --> Higher Inflation --> Higher Rates (or fewer cuts) --> Lower Corporate Profits --> Lower Equities
I still think that chain is very relevant.
Why? Because this is not just about oil going up on a headline. Oil is up sharply, and the Strait of Hormuz disruption is threatening a route that carries a very large share of global oil supply, more than 20%. If this persists, it can push transportation costs, production costs, and consumer costs higher again. That is how a geopolitical shock turns into a macro problem.
And we have seen this type of reaction before. During major geopolitical conflicts that affected energy markets, like the 1973 oil embargo, the 1979 Iranian shock, the 1990 Gulf crisis, and even the 2022 Russia-Ukraine war. As a result, oil moved higher, inflation pressure increased, and equities came under stress. Of course every cycle is different, but the pattern is often similar: when energy becomes more expensive, margins get tighter, growth slows down, and the S&P starts repricing that risk.
This is where the word stagflation becomes important.
For anyone new to the term, recession means slower growth, weaker demand, and a softer labor market.
Stagflation is when growth slows down while inflation stays high or moves higher again.
That is a much more difficult environment for the market, because the Fed cannot support the economy as easily if inflation is still being pushed up by energy. So even if growth weakens, policy may stay tighter than the market wants.
Then we have the private credit side of the story.
This part is also important. When firms like Morgan Stanley, BlackRock, and BlackStone among others, start limiting withdrawals in private credit funds, it tells us something. It doesn't automatically mean crisis but it does mean that liquidity is not as strong as it looks in calm markets. That is the kind of thing we need to watch closely, because credit stress can spread into risk assets very quickly.
So for me, the bigger picture is this:
- Old yield curve warning still matters
- Growth was already slowing
- Oil shock is adding fresh inflation pressure
- That limits how supportive the Fed can be
- And private credit is starting to show signs of stress
That doesn't mean 2026 has to become another 2008 GFC. The structure of the risk is different. But it means that the probability of recession or even stagflation is higher than many people want to admit right now.
So when I look at the S&P 500 chart here, I do not just see a technical setup. I see a market that may still be underpricing a macro environment that can get worse before it gets better.
What do you think? Do you think a recession is looming?
Share your thoughts with me in the comments.

Publications connexes
Clause de non-responsabilité
Les informations et publications ne sont pas destinées à être, et ne constituent pas, des conseils ou recommandations financiers, d'investissement, de trading ou autres fournis ou approuvés par TradingView. Pour en savoir plus, consultez les Conditions d'utilisation.
Publications connexes
Clause de non-responsabilité
Les informations et publications ne sont pas destinées à être, et ne constituent pas, des conseils ou recommandations financiers, d'investissement, de trading ou autres fournis ou approuvés par TradingView. Pour en savoir plus, consultez les Conditions d'utilisation.