
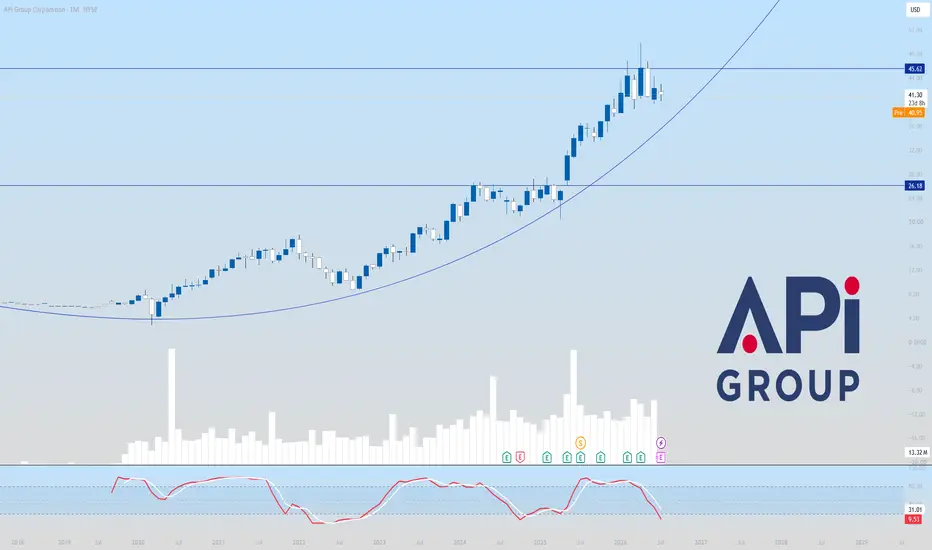
APi Group Corporation has quietly become one of the strongest performing companies in the industrial services sector. Rather than relying on cyclical construction projects, the company generates much of its revenue from recurring inspection, maintenance, and repair services for fire protection, life safety, security, and elevator systems
These services are often required by law or insurance regulations, giving APi a resilient business model that performs well even during slower economic periods. With more than 500 locations worldwide and a growing customer base across healthcare, education, manufacturing, commercial real estate, and data centers, the company has built a diversified platform that continues to expand through both organic growth and strategic acquisitions
Financial performance has remained impressive over the past year. APi reported record 2025 revenue of $7.91 billion, representing 12.7% year over year growth, while net income climbed more than 20% to $302 million. Profitability also continued improving, with adjusted EBITDA margins reaching 13.2%, supported by operating efficiencies and successful integration of acquired businesses
The momentum carried into Q1 2026, where revenue increased 15.3% year over year to $1.98 billion, including an impressive 10.4% organic growth rate, showing that expansion is being driven by healthy underlying demand rather than acquisitions alone. Strong free cash flow generation and a conservative 1.6x net leverage ratio also leave the company with ample financial flexibility for future investments
One of APi's biggest strengths is its acquisition strategy
Management has consistently acquired high-quality fire protection and specialty service businesses, including recent deals such as OnyxFire Protection Services and WTech Fire Group, which expand both recurring revenue and geographic reach. These acquisitions, combined with steady demand from fast growing markets like hyperscale data centers, healthcare facilities, advanced manufacturing, and critical infrastructure, have prompted management to raise its 2026 guidance multiple times. The company now expects approximately $8.5–8.8 billion in revenue and $1.15–1.23 billion in adjusted EBITDA this year while continuing to execute its long term "10/16/60+" strategy focused on organic growth, higher margins, and strong free cash flow conversion
Despite trading at roughly 27 times forward earnings, many investors believe APi deserves its premium valuation because of its predictable recurring revenue, consistent margin expansion, disciplined capital allocation, and resilient business model. Wall Street remains largely bullish, with most analysts maintaining Strong Buy or Moderate Buy ratings and average price targets between $52 and $54, implying approximately 25% to 30% upside from current levels. Still, investors should recognize the risks
The company must continue successfully integrating acquisitions, manage labor shortages and wage inflation, and navigate slower construction activity that could affect its project based business. Its relatively high beta also means the stock can experience above average volatility during broader market selloffs
APi Group offers an attractive combination of defensive characteristics and long term growth potential that is uncommon in the industrial sector
The company's recurring service model provides stable cash flow, while acquisitions and exposure to expanding industries such as data centers continue to drive revenue and earnings higher. Upcoming quarterly earnings, additional acquisition announcements, and progress toward management's long term financial targets will be important catalysts to watch.
Trade aktif
APi Group delivered a strong Q2 2026, with revenue rising 13.3% year over year to $2.25 billion, organic growth reaching 10.1%, and adjusted EBITDA increasing 14.3% to $311 million. Management raised its full year 2026 guidance, backed by a record $5 billion-plus backlog and continued acquisition activity, including WTech Fire Group and Onyx-Fire. The company is also benefiting from demand tied to data centers and its inspection-focused recurring revenue model, while analysts remain positive. The main risks are valuation, debt levels, and successfully integrating its growing portfolio of acquisitions
Publikasi terkait
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.
Publikasi terkait
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.