
BTSG - BrightSpring Health Services (BTSG): A High-Growth Roll-Up in the Vital Post-Acute Care Arena
BrightSpring Health Services, Inc. (NASDAQ: BTSG) has emerged as one of the standout performers in the healthcare sector in 2025, with its shares skyrocketing over 120% year-to-date and recently reaching a new 52-week high. This explosive performance raises the pivotal question for investors: Is this a speculative frenzy, or does it represent the justified market recognition of a fundamental transformation within a critical, fragmented, and recession-resistant industry? A deeper examination suggests that while the valuation now demands greater scrutiny, the company's compelling growth narrative, operational execution, and entrenched market position present a strong case for continued holding, albeit with a defined framework for risk management.
The Investment Thesis: Consolidating a Fragmented, Essential Market
BrightSpring operates at the vital intersection of healthcare delivery and the home, providing a comprehensive suite of post-acute care and pharmacy services. Its business model is built on two powerful pillars:
The Roll-Up Strategy in a Fragmented Landscape: The post-acute and home health sector is notoriously fragmented, populated by thousands of small, regional providers. BrightSpring’s core strategy is to act as a consolidator, acquiring these businesses to achieve national scale, realize significant cost synergies, and leverage a unified technology and administrative platform. This "buy-and-build" approach can create tremendous value if executed well, as evidenced by the company's accelerating revenue growth.
Exposure to Powerful Demographic Tailwinds: The company's services are driven by the irreversible aging of the population, the increasing preference for aging in place (home-based care over institutional settings), and the healthcare system's push to lower costs by managing patients effectively outside of expensive hospital stays. These are long-term, structural trends that provide a durable demand foundation.
Operational Excellence: Translating Strategy into Financial Performance
The stock's remarkable rally is firmly underpinned by exceptional operational and financial results, moving beyond mere speculation:
Consistent Earnings Surprises: BrightSpring has beaten consensus earnings estimates in each of the last four quarters, demonstrating its ability to not only grow but to do so more profitably than the market anticipates. The most recent quarter saw an EPS beat alongside a 5.46% revenue surprise, signaling strong top-line execution.
Explosive Growth Trajectory: Analyst projections are breathtaking, with current fiscal year EPS expected to surge 89.29% on 12.85% revenue growth. Even more impressive, the following year calls for 31.54% earnings growth on a 14.55% revenue increase, indicating a path of sustained, high-quality expansion.
Superior Momentum and Growth Scores: The company's perfect 'A' Growth Score from Zacks formally quantifies this outstanding trajectory, while its combined VGM Score of 'A' highlights its overall attractiveness based on style factors.
The Crucial Valuation Question: Premium Price for Premium Growth?
This is where the investor's dilemma crystallizes. Success has come at a cost, and that cost is a premium valuation. Trading at 35.3x current fiscal year EPS estimates, BrightSpring commands a significant premium over its peer industry average of 15.4x. Its price-to-cash-flow multiple of 20x also dwarfs the peer group average of 10.9x.
However, context is critical. For high-growth companies in the consolidation phase, traditional valuation multiples often appear stretched. The more telling metric may be the PEG Ratio (Price/Earnings to Growth) of 0.66. A PEG below 1.0 can suggest that even at its elevated P/E, the stock may still be reasonably valued relative to its exceptional projected earnings growth rate. The company's 'B' Value Score indicates that while not a deep value play, its price may be justified by its growth profile for investors focused on that style.
Technical Analysis: Defining Support in a High-Flying Stock
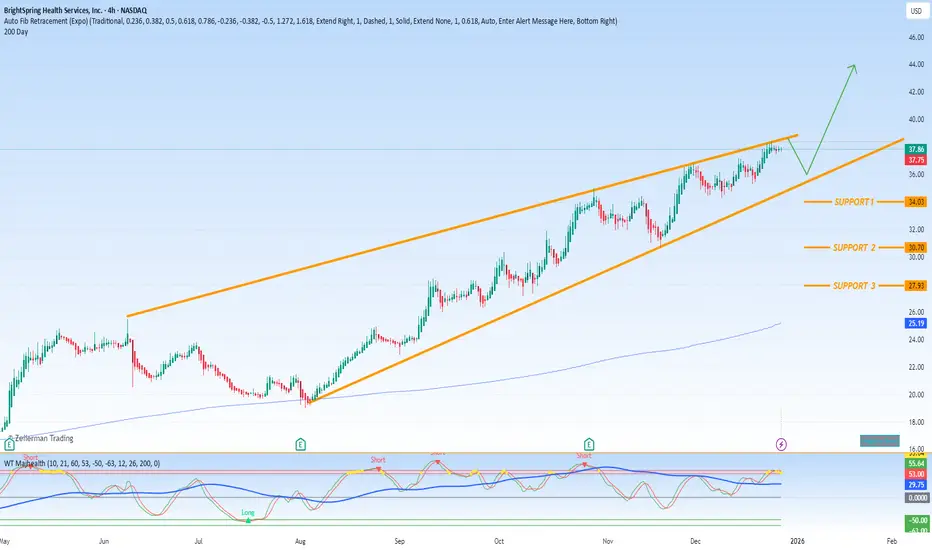
After such a parabolic rise, identifying levels where the stock might find stability on any pullback is essential for risk management and potential entry. The chart reveals several key support zones:
Near-Term Support Zone at ~$34: This area, just below the recent all-time high, represents the first line of defense. A successful hold here would indicate that the bullish momentum remains powerfully intact and that investors are using minor dips as buying opportunities to participate in the story.
Intermediate Support Zone at ~$30: This is a more significant psychological and technical level. A pullback to $30 would represent a healthy, double-digit correction that could work off overbought conditions. It would be a critical test of whether the institutional money supporting the rally is committed for the long term.
Major Value & Conviction Support Zone at ~$28: A decline to this deeper level would signal a more substantial reset, likely triggered by a broader market downturn or a rare earnings disappointment. For long-term believers in the consolidation story, this zone would represent a high-conviction buying area, offering a much-improved margin of safety and a potential discount to the prevailing growth narrative.
Investment Verdict: Hold with a Disciplined Plan
For existing shareholders, the decision to hold BrightSpring hinges on investment horizon and risk tolerance.
The case for holding is strong: The underlying business is performing superbly, capitalizing on powerful secular trends and demonstrating consistent operational excellence. The growth runway, both organic and through acquisitions, appears long. Exiting simply because the stock has risen dramatically could mean missing the bulk of a multi-year growth story.
However, prudent risk management is non-negotiable. The premium valuation means the stock is vulnerable to volatility and sentiment shifts. Any stumble in growth rates or a broader market de-rating of high-multiple stocks could lead to a sharp correction.
Therefore, a balanced approach is recommended:
Continue to hold core positions for long-term growth, trusting in the fundamental execution.
Use the identified support zones ($34, $30, $28) as guides. Consider these levels for potential scaling-in of new capital or for setting stop-loss parameters to protect realized gains.
Monitor quarterly execution meticulously. In a story stock trading at a premium, consistent delivery on growth and synergy targets is paramount.
BrightSpring is not a low-risk, steady-eddie investment. It is a high-octane growth vehicle in an essential sector. For investors who identified the opportunity earlier, the rally is a validation of their thesis. For those considering an entry or managing an existing position, the path forward involves respecting the momentum while anchoring decisions to both the robust fundamentals and the clear technical levels that now define its chart.
BrightSpring Health Services, Inc. (NASDAQ: BTSG) has emerged as one of the standout performers in the healthcare sector in 2025, with its shares skyrocketing over 120% year-to-date and recently reaching a new 52-week high. This explosive performance raises the pivotal question for investors: Is this a speculative frenzy, or does it represent the justified market recognition of a fundamental transformation within a critical, fragmented, and recession-resistant industry? A deeper examination suggests that while the valuation now demands greater scrutiny, the company's compelling growth narrative, operational execution, and entrenched market position present a strong case for continued holding, albeit with a defined framework for risk management.
The Investment Thesis: Consolidating a Fragmented, Essential Market
BrightSpring operates at the vital intersection of healthcare delivery and the home, providing a comprehensive suite of post-acute care and pharmacy services. Its business model is built on two powerful pillars:
The Roll-Up Strategy in a Fragmented Landscape: The post-acute and home health sector is notoriously fragmented, populated by thousands of small, regional providers. BrightSpring’s core strategy is to act as a consolidator, acquiring these businesses to achieve national scale, realize significant cost synergies, and leverage a unified technology and administrative platform. This "buy-and-build" approach can create tremendous value if executed well, as evidenced by the company's accelerating revenue growth.
Exposure to Powerful Demographic Tailwinds: The company's services are driven by the irreversible aging of the population, the increasing preference for aging in place (home-based care over institutional settings), and the healthcare system's push to lower costs by managing patients effectively outside of expensive hospital stays. These are long-term, structural trends that provide a durable demand foundation.
Operational Excellence: Translating Strategy into Financial Performance
The stock's remarkable rally is firmly underpinned by exceptional operational and financial results, moving beyond mere speculation:
Consistent Earnings Surprises: BrightSpring has beaten consensus earnings estimates in each of the last four quarters, demonstrating its ability to not only grow but to do so more profitably than the market anticipates. The most recent quarter saw an EPS beat alongside a 5.46% revenue surprise, signaling strong top-line execution.
Explosive Growth Trajectory: Analyst projections are breathtaking, with current fiscal year EPS expected to surge 89.29% on 12.85% revenue growth. Even more impressive, the following year calls for 31.54% earnings growth on a 14.55% revenue increase, indicating a path of sustained, high-quality expansion.
Superior Momentum and Growth Scores: The company's perfect 'A' Growth Score from Zacks formally quantifies this outstanding trajectory, while its combined VGM Score of 'A' highlights its overall attractiveness based on style factors.
The Crucial Valuation Question: Premium Price for Premium Growth?
This is where the investor's dilemma crystallizes. Success has come at a cost, and that cost is a premium valuation. Trading at 35.3x current fiscal year EPS estimates, BrightSpring commands a significant premium over its peer industry average of 15.4x. Its price-to-cash-flow multiple of 20x also dwarfs the peer group average of 10.9x.
However, context is critical. For high-growth companies in the consolidation phase, traditional valuation multiples often appear stretched. The more telling metric may be the PEG Ratio (Price/Earnings to Growth) of 0.66. A PEG below 1.0 can suggest that even at its elevated P/E, the stock may still be reasonably valued relative to its exceptional projected earnings growth rate. The company's 'B' Value Score indicates that while not a deep value play, its price may be justified by its growth profile for investors focused on that style.
Technical Analysis: Defining Support in a High-Flying Stock
After such a parabolic rise, identifying levels where the stock might find stability on any pullback is essential for risk management and potential entry. The chart reveals several key support zones:
Near-Term Support Zone at ~$34: This area, just below the recent all-time high, represents the first line of defense. A successful hold here would indicate that the bullish momentum remains powerfully intact and that investors are using minor dips as buying opportunities to participate in the story.
Intermediate Support Zone at ~$30: This is a more significant psychological and technical level. A pullback to $30 would represent a healthy, double-digit correction that could work off overbought conditions. It would be a critical test of whether the institutional money supporting the rally is committed for the long term.
Major Value & Conviction Support Zone at ~$28: A decline to this deeper level would signal a more substantial reset, likely triggered by a broader market downturn or a rare earnings disappointment. For long-term believers in the consolidation story, this zone would represent a high-conviction buying area, offering a much-improved margin of safety and a potential discount to the prevailing growth narrative.
Investment Verdict: Hold with a Disciplined Plan
For existing shareholders, the decision to hold BrightSpring hinges on investment horizon and risk tolerance.
The case for holding is strong: The underlying business is performing superbly, capitalizing on powerful secular trends and demonstrating consistent operational excellence. The growth runway, both organic and through acquisitions, appears long. Exiting simply because the stock has risen dramatically could mean missing the bulk of a multi-year growth story.
However, prudent risk management is non-negotiable. The premium valuation means the stock is vulnerable to volatility and sentiment shifts. Any stumble in growth rates or a broader market de-rating of high-multiple stocks could lead to a sharp correction.
Therefore, a balanced approach is recommended:
Continue to hold core positions for long-term growth, trusting in the fundamental execution.
Use the identified support zones ($34, $30, $28) as guides. Consider these levels for potential scaling-in of new capital or for setting stop-loss parameters to protect realized gains.
Monitor quarterly execution meticulously. In a story stock trading at a premium, consistent delivery on growth and synergy targets is paramount.
BrightSpring is not a low-risk, steady-eddie investment. It is a high-octane growth vehicle in an essential sector. For investors who identified the opportunity earlier, the rally is a validation of their thesis. For those considering an entry or managing an existing position, the path forward involves respecting the momentum while anchoring decisions to both the robust fundamentals and the clear technical levels that now define its chart.

Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.