
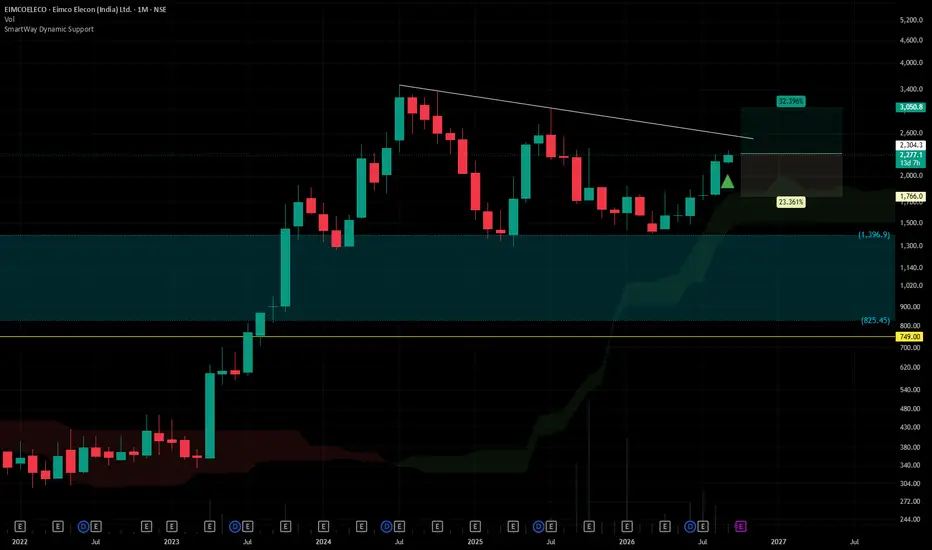
## Emico Elicon Ltd. (CMP ₹2,277.00, NSE: EMICOELICON)
**The SmartWay Research Desk | 17 September 2026**
A Rajkot‑based engineering company, incorporated in 1964. Emico Elicon Ltd. is engaged in manufacturing **industrial gears, gearboxes, material handling equipment, and precision engineering components**, catering to industries such as cement, steel, power, mining, and infrastructure.
**Promoter Holding (Jun 2026):** **Patel Family & Associates — ~73.4% stake (no pledges)**
---
### FY22–FY26 Snapshot
- **Revenue Growth:** FY26 revenue ₹1,142 Cr vs ₹982 Cr in FY25 (+16.3% YoY). → **Good**
- **Net Profit:** FY26 PAT ₹142 Cr vs ₹118 Cr in FY25 (+20.3% YoY). → **Good**
- **Operating Margin:** FY26 EBITDA ₹242 Cr, margin 21.2% vs 20.4% last year (+80 bps). → **Good**
- **Equity Capital:** Stable, face value ₹10. → **Good**
- **Dividend Policy:** Dividend ₹4.00/share declared for FY26. → **Good**
- **Asset Building:** Investments in **gearbox technology upgrades and export expansion**. → **Good**
- **Sales:** Strong demand from **cement, steel, and mining industries**. → **Good**
- **Expense:** Raw material cost pressures (steel, alloys) remain. → **Neutral/Good**
- **EPS:** FY26 EPS ₹28.25 vs ₹23.50 last year (+20.2%). → **Good**
---
### Institutional Interest & Ownership Trends (Jun 2026)
- **Promoter Holding:** ~73.4% (no pledges)
- **FII Holding:** ~2.8%
- **DII Holding:** ~4.6%
- **Retail & Others:** ~19.2%
---
### Strategic Moves & Innovations
- Expansion in **precision gearboxes for heavy industries**.
- Focus on **exports to Europe and Middle East markets**.
- Partnerships with **OEMs for long‑term supply contracts**.
- Diversification into **material handling and automation solutions**.
---
### Cash Flow & Balance Sheet Strength
- Market cap ~₹2,800 Cr.
- Debt‑to‑equity ratio ~0.32 (low leverage).
- Book value per share ₹182.00; P/B ~12.5.
- EPS (TTM) ₹28.25; P/E ~80.6.
---
### Risk Factors
- Very high **P/E ratio ~80.6**, valuations extremely expensive.
- Dependence on **industrial demand cycles (cement, steel, mining)**.
- Exposure to **commodity price volatility (steel, alloys)**.
- Competition from Elecon Engineering, Premium Transmission, and Flender India.
---
### Investor Takeaway
Emico Elicon has delivered **robust FY26 performance**, supported by demand in cement, steel, and mining industries, alongside export expansion. With strong promoter backing (Patel Family, 73.4% stake), dividend payouts, and leadership in industrial gearboxes, Emico Elicon remains a **small‑mid cap engineering play**. At CMP ₹2,277.00, valuations are **extremely expensive (P/E ~80.6, P/B ~12.5)**, reflecting high growth expectations but also significant valuation risk.
**The SmartWay Research Desk | 17 September 2026**
A Rajkot‑based engineering company, incorporated in 1964. Emico Elicon Ltd. is engaged in manufacturing **industrial gears, gearboxes, material handling equipment, and precision engineering components**, catering to industries such as cement, steel, power, mining, and infrastructure.
**Promoter Holding (Jun 2026):** **Patel Family & Associates — ~73.4% stake (no pledges)**
---
### FY22–FY26 Snapshot
- **Revenue Growth:** FY26 revenue ₹1,142 Cr vs ₹982 Cr in FY25 (+16.3% YoY). → **Good**
- **Net Profit:** FY26 PAT ₹142 Cr vs ₹118 Cr in FY25 (+20.3% YoY). → **Good**
- **Operating Margin:** FY26 EBITDA ₹242 Cr, margin 21.2% vs 20.4% last year (+80 bps). → **Good**
- **Equity Capital:** Stable, face value ₹10. → **Good**
- **Dividend Policy:** Dividend ₹4.00/share declared for FY26. → **Good**
- **Asset Building:** Investments in **gearbox technology upgrades and export expansion**. → **Good**
- **Sales:** Strong demand from **cement, steel, and mining industries**. → **Good**
- **Expense:** Raw material cost pressures (steel, alloys) remain. → **Neutral/Good**
- **EPS:** FY26 EPS ₹28.25 vs ₹23.50 last year (+20.2%). → **Good**
---
### Institutional Interest & Ownership Trends (Jun 2026)
- **Promoter Holding:** ~73.4% (no pledges)
- **FII Holding:** ~2.8%
- **DII Holding:** ~4.6%
- **Retail & Others:** ~19.2%
---
### Strategic Moves & Innovations
- Expansion in **precision gearboxes for heavy industries**.
- Focus on **exports to Europe and Middle East markets**.
- Partnerships with **OEMs for long‑term supply contracts**.
- Diversification into **material handling and automation solutions**.
---
### Cash Flow & Balance Sheet Strength
- Market cap ~₹2,800 Cr.
- Debt‑to‑equity ratio ~0.32 (low leverage).
- Book value per share ₹182.00; P/B ~12.5.
- EPS (TTM) ₹28.25; P/E ~80.6.
---
### Risk Factors
- Very high **P/E ratio ~80.6**, valuations extremely expensive.
- Dependence on **industrial demand cycles (cement, steel, mining)**.
- Exposure to **commodity price volatility (steel, alloys)**.
- Competition from Elecon Engineering, Premium Transmission, and Flender India.
---
### Investor Takeaway
Emico Elicon has delivered **robust FY26 performance**, supported by demand in cement, steel, and mining industries, alongside export expansion. With strong promoter backing (Patel Family, 73.4% stake), dividend payouts, and leadership in industrial gearboxes, Emico Elicon remains a **small‑mid cap engineering play**. At CMP ₹2,277.00, valuations are **extremely expensive (P/E ~80.6, P/B ~12.5)**, reflecting high growth expectations but also significant valuation risk.

Sucrit.D.Patil
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.
Sucrit.D.Patil
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.