
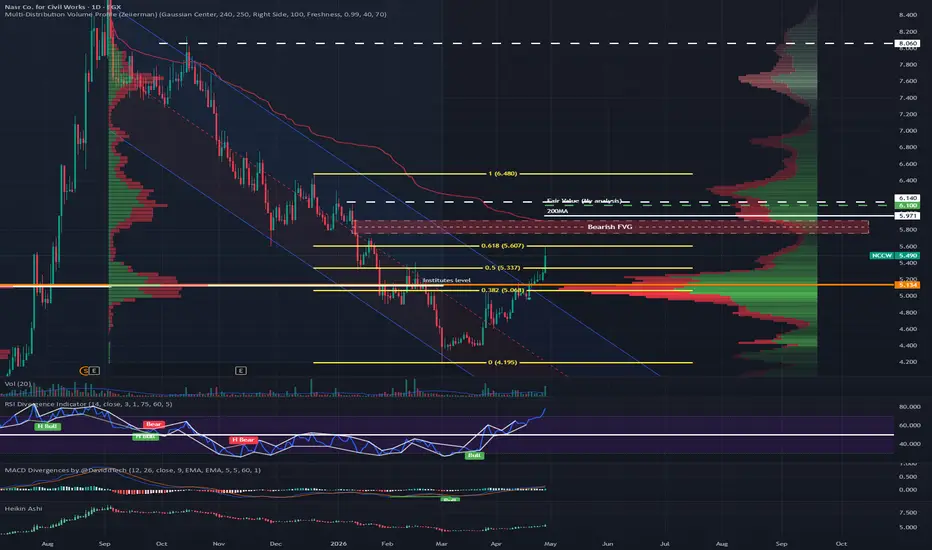
NCCW – Project Backlog vs. Margin Compression 📉🏗️
The Reality: I see a "Mid-Cap Contractor" currently stuck in a cooling cycle. 🌬️
While 2024 was stellar, the FY 2025 results show an 11.4% decline in net profit to EGP 60.35 million.
The story here is a "Margin Pinch" revenue was stable at EGP 348.7M, but domestic rising costs for materials and overhead are eating the bottom line. 🩹🏗️
The Regional Pivot: I note the company is looking outside for growth, recently signing a EUR 46M agreement in Uganda. 🌍
This expansion is vital because domestic margins are suffering.
However, I find the EPS of 0.29 EGP (down from 0.32 EGP) reflects the current struggle to maintain efficiency at home.
The Cash Flow Hurdle: I observe that cash conversion is tight.
NCCW is carrying significant "Work in Progress" on the balance sheet, a typical lag in civil works where milestones haven't yet turned into liquid cash.
While I appreciate that the earnings are 100% operational with no "one-off" fluff, the reliance on short-term credit to fund the project backlog is putting pressure on the debt-to-equity profile. ⚓💸
The Valuation: I find the 6.10 EGP Final Target leaves no meat on the bone.
By applying a premium 19.0x P/E to account for their historical "Zero-Debt" reputation and adding an asset strength premium for their EGP 951M book value, the target is technically sound but offers no upside from current interest levels. 🎯⚖️
Sharia Status: ❌ Non-Compliant.
I confirm that NCCW fails the quantitative screens for the EGX33 Shariah Index (April 2026).
The primary hurdles are the Interest Income, which frequently breaches the 5% purification threshold. ☪️🚫
Technical Analysis:
The Waiting Game – I see no immediate trigger. 🎢🧗
The Resistance: I've identified 6.14 as the critical level.
Since my fair value is 6.10, the price needs to break above this threshold to signal a new bullish trend that is actually worth trading. 🏹🧱
Verdict: I classify NCCW as a "Technical Pass." 🏗️🏎️
The fair value is too close to the current market price to justify the risk of high accruals and a declining bottom line.
I will wait for a structural change in earnings before looking at this stock again. 🛡️🔝
If I like my posts, I follow and boost 🙌
🎁 Get a $15 discount on your next subscription:
🔗 tradingview.com/pricing/?share_your_love=mnmabroukw36ix ✨💸

Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.