
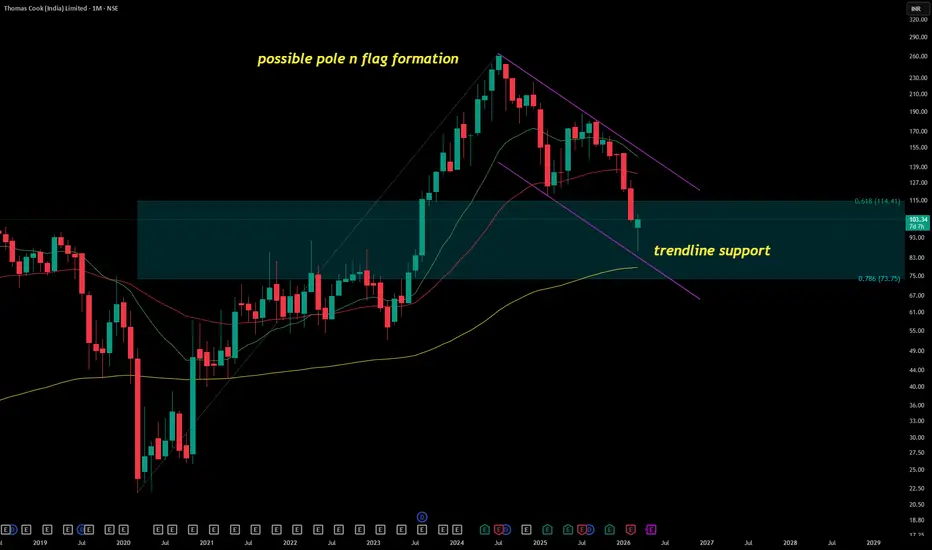
Thomas Cook (India) Ltd. (NSE: THOMASCOOK) is a mid‑cap travel services company offering foreign exchange, holiday packages, corporate travel, and visa services. It is part of the Fairfax Financial Holdings Group (Fairbridge Capital Mauritius Ltd.), which is the promoter. As of Dec 2025, promoters hold 63.83%, with balanced institutional and retail participation.
FY22–FY26 Snapshot
Revenue Growth: CAGR ~11–12% over FY22–FY26, driven by recovery in travel demand post‑COVID. → Good
Net Profit: FY26 PAT ~₹210 Cr, reflecting strong turnaround. → Good
Operating Margin: Maintained ~8–9%, moderate efficiency. → Neutral
Equity Capital: Stable, no major dilution. → Good
Dividend Policy: Yield ~1.2% (FY26), conservative payouts. → Neutral
Asset Building: Expansion of forex and travel services network. → Good
Sales: FY26 revenue crossed ₹6,200 Cr. → Good
Expense: High operating costs in travel services. → Neutral
EPS: ~₹6.4 in FY26, reflecting consistent profitability. → Good
Institutional Interest & Ownership Trends
Largest Promoter: Fairbridge Capital Mauritius Ltd. (Fairfax Group) – 63.83%
Largest FII: Foreign institutional investors – 7.28%
Largest DII: Domestic institutions – 6.83%
Retail & Others: ~16.54%
Strategic Moves & Innovations
Expansion into digital travel booking and forex platforms.
Focus on corporate travel management and MICE (Meetings, Incentives, Conferences, Exhibitions).
Investment in technology‑driven customer experience.
Strengthening partnerships with airlines and hotels globally.
Cash Flow & Balance Sheet Strength
Operating cash flows supported by travel demand recovery.
Debt levels moderate, manageable with steady profits.
Profit growth supports reinvestment in digital platforms.
Risk Factors
Dependence on global travel demand cycles.
Margin sensitivity to forex volatility and travel costs.
Competition from online travel agencies (MakeMyTrip, Yatra).
Exposure to geopolitical and pandemic risks.
Investor Takeaway
Thomas Cook (India) Ltd., backed by Fairfax Group via Fairbridge Capital Mauritius, is a leading travel services provider with strong promoter holding and balanced institutional interest. With most snapshot parameters rated Good, the company shows consistent EPS growth, robust asset building, and strong sales momentum. Investors should monitor travel demand cycles and forex volatility, but overall the outlook remains positive for long‑term holders.

Sucrit.D.Patil
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.
Sucrit.D.Patil
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.