
UNIP – Scrap Value vs. Financial Reality
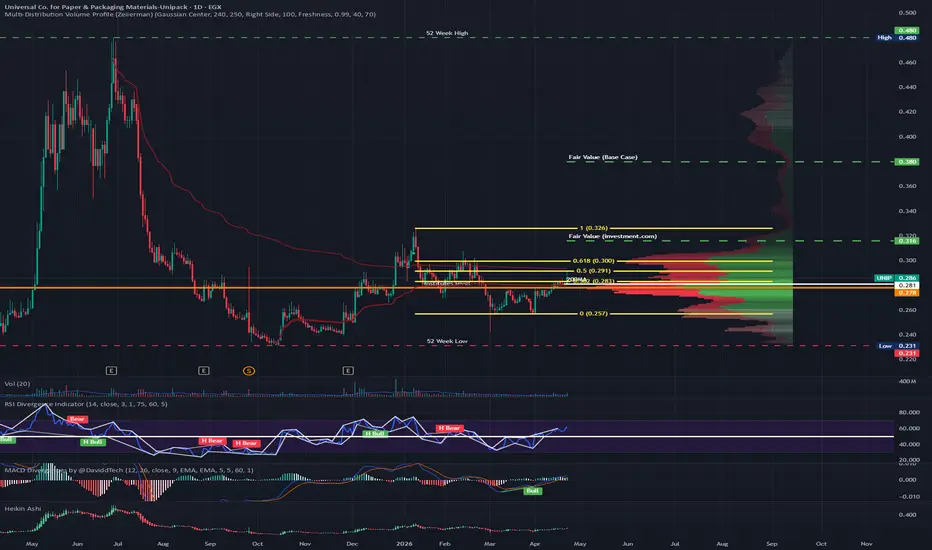
UNIP – Scrap Value vs. Financial Reality 📉📦
The Reality: A classic "Value Trap" in the penny stock realm. 🕸️
While revenue sits at EGP 1.37 billion, net income has collapsed by 87% to a mere EGP 13.05 million.
With a razor-thin net profit margin of 0.95%, the company is effectively dancing on the edge of a loss. ⛸️🔴
The Cash Squeeze: The balance sheet is under heavy fire. 📉
Less than 40% of operating profit is turning into cash, as liquidity remains trapped in slow-moving inventory.
With a staggering 111.7% Debt-to-Equity ratio, UNIP is gasping for air in this high-interest environment.
It’s currently "dead money" unless a miracle restructuring or merger occurs. 🩹🏦
The Valuation: On paper, it looks like a bargain, trading at EGP 0.28 less than half its Book Value of 0.63 EGP. 📚
While my mathematical Fair Value estimate of 0.380 EGP (using a recovery P/E of 18.5x) suggests upside, the market is currently pricing it at "scrap" value for a reason. 🧱⚖️
Sharia Status: ❌ Non-Compliant. UNIP fails the quantitative screens for the EGX33 Shariah Index (April 2026).
The heavy debt used to finance production and non-permissible interest income from its cash management break both the 30% and 5% thresholds. ☪️🚫
Verdict: A Cyclical Gamble.
UNIP is at a "Cyclical Bottom," but without a catalyst, it’s just a falling knife.
I don't even need to technical analysis this stock; enter at your own risk, but at least wait until it is over 0.30. 🛡️📉
If you like my posts, please follow and boost 🙌
🎁 Get a $15 discount on your next subscription:
🔗 tradingview.com/pricing/?share_your_love=mnmabroukw36ix ✨💸
The Reality: A classic "Value Trap" in the penny stock realm. 🕸️
While revenue sits at EGP 1.37 billion, net income has collapsed by 87% to a mere EGP 13.05 million.
With a razor-thin net profit margin of 0.95%, the company is effectively dancing on the edge of a loss. ⛸️🔴
The Cash Squeeze: The balance sheet is under heavy fire. 📉
Less than 40% of operating profit is turning into cash, as liquidity remains trapped in slow-moving inventory.
With a staggering 111.7% Debt-to-Equity ratio, UNIP is gasping for air in this high-interest environment.
It’s currently "dead money" unless a miracle restructuring or merger occurs. 🩹🏦
The Valuation: On paper, it looks like a bargain, trading at EGP 0.28 less than half its Book Value of 0.63 EGP. 📚
While my mathematical Fair Value estimate of 0.380 EGP (using a recovery P/E of 18.5x) suggests upside, the market is currently pricing it at "scrap" value for a reason. 🧱⚖️
Sharia Status: ❌ Non-Compliant. UNIP fails the quantitative screens for the EGX33 Shariah Index (April 2026).
The heavy debt used to finance production and non-permissible interest income from its cash management break both the 30% and 5% thresholds. ☪️🚫
Verdict: A Cyclical Gamble.
UNIP is at a "Cyclical Bottom," but without a catalyst, it’s just a falling knife.
I don't even need to technical analysis this stock; enter at your own risk, but at least wait until it is over 0.30. 🛡️📉
If you like my posts, please follow and boost 🙌
🎁 Get a $15 discount on your next subscription:
🔗 tradingview.com/pricing/?share_your_love=mnmabroukw36ix ✨💸

Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.